Bank statement loans are an innovative financing solution tailored primarily for self-employed individuals and those with unconventional income streams. Unlike traditional mortgage options, which generally require extensive documentation and income verification from standard pay stubs, bank statement loans simplify this process by allowing applicants to provide their bank statements as proof of income. This approach addresses a common pain point for borrowers whose income may fluctuate or not be easily documented through traditional means. By the end of this article, readers will have a thorough understanding of bank statement loans, their benefits, the documentation required, and how they compare to traditional mortgages. We will also explore the role Munshi Capital Inc plays in facilitating these loans for eligible borrowers.
Bank Statement Loans: Overview
Bank statement loans are categorized as alternative mortgage options designed for borrowers who may not qualify for conventional loans due to unique income patterns. These loans are particularly beneficial for self-employed individuals, freelancers, and small business owners who can demonstrate their income through bank statements instead of rigid documentation, such as W-2 forms. This flexibility in income verification allows additional accessibility to home financing for those often overlooked by traditional lenders.
What Defines a Bank Statement Loan Compared to Traditional Mortgages?
A bank statement loan differs from a traditional mortgage primarily in its income verification process and documentation requirements. Traditional mortgages typically require extensive documentation, including W-2 forms, tax returns, and proof of stable employment. In contrast, bank statement loans evaluate a borrower’s financial health based on bank statements over a set period, usually ranging from 12 to 24 months. This method focuses on actual cash flow rather than declared income, which can significantly benefit self-employed individuals who experience fluctuating earnings.
How Does a Bank Statement Loan Use Income Verification Differently?
Bank statement loans simplify the income verification process by focusing on the borrower’s cash flow. Rather than requiring pay stubs or tax returns, lenders analyze bank statements to gauge monthly income and spending behavior. This method not only allows for a more accurate understanding of financial stability but also accommodates applicants whose income might be less predictable due to seasonal work patterns or variable earnings. This flexibility facilitates the approval process for those who might struggle with traditional documentation requirements.
Who Typically Qualifies for Bank Statement Loans in the Mortgage Market?
Bank statement loans cater primarily to self-employed individuals and small business owners who may face challenges in providing traditional income documentation. Typically, qualifying borrowers include freelancers, contractors, and anyone with irregular or non-standard income streams. A crucial factor in qualifying is the applicant’s credit profile; favorable credit scores and a solid financial history enhance the chances of approval, as lenders seek assurance of the borrower’s ability to repay the loan.
What Are the Bank Statement Loan Requirements and Underwriting Criteria?
The requirements for obtaining a bank statement loan often include providing bank statements from the past 12-24 months, along with identity verification and self-employment documentation. Though less stringent than traditional loans, these criteria are crucial for the underwriting process. Understanding these requirements can facilitate a smoother application experience.
Which Documentation Is Necessary for Bank Statement Loan Approval?
To secure approval for a bank statement loan, borrowers typically need to submit a few key documents, which may include:
- Bank Statements: Proof of income over the last 12-24 months.
- Identification: Valid ID to verify the borrower’s identity.
- Self-Employment Documentation: Evidence of business ownership or freelance work.
These documents help ensure that lenders can accurately assess the borrower’s financial situation and repayment capability.
How Does the Underwriting Process Differ for Bank Statement Loans?
The underwriting process for bank statement loans differs from traditional mortgages in its approach to evaluating income and financial stability. Instead of relying heavily on standard documentation, underwriters focus on bank statements, which reflect the applicant’s real income and spending habits. This method allows for more flexible eligibility criteria, particularly suited to those with variable income. The underwriting process also tends to be faster, leading to quicker loan approvals compared to traditional methods.
What Are the Key Advantages and Limitations of Bank Statement Loans?
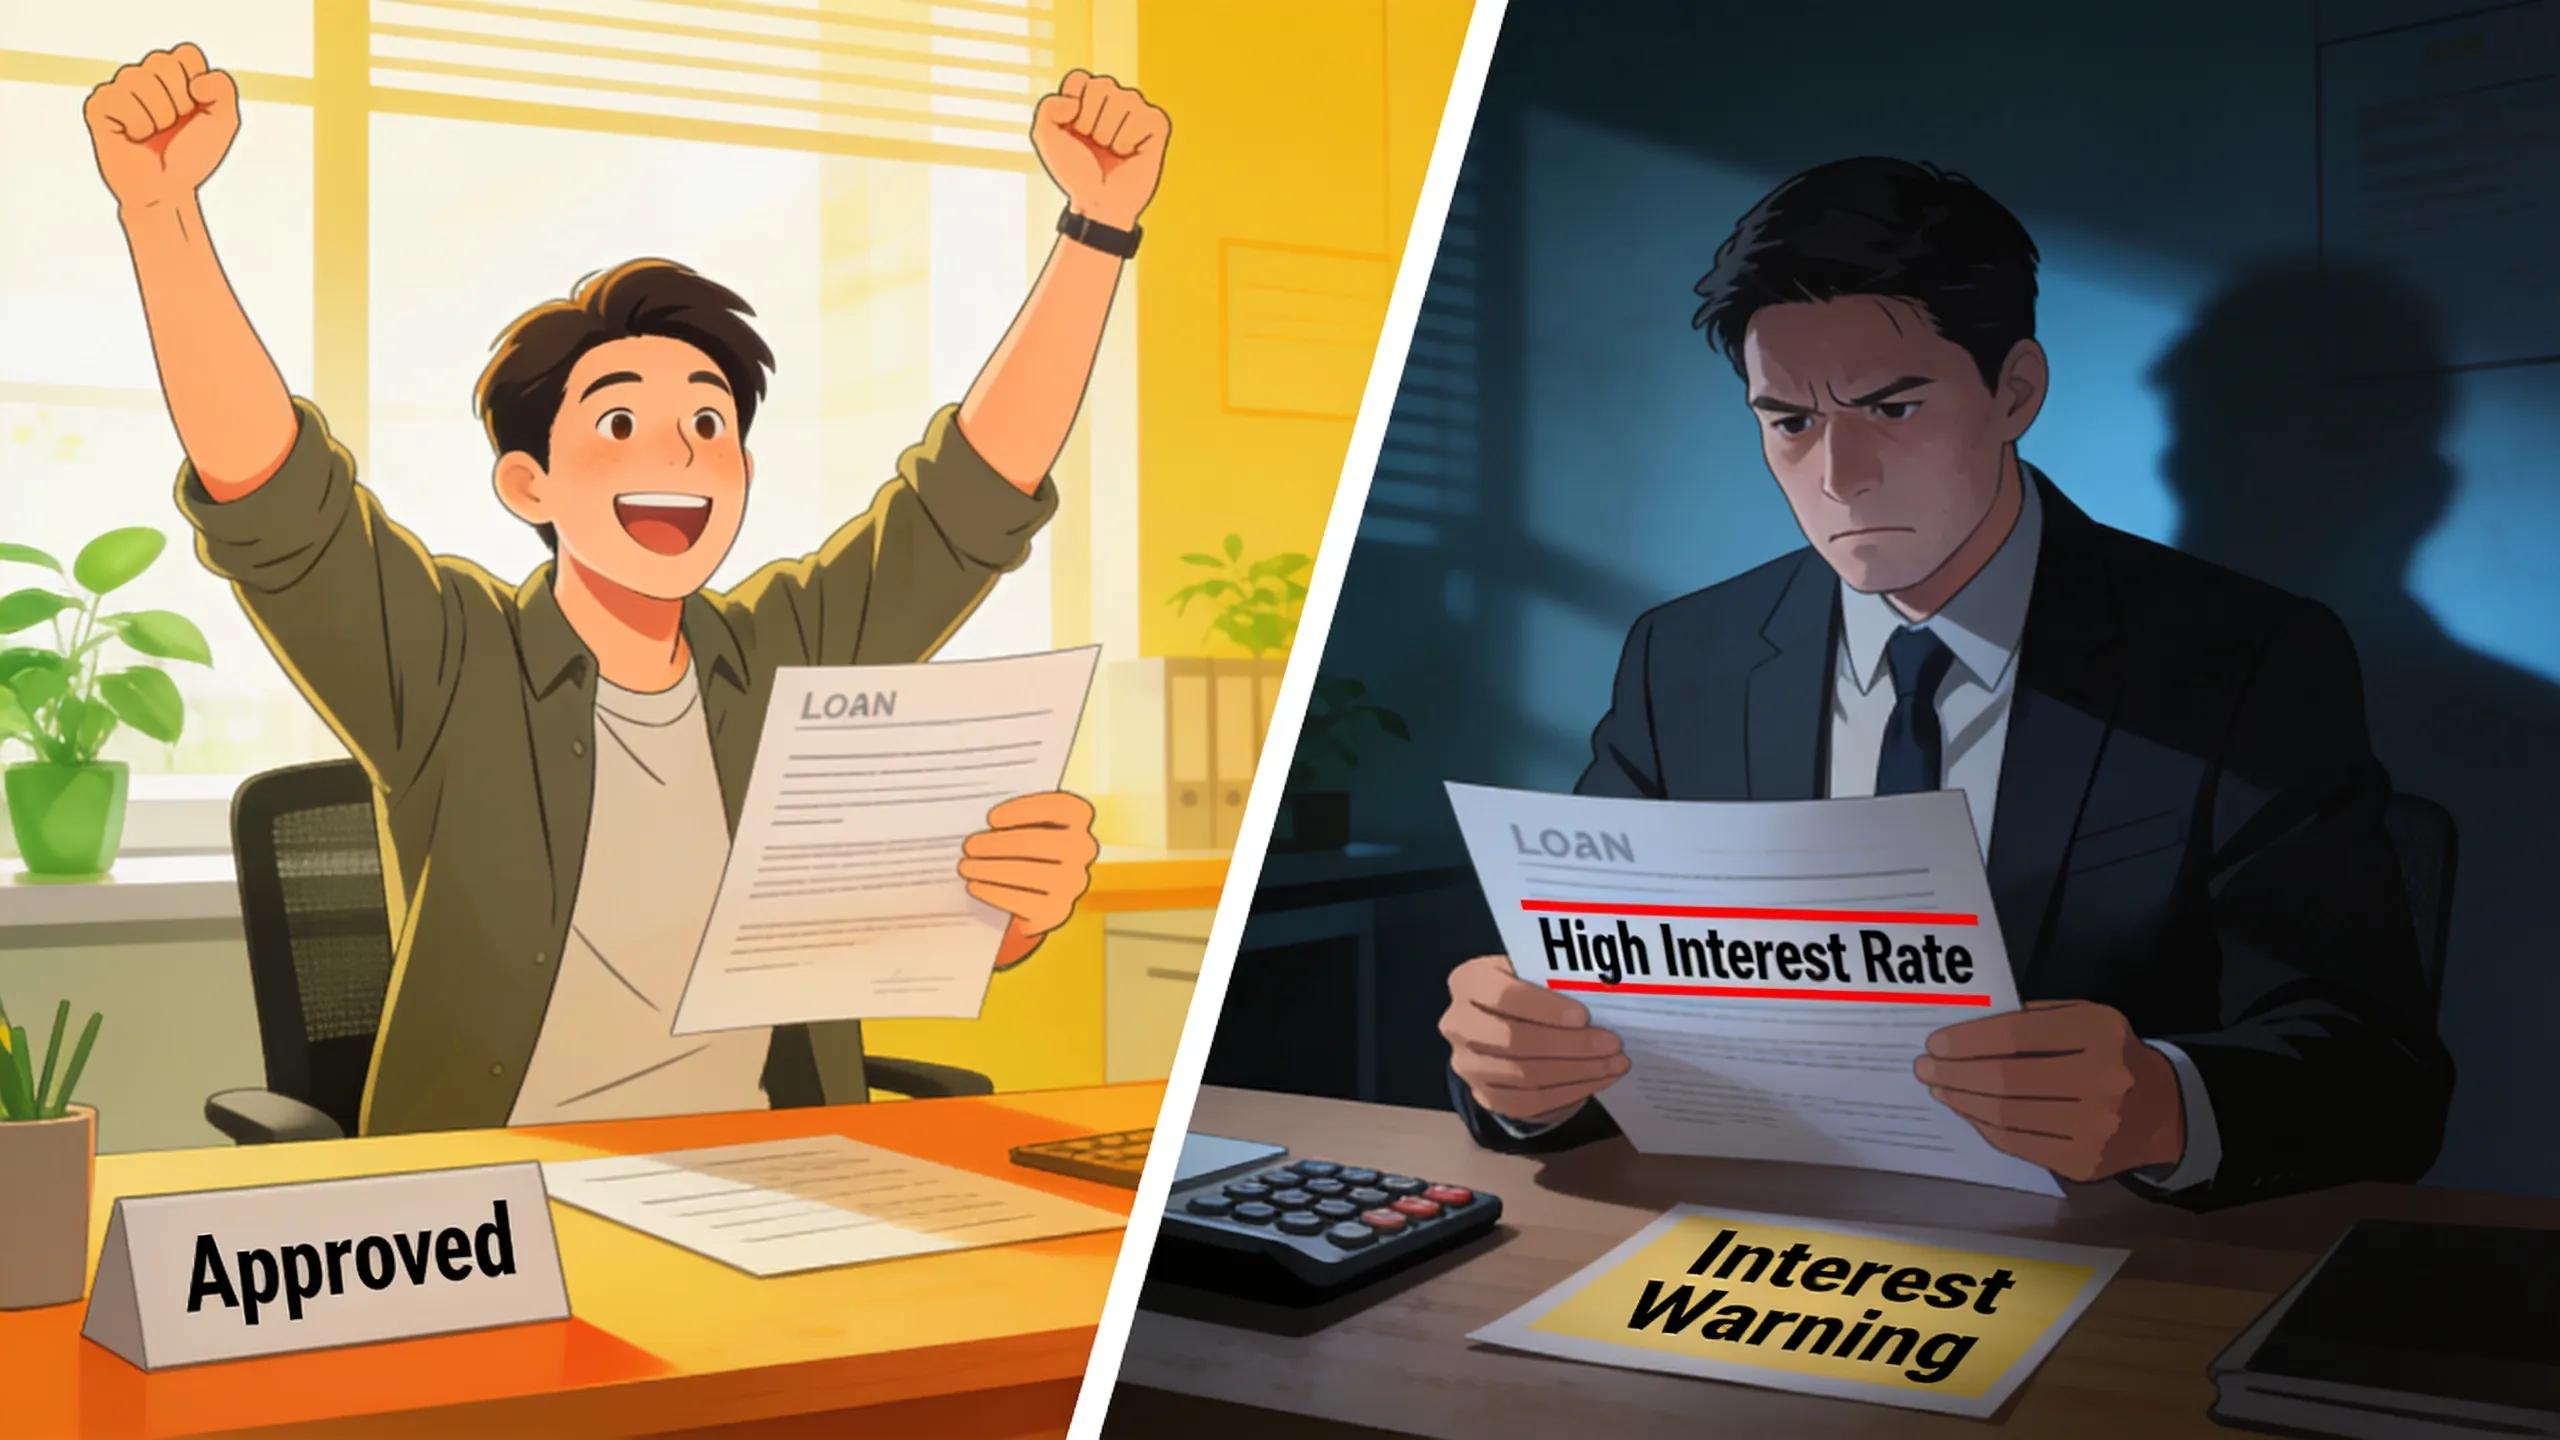
Understanding the advantages and limitations of bank statement loans can help potential borrowers make informed decisions. These loans provide unique benefits tailored for self-employed individuals while also presenting some drawbacks when compared to traditional mortgage options.
What Are the Primary Benefits for Self Employed and Real Estate Investors?
Bank statement loans offer several key benefits specifically for self-employed individuals and real estate investors, including:
- Easier Qualification: Simplified income verification allows more individuals to qualify for loans.
- Flexibility in Income Reporting: Varies in documentation requirements to cater to non-traditional income patterns.
- Faster Processing Times: Generally, quicker approvals mean borrowers can secure funding when they need it.
These aspects make bank statement loans particularly appealing for those navigating non-standard financial landscapes.
What Drawbacks Should Borrowers Consider Compared to Traditional Mortgage Options?
While bank statement loans present considerable benefits, they also come with certain drawbacks. Borrowers should be aware of:
- Higher Interest Rates: Typically, bank statement loans carry higher rates than standard mortgages due to increased lender risk.
- Larger Down Payments: These loans may require more substantial down payments than traditional options.
- Limited Availability: Not all lenders offer bank statement loans, making them harder to find.
These limitations necessitate careful evaluation when considering this type of loan.
How Does Munshi Capital Inc Facilitate Bank Statement Loans for Eligible Borrowers?
Munshi Capital Inc plays a pivotal role in connecting eligible borrowers to bank statement loans. With expertise in the lending landscape, the company streamlines the application process and provides valuable guidance for self-employed individuals seeking flexible mortgage solutions. This support significantly enhances the chances of securing funding for those who may find traditional methods challenging.
What Are the Service Features and Process Offered by Munshi Capital Inc?
Munshi Capital offers several unique service features for borrowers exploring bank statement loans:
- Personalized Application Assistance: Tailored support to navigate the loan process effectively.
- Flexible Income Qualification: Understanding of diverse income scenarios to determine eligibility.
- Efficient Processing: Commitment to fast lending processes reduces waiting times.
How Does Munshi Capital Incorporate Alternative Financing Solutions for Investors?
In addition to bank statement loans, Munshi Capital also provides alternative financing solutions for investors, such as:
- DSCR Loans: Designed for real estate investors without traditional income sources.
- Hard Money Loans: Short-term alternatives for immediate funding needs.
- Flexible Financing Options: Tailored solutions reflecting the unique needs of investors.
These features establish Munshi Capital as a versatile player in the lending market, addressing various borrower needs.
Leave a Reply