Jumbo loan options finance high-value properties exceeding conforming limits of pricing varies or $1,249,125 in high-cost markets. Munshi Capital Inc. structures jumbo financing for primary residences, vacation homes, and investment properties nationwide, including California’s luxury markets. Strong credit, income documentation, and reserves qualify borrowers for competitive rates, with piggyback and asset-based alternatives available for unique financial profiles.
Key Takeaways
- Jumbo loans finance properties exceeding the $832,750 conforming loan limit set by Fannie Mae and Freddie Mac.
- Strong credit scores, substantial income documentation, and significant reserves are essential qualification requirements for jumbo financing.
- Fixed-rate, adjustable-rate, and interest-only loan terms provide flexible options tailored to your high-value property financing needs.
- Strategic refinancing and tax advantages make jumbo loans effective tools for optimizing wealth in expensive real estate markets.
What Counts as a Jumbo Loan Today?
A mortgage earns the jumbo classification once its amount exceeds the loan-servicing limits set by Fannie Mae. Freddie Mac, currently $832,750 for a single-family home in most states. High-value properties, from hillside estates to custom-built luxury residences, routinely sell above that threshold, pushing their financing into jumbo territory. This jumbo mortgage info matters because conventional conforming loans simply do not stretch far enough to cover these purchase prices.
Currently $832,750 for a single-family home in all states but rise to $1,249,125 in designated high-cost markets. Buyers targeting high-value properties in these pricier regions benefit from the higher ceiling. Many luxury homes still exceed even that elevated figure. Munshi Capital Inc. serves high-value property buyers wherever these limits apply, structuring financing around the local benchmark rather than a one-size-fits-all number.
High-value home loans come with tighter underwriting standards than standard mortgages. Lenders ask for more documentation and larger reserves because the loan amounts carry greater risk. In exchange, qualified borrowers gain access to financing for luxury properties and high-cost real estate that conforming loans cannot touch.
How Do Jumbo Loans Differ From Conforming Loans?
Conforming loans stay within Fannie Mae and Freddie Mac limits and follow standardized underwriting rules. Jumbo loans exceed those limits and require stricter qualification, including stronger credit profiles and deeper financial reserves. The tradeoff: jumbo financing unlocks properties priced well beyond what a conforming loan can fund.
Buyers working from a complete jumbo loan guide understand this distinction before shopping for a high-value property.
What Loan Terms Can You Choose?
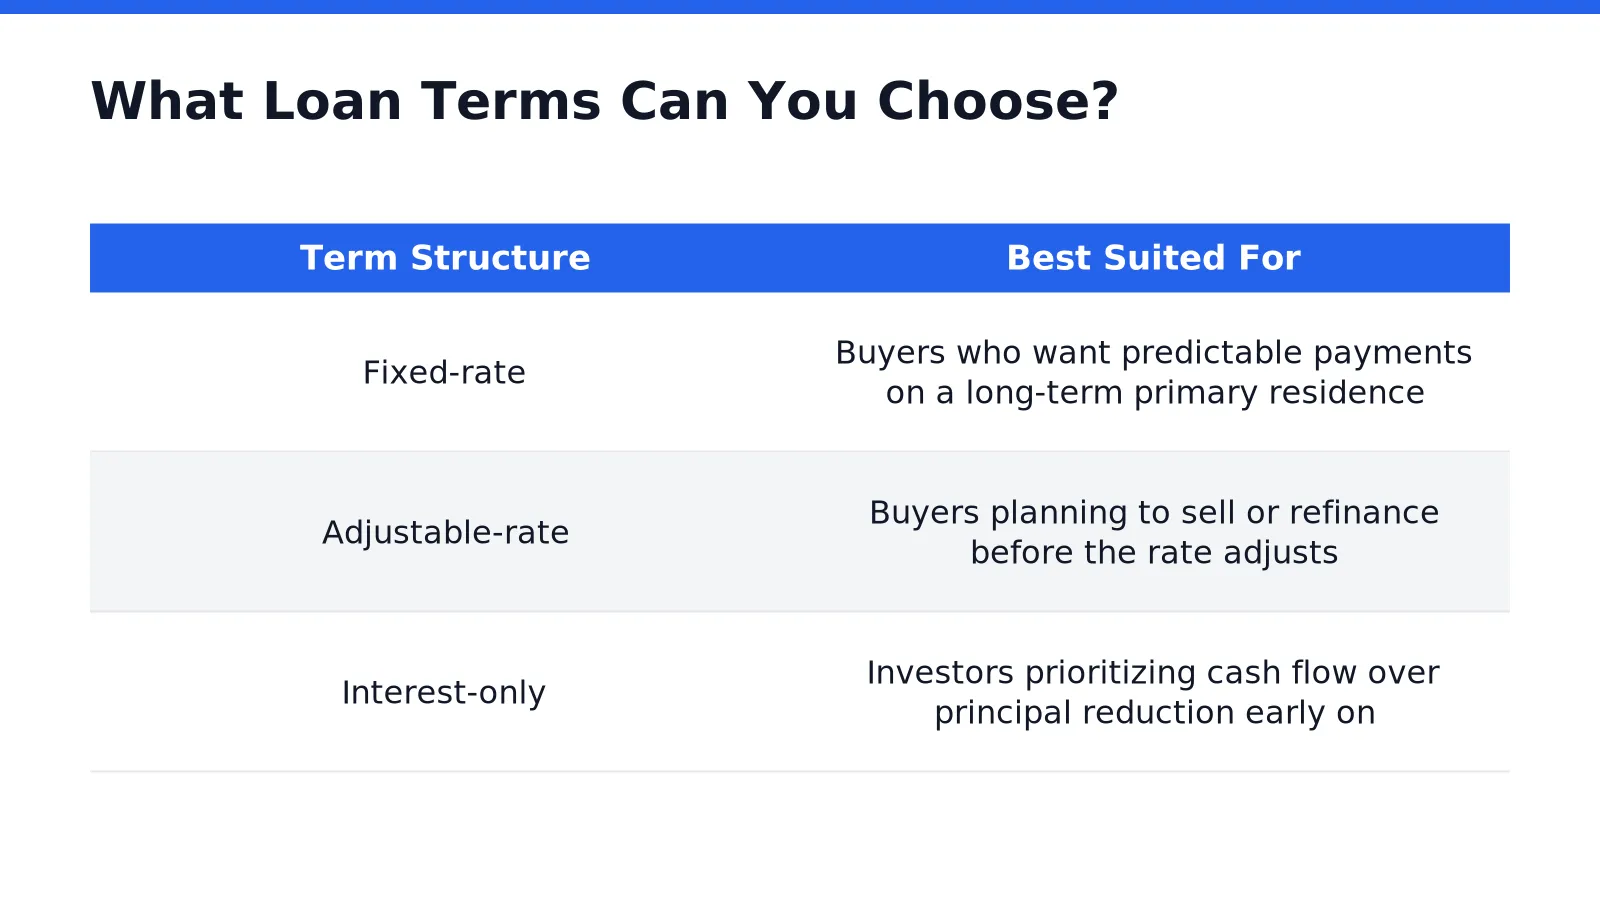
Jumbo financing for high-value properties comes structured three ways: fixed-rate, adjustable-rate, and interest-only. Each structure suits a different ownership timeline. A jumbo mortgage information review helps buyers match the term to how long they intend to hold the property and how income flows in.
Property type matters just as much as rate structure. Jumbo loans apply to primary residences, second or vacation homes. Investment properties alike, so a single borrower can finance a coastal retreat and a rental portfolio under the same lending relationship. This flexibility makes jumbo products a central piece of any serious high-value home loans strategy. High-net-worth buyers rarely limit their holdings to one property type.
Can a jumbo loan finance a vacation home or investment property?
Yes. Jumbo financing covers primary residences, vacation homes, and investment properties, giving affluent buyers room to diversify. A buyer financing a luxury second home in wine country faces the same structural choices as someone financing a primary estate.
Which term works best for a high-value property investor?
Adjustable-rate and interest-only structures often appeal to investors who expect to sell, refinance, or reposition the asset within a few years. Fixed-rate terms suit long-term holders. Munshi Capital Inc. walks buyers through this jumbo loan guide decision point before locking a rate, matching the structure to the property’s intended use.
How Do Rates and Qualification Work?
Qualification for financing on high-value properties hinges on three pillars: credit strength, income documentation, and cash reserves. Lenders scrutinize each factor closely before approving a jumbo mortgage on a luxury purchase. Weak reserves or inconsistent income derail applications that would otherwise sail through underwriting.
Pricing works differently than many affluent buyers expect. Borrowers with strong credit profiles often secure rates comparable to, or even lower than, standard conforming loans. That advantage disappears quickly for applicants with thin credit files or inconsistent income history. Preparation matters as much as net worth.
Are jumbo loan rates higher than conventional rates?
Not necessarily. Rate parity depends almost entirely on credit quality. Jumbo financing typically comes with stricter underwriting standards, higher rate potential for weaker applicants, and larger down payment requirements than standard mortgages carry. Buyers with excellent credit, however, frequently land terms that rival or beat conventional pricing on comparable properties.
Does a jumbo loan require mortgage insurance?
Often, no. Many high-value home loans skip private mortgage insurance entirely, even when down payments run lower than the conventional 20% benchmark. That omission trims monthly carrying costs meaningfully on seven-figure properties, where PMI would otherwise add a substantial recurring expense.
Before shopping for a high-value property, buyers should confirm standing on each qualification pillar:
- Credit score: higher tiers unlock better pricing and fewer conditions
- Income documentation: lenders verify stability, not just total earnings
- Cash reserves: months of liquid assets reassure underwriters on larger loan balances
This jumbo loan guide approach to underwriting rewards preparation. Buyers who organize financials early move through approval faster and with fewer surprises.
What Alternative Financing Strategies Exist?
Piggyback loans and asset-based lending give buyers of high-value properties paths beyond a single jumbo mortgage. Both structures suit purchasers whose income or asset profile does not fit a conventional underwriting box. A sound jumbo loan guide treats these options as complements to, not substitutes for, standard jumbo financing.
Piggyback structures split a purchase into two loans, often a first mortgage paired with a second lien, which lowers the size of the primary jumbo balance. Asset-based lending shifts the qualification focus from tax-return income to verifiable assets, a useful route for buyers whose wealth sits in investments rather than paychecks. Both approaches add flexibility for unique financial situations instead of forcing a buyer into one rigid loan product.
- Piggyback loans: combine two mortgages to reduce the jumbo balance on the primary note
- Asset-based lending: qualifies borrowers using verified assets instead of reported income
- DSCR loans: weigh a property’s rental income against its debt obligations
- Hard money loans: deliver short-term, asset-secured capital for time-sensitive purchases
Are DSCR and hard money loans useful for luxury property investors?
Yes. Investors buying high-value properties for rental income often qualify more easily under debt-service coverage ratio underwriting than under traditional income documentation. Hard money loans fill short-term gaps, giving investors capital to close quickly on competitive, high-price listings. These investor-focused products sit alongside standard jumbo mortgage info as part of a broader financing toolkit for expensive markets.
Strong credit, income, and reserves remain the baseline for qualifying. The payoff, though, includes competitive rates and tax advantages that buyers priced out of conventional high-value home loans rarely see elsewhere. Expensive real estate markets. Prices routinely exceed conforming loan limits, reward buyers who line up the right alternative structure before making an offer.
How Should You Choose a Jumbo Lender?
Selecting a jumbo lender comes down to transparency, speed, and a loan structure built around the buyer’s actual financial picture. High-value property purchases involve larger sums and more documentation, so a lender’s process matters as much as its rate sheet. Munshi Capital Inc. structures its jumbo-mortgage-info-007 services around a borrower-first philosophy, guiding high-net-worth buyers through each step without hidden surprises or last-minute conditions.
Technology plays a role, but it does not replace human judgment. Pre-approvals move quickly when modern systems pair with experienced loan specialists who track a file from application to closing. That combination gives buyers full visibility into loan status at every stage, a detail that matters when competing for a high-value listing in a tight market.
What Should a High-Value Buyer Look For in a Jumbo Lender?
Look for a lender offering genuine flexibility across loan types, not a one-size-fits-all product. A strong jumbo-loan-guide-007 resource should explain program options clearly, without burying terms in fine print. Dependable service and consistent communication matter more than marketing promises once underwriting begins.
Buyers evaluating lenders should weigh:
- Clarity: Clear answers about documentation, timelines, and program fit
- Breadth of programs: Residential and commercial options covering diverse financial profiles
- Responsiveness: Loan status visible throughout underwriting, not just at closing
- Personalized guidance: Support tailored to the borrower’s goals, not a generic script
Why Does Loan Program Variety Matter for Luxury Buyers?
Affluent buyers often have complex income, multiple properties, or investment holdings that do not fit standard underwriting boxes. A lender offering comprehensive high-value-home-loans-007 programs can structure financing around that complexity rather than forcing a rigid template. That range of residential and commercial options gives serious buyers room to negotiate terms that match their actual financial reality.
FAQ
What qualifies as a jumbo loan for high-value properties?
A jumbo loan is any mortgage exceeding the conforming limits of pricing varies or $1,249,125 in high-cost markets, set by Fannie Mae and Freddie Mac. Munshi Capital Inc. structures jumbo financing for luxury homes above these thresholds nationwide.
How do jumbo loans differ from conforming loans?
Conforming loans stay within Fannie Mae and Freddie Mac limits and follow standardized underwriting rules. Jumbo loans exceed those limits and require stricter qualification. Jumbo financing demands stronger credit profiles and deeper financial reserves in exchange for funding higher-priced properties.
What loan term structures does Munshi Capital Inc. offer for jumbo financing?
Munshi Capital Inc. offers fixed-rate, adjustable-rate, and interest-only jumbo loan terms for high-value properties. Fixed-rate options suit buyers wanting predictable payments on a long-term primary
Conclusion
In closing, securing financing for high-value properties demands a lender who understands the complexity of your financial situation and delivers transparent guidance without compromise. Munshi Capital Inc. provides the specialized expertise and comprehensive loan solutions necessary to navigate jumbo financing with confidence, backed by a commitment to clarity and dependable service throughout your entire lending journey. Our team remains dedicated to ensuring you access the right financing structure tailored to your unique objectives, enabling you to move forward with certainty and integrity at every stage.
Leave a Reply