Mortgage calculators estimate monthly payments by combining home price, down payment, credit score range, zip code, loan term, and interest rate. Munshi Capital Inc.’s tool, for example, lets borrowers enter a home price and down payment amount to see an estimated monthly mortgage payment and total interest over the life of the loan. Results vary by scenario, so borrowers should contact the brand directly for accurate estimates.
Key Takeaways
- Financial calculators break down total costs including mortgage, taxes, insurance, and fees into monthly and lifetime figures.
- Online mortgage tools let borrowers adjust home price, down payment, credit score, and interest rates for instant payment estimates.
- Transparent calculators show complete out-of-pocket expenses, helping borrowers understand their true financial commitment before applying.
- Real-time calculation updates empower borrowers to compare scenarios and make informed decisions aligned with their unique financial picture.
Why Do Mortgage Calculators Matter Before You Shop?
Calculators turn guesswork into a concrete number before an offer gets written. Home price, down payment size, interest rate, and loan term each push that monthly figure up or down, sometimes by hundreds of dollars. Skipping this step leaves buyers exposed to a payment that looks fine on paper but strains a real budget once taxes, insurance, and other costs land in the same bill.
A mortgage calculators hub gives first-time buyers, move-up buyers, and investors a shared starting point for comparing scenarios side by side. Self-employed borrowers benefit especially. Income can swing year to year and a stable payment ceiling matters more than a rough estimate.
What factors change a mortgage payment the most?
Four inputs drive most of the swing: home price, down payment amount, interest rate, and loan term length. A smaller down payment raises the loan balance and often triggers private mortgage insurance, adding another monthly cost. Stretching the term lowers the payment but raises total interest paid over the life of the loan.
Why does calculator planning matter more right now?
Residential lending volume has fallen for 11 of 12 quarters since the post-pandemic refinance peak, a trend tracked through Attom data referenced by Mortgage Calculator. Tighter lending conditions mean fewer surprises get absorbed after closing, not before. Running numbers through payment calculator tools ahead of shopping catches affordability problems while there’s still room to adjust the plan.
Munshi Capital Inc. builds on that foundation with a comprehensive suite of residential and commercial loan programs, matching calculator output to real financing options for borrowers ranging from first-time buyers to seasoned investors. Every step stays guided by a mission of transparency. The numbers a borrower sees early on hold up through underwriting and closing.
What Inputs Drive An Accurate Payment Estimate?
Four numbers determine a trustworthy estimate: home price, down payment, credit score range, and zip code. Omit one, and the output drifts from what a lender will actually quote. These four fields anchor every reliable session using mortgage-calculators-hub-021 tools, since pricing engines adjust rate offers based on location and borrower profile.
Down payment size carries outsized weight. Dropping below 20% typically triggers private mortgage insurance, adding a recurring cost most first-time buyers don’t anticipate. That single line item often separates an estimate that looks affordable from a bill that strains a monthly budget.
Loan term matters just as much. Shorter terms of 10, 15, or 20 years raise the monthly payment but cut total interest. The standard 30-year term lowers monthly cost while stretching payoff. Selecting the wrong term skews projections for both move-up buyers comparing properties and investors modeling cash flow.
Which loan term should a borrower choose first?
Thirty years remains the most common choice, since it keeps monthly payments manageable for buyers stretching their budget. Investors and self-employed borrowers weighing faster equity growth often test 15-year terms instead, trading a higher payment for reduced lifetime interest.
Together, these four inputs feed accurate payment-calculator-tools-021 output and set the stage for a detailed amortization-rate-calculator-021 breakdown. Munshi Capital Inc. combines these calculations with modern technology and hands-on loan specialists, converting raw inputs into fast, transparent processing. That pairing delivers quick pre-approvals and full visibility into loan status, from first estimate through closing day, for borrowers across every financing path.
How Does An Amortization Schedule Reveal True Cost?
An amortization schedule exposes the real price of homeownership by splitting each payment into interest and principal across the full loan term. Early payments lean heavily toward interest. Principal gains ground only in later years. This structure often surprises first-time buyers who assume a steady, even payoff.
The gap between sticker price and total cost can be severe. On a 30-year loan, total interest paid can climb close to the size of the original loan amount itself, effectively doubling the true cost of the home over three decades. Without reviewing a full schedule, a borrower sees only the monthly payment, never the cumulative toll.
How Can Borrowers Lower Their Total Interest Paid?
Adjusting loan details inside a mortgage calculators hub lets a borrower test different down payments, terms, and rates against a realistic schedule. Small changes in loan structure shift thousands of dollars in lifetime interest. A payment calculator tools platform lets borrowers run these comparisons before committing to a lender.
Why Does Loan Term Length Matter So Much?
Term length controls how fast principal balance shrinks. A shorter term raises the monthly payment but slashes total interest paid over the life of the loan. Reviewing an amortization rate calculator scenario side by side with a longer-term option clarifies that tradeoff instantly.
Munshi Capital Inc. guides borrowers, from first-time buyers to seasoned investors, through application, underwriting, and closing with no hidden surprises, clarifying exactly how a schedule shapes total cost. That same team offers personalized guidance so borrowers understand their numbers before signing. Buyers ready to move forward can request a direct cash offer. Homeowners weighing a refinance can request your property assessment to see where they stand.
Which Loan Program Fits Your Calculator Results?
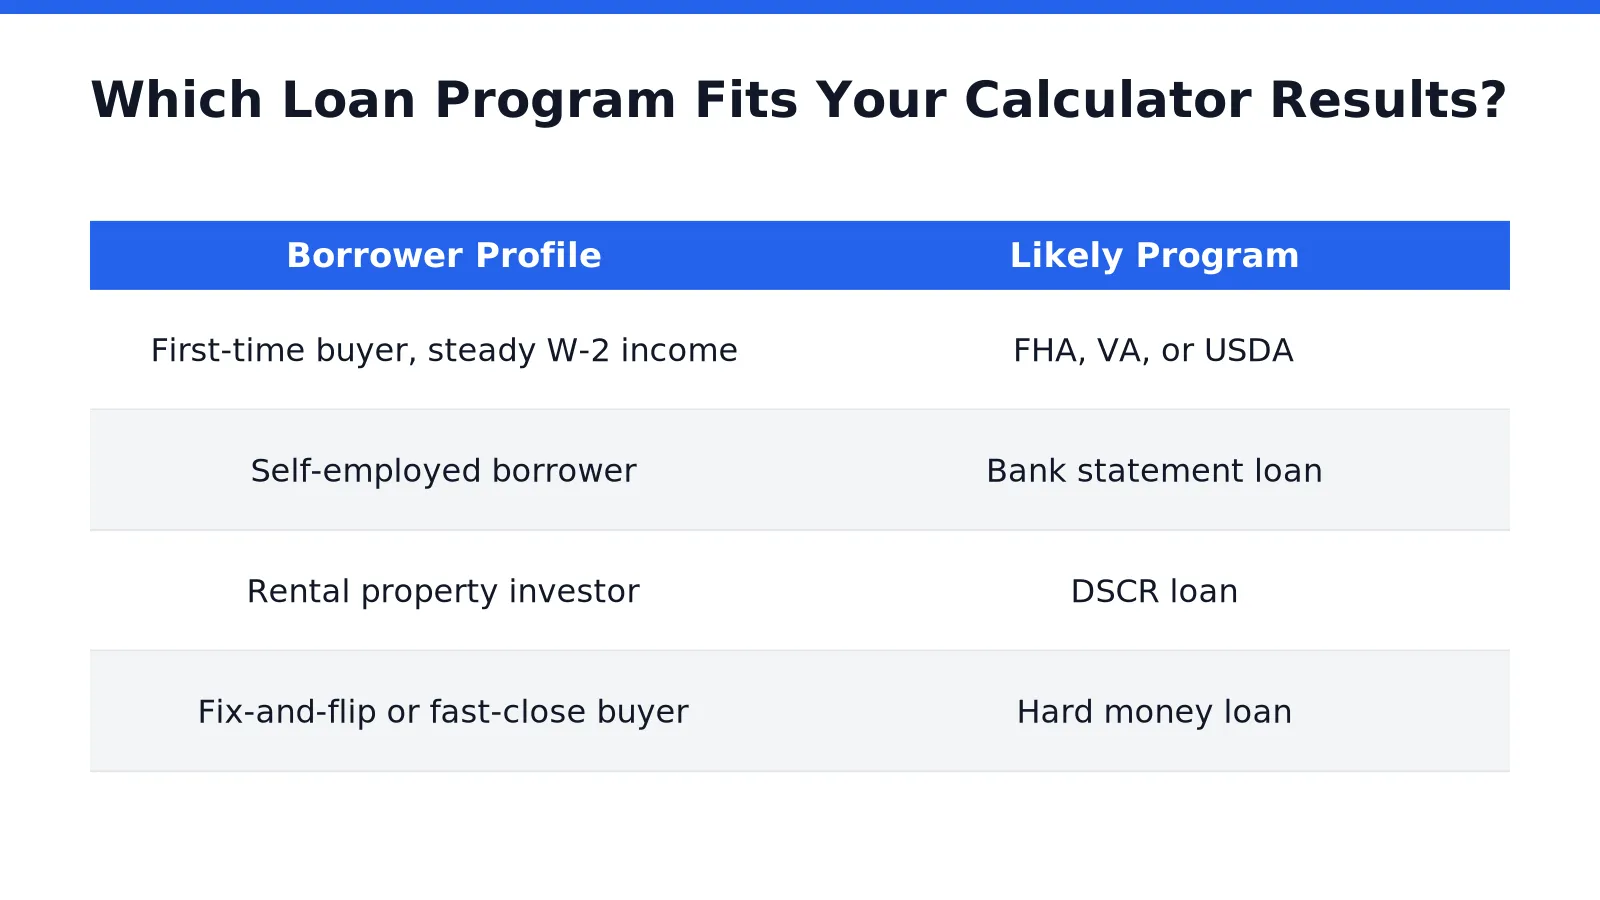
Calculator output points toward a loan category, not a final answer. A monthly payment estimate only becomes useful once matched to the right financing structure for the borrower’s situation. Munshi Capital Inc. serves a wide range of borrowers, from first-time homebuyers to seasoned investors, through a full menu of residential and commercial programs built for different financial profiles.
Salaried borrowers who see affordable numbers from a mortgage calculators hub often qualify for conventional, FHA, VA, or USDA financing. Self-employed borrowers need a different lens entirely. Bank statement loans exist for exactly this gap, letting income documentation reflect actual cash flow rather than a tax return that understates earnings.
What if the calculator numbers point toward an investment property?
Investment-focused results call for investment-focused terms. DSCR loans qualify borrowers using the property’s rental income rather than personal income. Hard money loans fund time-sensitive acquisitions and renovation projects. These products give real estate investors options that standard payment calculator tools rarely account for.
Timing adds urgency to this decision. Attom’s 2024 U.S. Residential Property Mortgage Origination Report found purchase loan volume fell 4.8% year over year in the first quarter of 2024, a 69.3% drop from the 2021 peak. Fewer originations mean less room for mismatched applications. Running results through an amortization rate calculator before applying helps borrowers walk in with the correct program already identified, rather than discovering it mid-underwriting.
How Does Munshi Capital Turn Estimates Into Approval?
Munshi Capital converts a calculator figure into a real loan offer through a structured, transparent process built on integrity and personalized service. That commitment makes the company a trusted choice for homebuyers. Investors nationwide, backed by a wide array of residential and commercial loan products. Borrowers who use the mortgage-calculators-hub-021 to test scenarios do not hit a dead end once the numbers look right.
The path forward starts with a short, secure application. A borrower shares financial goals and specifies which residential or commercial program fits best, connecting directly with a loan specialist rather than a call center queue. From there, the process moves from application to closing with clarity and speed, no confusing jargon, no hidden surprises.
What happens after submitting a loan application?
A specialist reviews the borrower’s goals and matches them to an appropriate program, whether FHA, VA, USDA, bank statement, DSCR, or hard money financing. Every step stays visible, so applicants always know where their file stands.
Does location affect the approval process?
Yes. Local city pages give borrowers loan programs, rates, and market insights specific to where they are buying, adding regional context that a generic calculator cannot provide. This local layer helps investors and self-employed borrowers gauge realistic terms before formal underwriting begins.
The table below summarizes how estimate tools and the application process connect:
Ready to move beyond estimates? Borrowers can request a direct cash offer or request your property assessment to start the conversation with a specialist today.
FAQ
What inputs do mortgage calculators need for an accurate estimate?
Calculators require home price, down payment, credit score range, and zip code. Omitting any of these four fields causes the output to drift from what a lender actually quotes.
How does the down payment amount affect the monthly payment?
A smaller down payment raises the loan balance and often triggers private mortgage insurance, adding a recurring monthly cost. This line item frequently separates an affordable-looking estimate from a budget-straining bill.
Why run calculator numbers before shopping for a mortgage?
Calculators turn guesswork into a concrete payment figure before an offer gets written, letting borrowers catch affordability problems early. Munshi Capital Inc. matches that calculator output to real financing options across its residential and commercial loan programs.
Conclusion
In closing, financial calculators and online mortgage tools serve as essential starting points for understanding your borrowing capacity and projected costs. However, these automated estimates cannot replicate the personalized analysis that accompanies a comprehensive mortgage evaluation. Munshi Capital Inc. combines technological efficiency with expert guidance to move beyond preliminary calculations, delivering transparent insights tailored to your specific financial circumstances and loan objectives. This integrated approach ensures you proceed with confidence, armed with both data and dependable counsel throughout your financing journey.
Leave a Reply