First-time homebuyers in Walnut Creek, CA find support through the City of Walnut Creek’s Housing Programs, which offer below-market-rate home listings, first-time buyer loans, and HUD-approved housing counseling agencies providing free or low-cost homebuyer education. Munshi Capital Inc. complements these resources with FHA, VA, USDA, and bank statement loan programs designed for various financial situations.
Key Takeaways
- Walnut Creek offers Below Market Rate (BMR) homes with 2026 income limits designed for qualified first-time homebuyers.
- HUD-approved housing counseling agencies throughout the Bay Area provide free guidance on homebuying programs and financial preparation.
- First-time homebuyer programs in nearby Concord deliver down payment assistance and specialized financing for qualified borrowers.
- Local housing programs provide down payment loans and home improvement grants to support your purchase journey.
What Do You Need Before Starting Your Search?
Three things matter most before touring a single property in Walnut Creek: a clear financing starting point, organized documentation, and proof of completed homebuyer education where required. Skipping any of these steps delays closing and weakens an offer in a competitive Contra Costa County market. Preparation turns a hopeful search into a focused one.
Munshi Capital Inc. serves as a first-time-buyer-hub-027 for Walnut Creek residents, offering mortgage financing built for borrowers ranging from first-time buyers to seasoned investors. This range matters because needs differ widely, from a young professional buying a first condo to a family upsizing near downtown. A comprehensive homebuyer-programs-guide-027 approach means buyers find a financing path suited to their specific income, credit profile, and property type, rather than a one-size-fits-all loan product.
What’s the First Practical Step Toward Financing?
Buyers start with a quick, secure application. From there, a loan specialist discusses goals and identifies which residential program fits the buyer’s situation before documents get gathered for pre-approval.
Is Homebuyer Education Required Before Applying for Assistance?
Many Walnut Creek down payment assistance programs require completion of a HUD-approved homebuyer education course first. This step, often overlooked, satisfies a core eligibility requirement for local first-time homebuyer assistance programs.
Before contacting a lender, buyers should gather:
- Recent pay stubs and two years of tax returns
- Bank statements covering the last several months
- Proof of completed HUD-approved homebuyer education, if applying for local assistance
- A list of current debts and monthly obligations
These first-home-loan-resources-027 materials streamline underwriting and prevent last-minute scrambling once an offer gets accepted on a Walnut Creek property.
How Do You Complete Required Homebuyer Education?
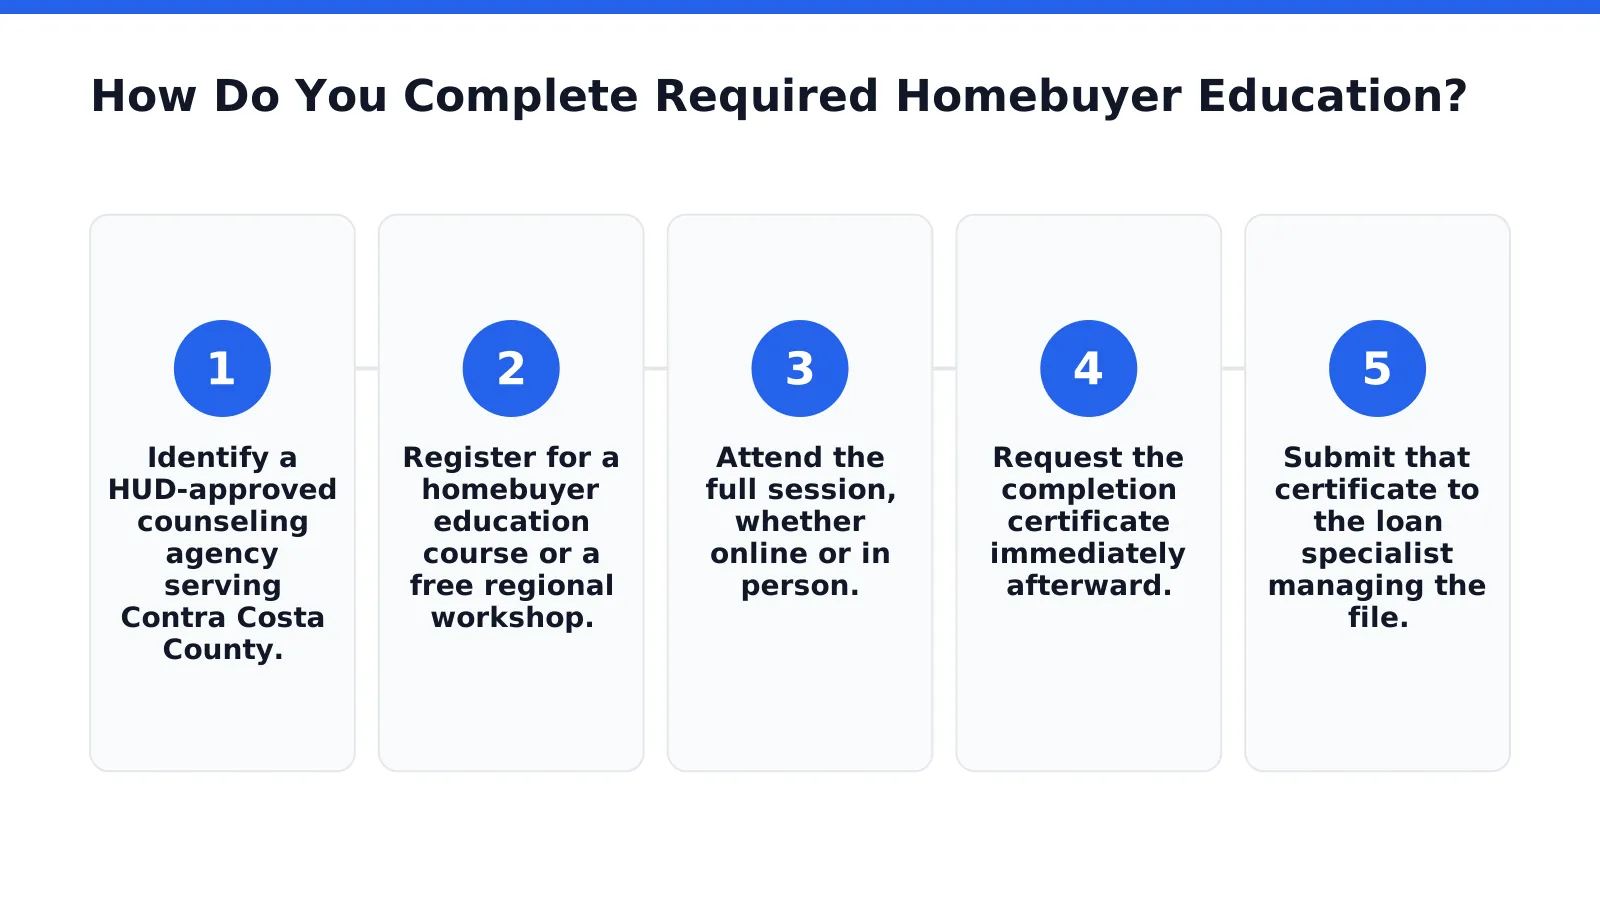
Completion requires three sequential steps: enrolling with a HUD-approved counseling agency, finishing the coursework or workshop, and obtaining a certificate before closing. Walnut Creek buyers skip this step at their own cost. Many down payment assistance programs will not fund a loan without proof of completed education. The process stays accessible, though. HUD-approved housing counseling agencies serving the Bay Area, including Walnut Creek residents, provide homebuyer education programs at free or low cost, alongside pre-purchase counseling, post-purchase counseling, predatory lending education, and credit counseling.
Follow these steps in order:
- Identify a HUD-approved counseling agency serving Contra Costa County.
- Register for a homebuyer education course or a free regional workshop.
- Attend the full session, whether online or in person.
- Request the completion certificate immediately afterward.
- Submit that certificate to the loan specialist managing the file.
Where Can Walnut Creek Buyers Find Free Workshops?
Regional nonprofits host free workshops and seminars throughout the Bay Area to prepare residents for homeownership. These sessions cover budgeting, credit readiness, and the mortgage timeline, giving Walnut Creek buyers a no-cost entry point into the first-time-buyer-hub-027 of local resources. Signing up for alerts ensures a seat opens before application deadlines close.
What Happens After the Certificate Is Issued?
Loan readiness begins the moment education wraps up. A completed certificate pairs naturally with the homebuyer-programs-guide-027, connecting coursework to actual financing options. Personalized guidance from a loan specialist then translates certificate-stage preparation into a tailored path, drawing on the first-home-loan-resources-027 available to Walnut Creek buyers. Goals and loan products align before any offer gets written.
Where Can You Secure Down Payment Assistance Funds?
Down payment assistance in Walnut Creek flows primarily through municipal housing programs built for lower-income residents. The City of Walnut Creek helps qualifying residents locate housing options to rent or buy, with direct support for first-home purchases. Losing sight of this resource costs buyers thousands in avoidable financing fees. Below market rate housing opens a second path forward: Walnut Creek residents can pursue BMR homes, which carry sale prices set below typical market value specifically to widen access to ownership.
Combining local assistance with the right loan product determines whether a down payment gap closes or widens. Munshi Capital Inc. structures financing through FHA, VA, USDA, and bank statement loan programs, pairing each with local down payment support to match a buyer’s actual financial picture. This first-time-buyer-hub-027 approach to financing means a buyer’s credit profile, income documentation, and savings timeline all factor into the loan match, rather than forcing one standard product on every applicant.
What Steps Should a First-Time Buyer Take to Access These Funds?
- Contact the City of Walnut Creek’s housing programs office to confirm income eligibility for assistance.
- Review available below market rate listings before committing to a standard market-rate search.
- Consult a homebuyer-programs-guide-027 resource to compare FHA, VA, USDA, and bank statement loan terms.
- Submit financing documentation early, since assistance funds and loan approvals often run on parallel timelines.
Is Down Payment Assistance Enough on Its Own?
Rarely. Assistance funds reduce the upfront cash barrier, but a buyer still needs a qualifying mortgage behind it. Pairing municipal support with structured first-home-loan-resources-027 financing closes the remaining gap. Buyers ready to move forward can request your property assessment or request a direct cash offer to clarify next steps.
How Do You Select the Right Mortgage Program?
Selecting a mortgage program starts with matching income documentation to loan structure, not with chasing the lowest advertised rate. Walnut Creek first-time buyers face a distinct challenge: competitive home prices in Contra Costa County demand financing that fits an individual financial picture rather than a one-size-fits-all product. A mismatch here costs buyers weeks of delay, denied applications, or loan terms that strain a household budget for years.
Before comparing programs, gather the following prerequisites: two years of tax returns or bank statements, a credit report, proof of employment, and a target purchase price range for Walnut Creek properties. With documentation ready, follow these steps:
- Identify income type. Salaried borrowers typically qualify for FHA or VA programs, while self-employed buyers often need bank statement loans.
- Confirm property eligibility. Some Walnut Creek neighborhoods and surrounding Contra Costa County areas qualify for USDA financing; most urban parts of the city will not.
- Compare program structures using a side-by-side review of qualification criteria and documentation burden.
- Submit documentation through a streamlined application process built for clarity at every stage.
- Review underwriting feedback promptly to avoid closing delays.
Borrowers move through a straightforward application, underwriting, and closing process designed to prioritize ease and understanding, without hidden surprises. Clarity and honest communication guide every step for Walnut Creek first-time buyers navigating this first-time buyer hub of options.
What Loan Programs Suit a First-Time Buyer?
FHA, VA, and USDA loans each serve different borrower profiles. A proper homebuyer programs guide sorts them by income verification type and property location. Bank statement loans serve self-employed applicants who lack traditional pay stubs.
How Fast Can Pre-Approval Happen?
Fast, transparent processes rely on modern technology paired with hands-on loan specialists, producing quicker pre-approvals. Buyers gain full visibility into loan status by consulting dependable first home loan resources throughout underwriting and closing.
What Common Mistakes Should First-Time Buyers Avoid?
Unclear loan terms trip up more Walnut Creek buyers than bad interest rates do. Confusion about fees, timelines, and eligibility creates costly delays, and some buyers walk away from deals entirely. Avoiding these errors starts with understanding where first-time buyers typically go wrong.
Mistake 1: Working with a lender that leaves loan steps unexplained. A murky process breeds missed deadlines and surprise costs at closing. Partnering with a lender committed to integrity and personalized service helps buyers sidestep the pitfalls of an unclear loan process before they derail a purchase.
Mistake 2: Choosing financing that isn’t structured for the borrower’s actual situation. Loan programs built around the individual, with clear answers at every step, cut down on the confusion common among first-time buyers. Generic financing packages often create more questions than they answer.
Mistake 3: Skipping vetted nonprofit resources. Organizations such as BAAHA exist specifically to support, preserve, and expand affordable homeownership across Bay Area communities, including below-market-rate program guidance local buyers need. Bypassing these resources leaves buyers without critical information on BMR eligibility and application timing.
Is It Worth Using a First-Time Buyer Guide Before Applying?
Yes. A thorough first-time-buyer-hub-027 consolidates financing steps, reducing the odds of overlooked requirements. Buyers who review a homebuyer-programs-guide-027 before applying typically enter underwriting with fewer surprises.
Buyers ready to move forward should consult first-home-loan-resources-027 early, request a direct cash offer when evaluating a current property, and request your property assessment before finalizing a purchase timeline.
FAQ
What resources help first-time homebuyers in Walnut Creek?
The City of Walnut Creek’s Housing Programs offer below-market-rate homes, first-time buyer loans, and HUD-approved counseling, while Munshi Capital Inc. provides FHA, VA, USDA, and bank statement loan programs designed for various financial situations.
Is homebuyer education required before applying for down payment assistance?
Many Walnut Creek down payment assistance programs require completion of a HUD-approved homebuyer education course, with a certificate obtained before closing, to satisfy a core eligibility requirement.
What documents should buyers gather before applying for financing?
Buyers should collect recent pay stubs, two years of tax returns, several months of bank statements, proof of completed homebuyer education, and a list of current debts and monthly obligations.
Conclusion
In closing, first-time homebuyers in Walnut Creek benefit from a comprehensive landscape of resources and financing options designed to address their unique circumstances. By leveraging available programs, from government-backed loans to specialized financing solutions, and partnering with lenders committed to transparent, personalized guidance, prospective homeowners position themselves to navigate the purchase process with clarity and confidence. The path to homeownership requires informed decision-making and dependable support; securing both ensures a foundation built on understanding rather than uncertainty.
Leave a Reply