FHA loan requirements for first-time buyers in Walnut Creek include a minimum 3.5% down payment, government backing through the Federal Housing Administration, and flexible credit qualification standards. Munshi Capital Inc. guides first-time buyers, investors, and fund managers through eligibility criteria, documentation, and lender-specific requirements, helping clients navigate California’s competitive housing market with clarity and confidence.
What Are FHA Loan Requirements for First-Time Buyers?
FHA Loan Requirements for First-Time Buyers center on a government-insured mortgage structure designed to lower the barriers standing between renters and homeownership. The Federal Housing Administration, a division of the U.S. Department of Housing and Urban Development, insures these loans rather than issuing them directly. That insurance shifts risk away from private lenders, which is why FHA financing accepts lower credit scores and thinner savings accounts than many conventional loan products require.
For a first-time buyer eyeing a home in Walnut Creek, the structure works in practical terms as follows:
- Down payment minimum: as low as 3.5% of the purchase price, a fraction of what conventional loans typically demand.
- Lender insurance: the federal backing protects the lender, not the borrower, but it opens approval to applicants who might otherwise be denied.
- Property scope: FHA financing applies to primary residences, making it relevant for buyers planning to live in the Walnut Creek home they purchase.
Does an FHA loan cost more than a conventional loan?
Cost comparisons depend on individual credit profiles and loan terms, not a fixed rule. The insurance backing does add a layer of protection lenders factor into their offers. Buyers in Walnut Creek weighing FHA against conventional financing typically compare the reduced down payment against long-term loan costs before deciding.
Who benefits most from FHA financing?
First-time buyers with limited savings or a shorter credit history stand to gain the most. The California FHA Loan Eligibility Criteria were built specifically to widen access for exactly this group.
What Credit Score and Income Qualify Walnut Creek Buyers?
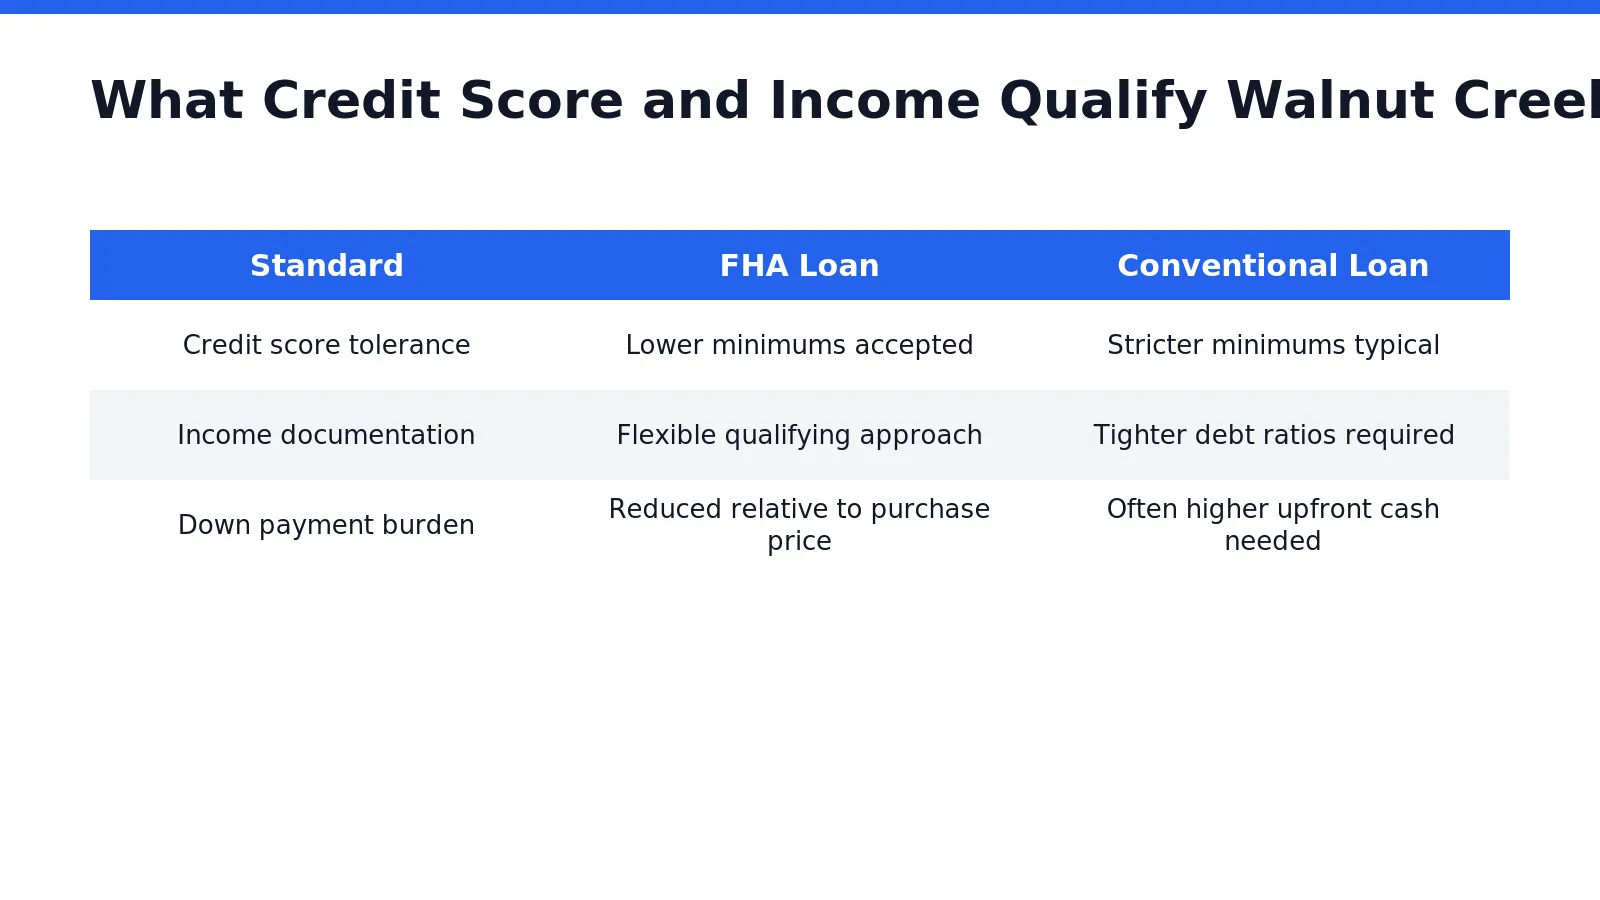
Federal Housing Administration guidelines set credit score and income thresholds well below what many conventional mortgage products demand. This structure matters most in Walnut Creek, where saving a substantial down payment ranks among the toughest obstacles buyers face in one of the nation’s most expensive housing markets. Credit history and income documentation carry weight, but they rarely close the door the way a large cash requirement does.
The broader California FHA Loan Eligibility Criteria rest on flexible standards rather than rigid cutoffs. Underwriters weigh the full financial picture, not a single number in isolation.
What credit score does an FHA loan require?
FHA Loan Credit Score Requirements sit below conventional benchmarks, giving buyers with thinner or imperfect credit files a workable path. Lenders review score history alongside income stability rather than rejecting applicants outright for a single low mark.
Does income level affect FHA eligibility?
Income matters, but FHA underwriting allows more flexibility than conventional guidelines. This forms a core piece of the FHA Loan Requirements for First-Time Buyers. Qualification depends on documented, stable earnings rather than a high fixed threshold. Munshi Capital Inc. applies proprietary insights to help Walnut Creek applicants organize eligibility documentation with transparency and efficiency.
How Does the FHA Loan Process Work in Walnut Creek?
FHA loans have supported American homeownership since 1934, giving the program a longer operating history than most conventional loan products on the market today. For Walnut Creek buyers weighing FHA Loan Requirements for First-Time Buyers against other financing paths, that history translates into a well-established, predictable sequence of steps rather than an untested process.
A structured process typically moves through these stages:
- Application submission: Borrowers complete a secure application and connect with a loan specialist who reviews program fit for the specific Walnut Creek purchase.
- Eligibility review: The specialist evaluates income, credit profile, and property type against California FHA Loan Eligibility Criteria.
- Underwriting and documentation: Financial records are verified and matched to FHA Loan Credit Score Requirements.
- Closing coordination: Steps are scheduled with defined timelines to reduce delay and confusion.
What Makes This Process Different From a Conventional Loan?
Government backing shapes each stage differently than conventional underwriting does. A customer-centric approach values borrower time throughout, replacing jargon with clear, practical guidance at each milestone.
Who Guides Walnut Creek Buyers Through the Steps?
A dedicated loan specialist walks buyers from initial application through closing, explaining requirements plainly. This structure keeps Walnut Creek borrowers informed without hidden surprises along the way.
Conclusion
In closing, navigating FHA loan requirements as a first-time buyer in Walnut Creek demands a methodical approach grounded in accurate financial assessment and documentation. Understanding credit standards, debt-to-income ratios, down payment expectations, and property appraisal criteria positions you to move forward with confidence. The path to homeownership through FHA financing remains accessible when you engage with knowledgeable guidance that prioritizes transparency. Addresses your specific circumstances with tailored solutions designed for your success.
Leave a Reply