First-time homebuyers in Walnut Creek, CA follow five steps: assess savings and credit score, get pre-approved, explore first-time buyer loan programs like FHA and CalHFA down payment assistance, search listings with a local agent, then submit offers and close escrow. Munshi Capital Inc. guides each financing step with transparent, data-driven pre-approval support.
Key Takeaways
- Evaluate your financial readiness by reviewing savings, credit score, income, and long-term homeownership goals before starting.
- Walnut Creek, California offers diverse mortgage programs including FHA, VA, USDA, and bank statement loans for first-time buyers.
- Pre-approval takes days, not weeks, with transparent underwriting that shows your exact loan status from application through closing.
- Down payment assistance and junior loan options help cover initial costs, making homeownership accessible for moderate-income borrowers.
What Should You Prepare Before Buying In Walnut Creek?
Preparation determines whether a Walnut Creek purchase closes smoothly or stalls under avoidable delays. Four factors shape readiness: savings, credit score, income, and long-term plans. Reviewing each one before touring properties gives buyers a realistic picture of what they can afford. How fast they can move once an offer is accepted.
Who qualifies as a first-time homebuyer?
A first-time homebuyer is defined as someone who has not owned a home in the past three years. This status carries real weight in the Walnut Creek market. It can unlock loan programs and assistance options unavailable to repeat buyers. Confirming eligibility early clarifies which financing paths are worth pursuing.
What should buyers check before house-hunting?
Buyers should complete a readiness review before scheduling showings in Walnut Creek neighborhoods. The following homebuying steps form a practical starting checklist:
- Pull a current credit score and address any errors or outstanding balances.
- Calculate total savings available for a down payment and closing costs.
- Document steady income sources to understand borrowing capacity.
- Clarify long-term plans, including how long the buyer intends to stay in the home.
Once these items are in order, the mortgage process moves faster and with fewer surprises. Munshi Capital Inc. dedicates its loan specialists to understanding each client’s goals before recommending a program, whether the buyer qualifies for first-time assistance or needs a conventional path. The company’s mission centers on transparency, keeping communication clear from application through closing. Walnut Creek buyers ready to move forward can request a direct cash offer or request your property assessment as a next step toward securing financing with confidence.
How Do You Determine Your Walnut Creek Budget?
A realistic Walnut Creek home budget starts with full financial qualification, not simply the number a lender approves. Approval amounts reflect debt ratios and credit history, but a sound budget accounts for every dollar flowing out each month. Buyers moving through the homebuying steps often mistake a loan ceiling for a spending plan, a costly error in a competitive East Bay market.
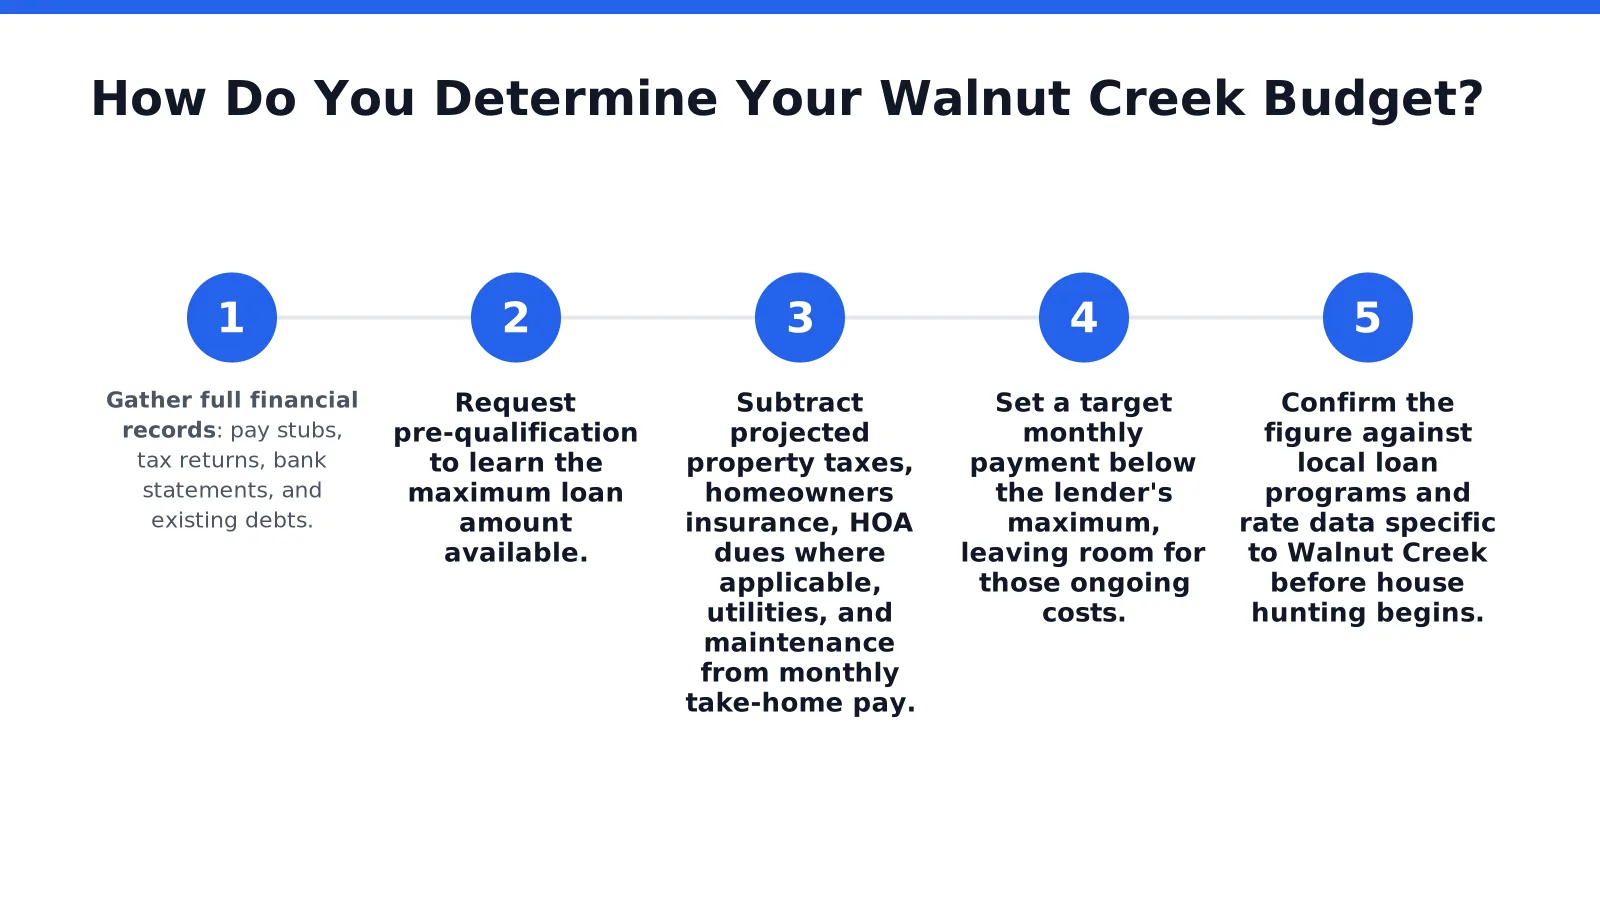
Setting that budget requires a clear sequence:
- Gather full financial records: pay stubs, tax returns, bank statements, and existing debts.
- Request pre-qualification to learn the maximum loan amount available.
- Subtract projected property taxes, homeowners insurance, HOA dues where applicable, utilities, and maintenance from monthly take-home pay.
- Set a target monthly payment below the lender’s maximum, leaving room for those ongoing costs.
- Confirm the figure against local loan programs and rate data specific to Walnut Creek before house hunting begins.
What costs beyond the mortgage payment should Walnut Creek buyers budget for?
Walnut Creek homeowners pay property taxes, homeowners insurance, and utilities every month regardless of loan terms. Condo and planned-community buyers add HOA fees to that list. Maintenance reserves matter too, since older East Bay properties often need repairs sooner than buyers expect.
Munshi Capital Inc. structures the mortgage process around each borrower’s complete financial picture rather than a single approval number. The company’s residential programs, including FHA, VA, USDA, and bank statement loans, serve first-time homebuyer households and seasoned investors across Walnut Creek alike. Local loan programs, rate information, and market insights tailored to Walnut Creek give buyers a realistic starting point before touring a single property. Borrowers who search their city first enter negotiations with a defensible number, not a guess.
Which Mortgage Programs Fit Walnut Creek Buyers?
Walnut Creek buyers qualify for mortgage programs built for a wide range of financial profiles, from salaried professionals to self-employed business owners. Munshi Capital Inc. structures its mortgage process around that diversity, serving first-time homebuyer clients and seasoned investors alike throughout the Walnut Creek market.
Loan selection depends on income documentation, down payment savings, and long-term goals. A young family with steady W-2 income has different needs than a contractor reporting business deposits instead of pay stubs. Matching the right program to the right borrower profile is one of the earliest homebuying steps a Walnut Creek household should take.
Residential loan programs through Munshi Capital Inc. include FHA, VA, USDA, and bank statement options, giving Walnut Creek households multiple paths toward approval rather than a single rigid standard.
Are there state assistance programs for first-time buyers in Walnut Creek?
California offers state-level support alongside private lending. The California Housing Finance Agency, known as CalHFA, provides first and junior loan options for low- to moderate-income families. These include down payment assistance loans carrying interest rates as low as zero percent, which can ease the upfront cost burden for qualifying Walnut Creek buyers.
Does financing extend beyond first-time buyers?
Yes. Munshi Capital Inc. extends its program range from first-time homebuyers to seasoned investors and business owners nationwide, including those purchasing in Walnut Creek. That range means a growing family. An established investor can both find a structured, transparent path through underwriting without switching lenders mid-process.
What Are The Core Homebuying Steps To Closing?
Closing on a home in Walnut Creek, California follows a defined sequence: application, underwriting, approval, and final signing. Each stage builds on the last, moving buyers from paperwork to keys in hand. For a first-time homebuyer, understanding this sequence removes much of the anxiety that comes with a major purchase.
The mortgage process feels complex at first glance, with multiple forms, verifications, and deadlines overlapping. Broken into clear, sequential homebuying steps, it becomes far more manageable for Walnut Creek buyers navigating a competitive East Bay market. A lending team that guides borrowers through every stage with clarity and speed, free of confusing jargon. Last-minute surprises, makes the difference between a stressful closing and a confident one.
What happens between application and closing?
Borrowers move through a straightforward application, underwriting, and closing sequence built to prioritize ease and understanding. No hidden surprises interrupt the process once documentation is submitted.
- Submit income, asset, and credit documentation to begin the application.
- Receive a quick pre-approval, backed by modern technology paired with hands-on loan specialist support.
- Enter underwriting, where the file is reviewed against program requirements.
- Track loan status with full visibility from start to finish.
- Sign final documents at closing and receive keys to the Walnut Creek property.
Homeowners exploring a sale alongside a purchase, whether relocating within Walnut Creek or upgrading from a starter condo, can request a direct cash offer on an existing property to simplify timing between transactions. Those still weighing their current home’s worth before listing can request your property assessment to clarify equity available for a down payment.
What Mistakes Should First-Time Buyers Avoid?
Overlooking special loan programs ranks among the costliest errors a first-time homebuyer in Walnut Creek makes. Buyers who skip this research often pay more upfront, miss down payment assistance, or qualify for less favorable terms than necessary. Avoiding a short list of recurring missteps protects both savings and sanity throughout the homebuying steps ahead.
Which loan programs do buyers in Walnut Creek often overlook?
State-backed options exist specifically to ease the path into homeownership, yet many buyers never investigate them. California’s own housing finance programs, for example, require working through an approved lender rather than applying directly to the agency. Skipping this step can mean missing low-interest down payment assistance entirely.
What other missteps slow down the mortgage process?
Buyers frequently default to the first loan offer they receive instead of comparing tailored options. A rigid, one-size-fits-all approach rarely fits a Walnut Creek household’s actual financial picture. Common mistakes include:
- Failing to research first-time buyer assistance programs before house hunting begins
- Applying to a lender without confirming eligibility for state-approved programs
- Accepting generic loan terms without exploring personalized financing paths
- Working with a lender whose guidance lacks transparency about costs and timelines
Personalized guidance, rather than a generic application, helps borrowers secure financing that fits their circumstances with confidence. A lender built on integrity, clear communication, and a broad range of loan products becomes a far more reliable partner than one offering a single rigid product. Transparent, borrower-first guidance, rooted in honesty rather than sales pressure, keeps buyers from costly missteps at every stage of the loan journey. Walnut Creek buyers ready to move forward can request a direct cash offer on their current property or request your property assessment before starting the mortgage search.
FAQ
What is the first step in buying a home in Walnut Creek?
Assess your financial readiness by reviewing savings, credit score, income, and long-term homeownership goals before getting pre-approved or touring properties.
What loan programs can first-time buyers in Walnut Creek explore?
Walnut Creek buyers can access FHA, VA, USDA, and bank statement loans, plus CalHFA down payment assistance programs designed for first-time and moderate-income homebuyers.
How quickly can buyers get pre-approved with Munshi Capital Inc.?
Pre-approval takes days, not weeks, with transparent underwriting that shows exact loan status from application through closing.
Conclusion
In closing, navigating the first-time homebuyer process in Walnut Creek requires a structured approach grounded in financial preparation, market awareness, and professional guidance. The steps outlined, from assessing your financial readiness through securing financing and closing on your property, establish a clear pathway to homeownership. Partnering with a mortgage lender committed to transparency and personalized service ensures you receive straightforward communication, comprehensive loan options tailored to your circumstances, and dependable support throughout the entire process. Your success as a first-time homebuyer depends on informed decision-making and reliable expertise at every stage.
Leave a Reply