Fresno homebuyers access local down payment assistance, including the City’s Mortgage Assistance Program (MAP), which provides down payment support up to $12,500 for eligible borrowers, and U.S. Bank’s Access Home Loan Program, which offers assistance toward down payment costs, closing costs, or required repairs for qualifying buyers. Munshi Capital Inc. pairs these programs with FHA, VA, USDA, DSCR, and bank statement loans for Fresno buyers and investors.
Key Takeaways
- Fresno’s First-Time Homebuyer Mortgage Assistance Program (MAP) provides down payment support up to $12,500 for eligible borrowers.
- Heritage Estates mortgage assistance requires first-time homebuyer status and household income at or below 80% of Fresno County average.
- Housing Choice Voucher participants can apply monthly voucher amounts directly toward mortgage payments instead of rent through homeownership programs.
- Munshi Capital Inc. offers personalized guidance matching borrowers with local Fresno programs and transparent loan solutions tailored to your financial situation.
What Makes Fresno Mortgage Financing So Complex?
Fresno’s housing market layers multiple loan categories, varying property types, and shifting rate conditions into a single transaction. Buyers move between Fresno’s established neighborhoods and newer developments, and each path carries different financing requirements. A conventional loan that works for a buyer near Woodward Park may not fit an investor eyeing a multi-unit property closer to downtown. This mismatch between buyer goals and available loan products drives most of the confusion.
Fresno neighborhood mortgages span a wide range of programs built for different financial pictures. Munshi Capital Inc. structures its residential lending around that reality, offering access to several distinct paths:
- FHA loans for buyers with limited down payment funds
- VA loans for eligible military borrowers
- USDA loans for qualifying rural and suburban Fresno-area properties
- Bank statement loans for self-employed borrowers without traditional W-2 income
Why do loan options vary by Fresno neighborhood?
Property type, zoning, and local market pricing shift the loan products available in each part of the city. Fresno neighborhood loans must account for these differences before underwriting begins. A dedicated city resource page consolidates current programs, rates, and market insights so buyers compare options for their specific area rather than relying on generic national data.
How does personalized guidance reduce Fresno financing complexity?
Borrowers receive direct support matched to their income structure, credit profile, and purchase timeline. This local Fresno mortgage guide approach pairs fast pre-approval with ongoing visibility into loan status. Applicants always know where their file stands. Clear tracking from application through closing removes much of the uncertainty that typically slows Fresno home purchases down.
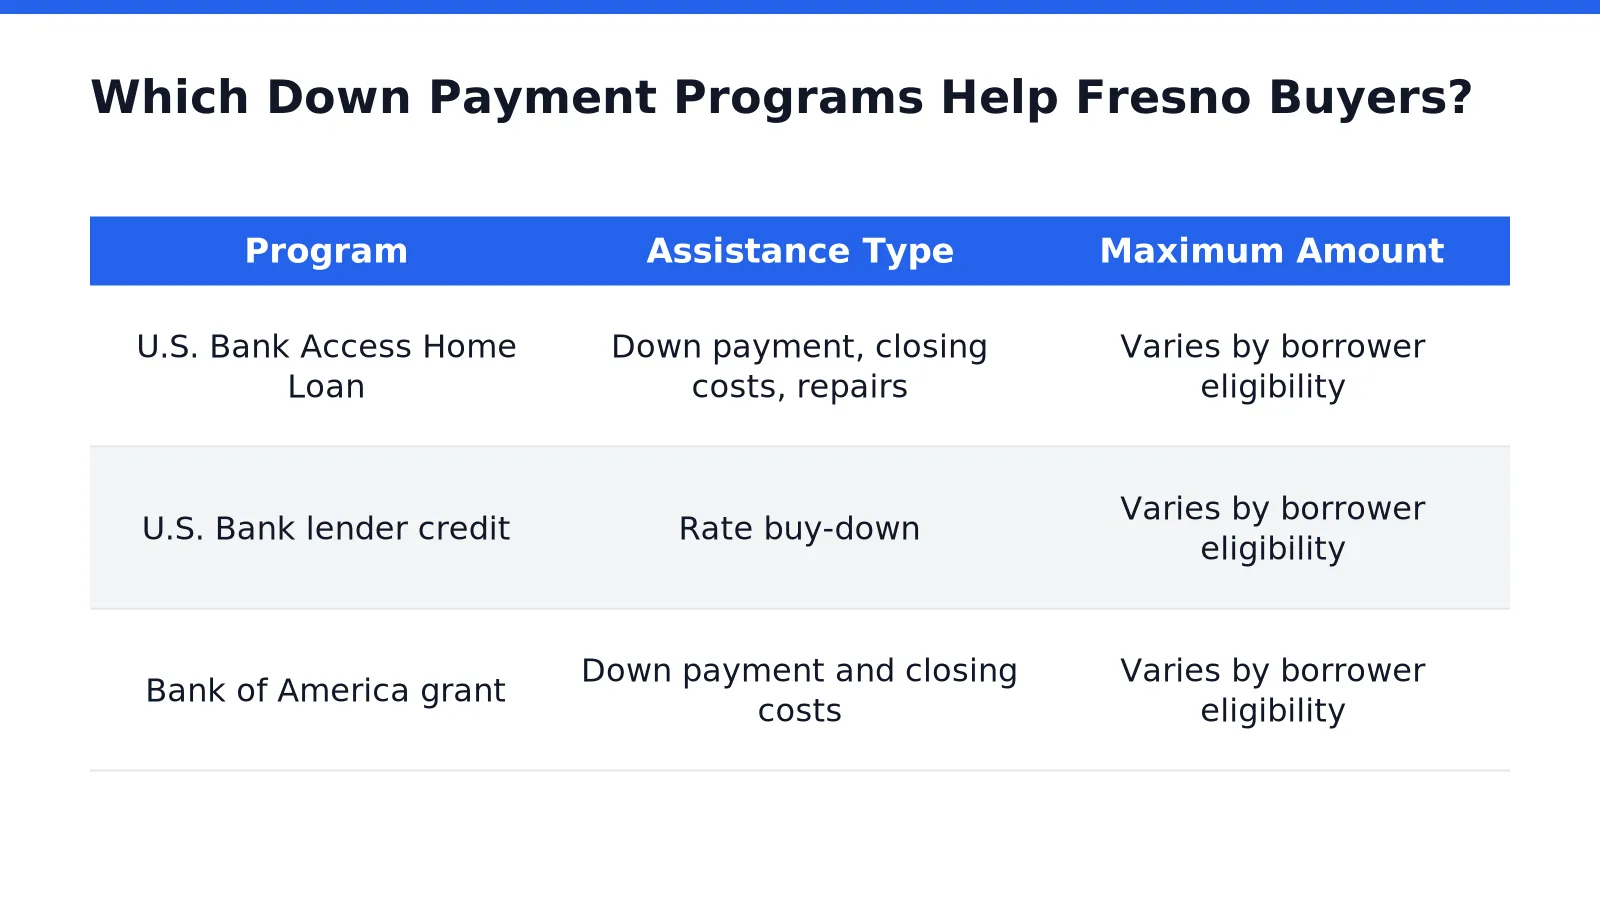
Which Down Payment Programs Help Fresno Buyers?
Several structured programs reduce the cash barrier for Fresno buyers chasing a first home. Fresno Housing and the City of Fresno’s Office of Community Affairs track multiple options. Two bank-backed programs stand out for buyers evaluating mortgages across Fresno neighborhoods.
U.S. Bank’s Access Home Loan Program, a Special Purpose Credit Program, offers assistance toward down payment costs, closing costs, or required repairs for qualifying buyers. On top of that assistance, eligible borrowers can receive an additional lender credit applied directly to buy down the mortgage rate. The purchase price requirement stays low too: buyers need only 3% of the home’s price out of pocket to qualify.
Bank of America runs a separate program offering combined down payment and closing cost grants. Buyers researching Fresno neighborhood loans often compare both options before choosing a lender, since eligibility and assistance amounts differ.
How much cash does a Fresno buyer actually need upfront?
Under the U.S. Bank program, qualifying buyers need as little as 3% of the purchase price. Layering in grant assistance from programs like Bank of America’s can shrink that number even further, depending on eligibility.
Can these programs be combined with a mortgage application?
Yes. Down payment assistance programs typically work alongside a standard mortgage application rather than replacing it. A local Fresno mortgage guide helps buyers map which assistance programs pair with which loan types before submitting paperwork.
Who Qualifies for Fresno’s First-Time Buyer Assistance?
Eligibility hinges on income limits, residency history, and prior homeownership status. Fresno Housing extends mortgage assistance to first-time buyers purchasing homes in developments such as Heritage Estates, giving qualified households a path to ownership they might not reach through a conventional loan alone. Munshi Capital Inc. helps Fresno buyers understand these local programs alongside its own mortgages fresno neighborhoods loan options. Applicants see every available route before committing to one.
Income remains the first hurdle. Applicants must be first-time buyers with household income at or below 80% of Fresno County’s average household income. That threshold shapes nearly every program layered on top of it.
Residency and ownership history matter just as much. Applicants cannot have owned a home in the past three years. They must have lived or worked in Fresno County for at least six months.
What does Fresno County’s loan program offer first-time buyers?
Fresno County’s 1st Time Homebuyer Program provides a zero-interest, deferred payment loan covering up to 20% of the purchase price plus closing costs. No monthly payments accrue during the deferral period, easing the cash burden at closing.
When does the county loan need to be repaid?
Repayment is deferred for 30 years or until the primary mortgage is paid off, whichever happens first. That structure rewards long-term residency rather than quick resale.
Qualification checklist for Fresno assistance programs:
- Household income at or below 80% of Fresno County’s average
- No home ownership within the past three years
- Minimum six months living or working in Fresno County
- Intent to occupy the purchased home as a primary residence
Buyers weighing these local requirements against broader financing paths can connect with a loan specialist to see where they stand before applying for assistance funds.
Can Voucher Holders And Investors Get Financing?
Yes, voucher holders and investors both qualify for financing in Fresno, though each group follows a distinct path. Housing Choice Voucher (HCV) participants can redirect their monthly voucher amount toward mortgage payments instead of rent,
FAQ
What down payment assistance programs are available to Fresno homebuyers?
Fresno’s Mortgage Assistance Program (MAP) and U.S. Bank’s Access Home Loan Program offer qualifying buyers up to $12,500 toward down payment and closing costs, with an additional $5,000 lender credit available through U.S. Bank.
What loan types does Munshi Capital Inc. offer for Fresno buyers and investors?
Munshi Capital Inc. provides FHA, VA, USDA, DSCR, and bank statement loans, matching Fresno buyers and investors with financing suited to their income structure, credit profile, and property type.
How does Munshi Capital Inc. simplify the Fresno mortgage process?
Munshi Capital Inc. pairs fast pre-approvals with ongoing visibility into loan status, giving borrowers clear tracking from application through closing and reducing uncertainty throughout the Fresno home-buying process.
Leave a Reply