Glendale homebuyers navigating Spanish-style, mid-century, and newer-construction neighborhoods get tailored FHA, VA, USDA, bank statement, DSCR, and hard money loan options from Munshi Capital Inc., paired with transparent underwriting and fast pre-approvals. Ownership duration varies based on individual investment strategies and market conditions.
Glendale, California homebuyers navigate a market mixing historic Spanish-style homes, mid-century residences, and new construction, each requiring different financing strategies. Munshi Capital Inc. offers residential and commercial loan programs including FHA, VA, USDA, and bank statement loans. Well as DSCR and hard money loans, guiding first-time buyers, self-employed professionals, and investors through transparent, neighborhood-specific mortgage decisions from pre-approval through closing.
Key Takeaways
- Glendale’s competitive real estate market demands pre-approval from specialized lenders offering FHA, VA, and USDA programs.
- First-time homebuyers benefit from transparent guidance through application, underwriting, and closing without hidden fees or surprises.
- Bank statement and specialized loan products serve self-employed borrowers and investors purchasing Glendale properties with non-traditional income.
- Our loan specialists provide quick pre-approvals and full loan status visibility throughout your entire Glendale home purchase journey.
Why Is Glendale’s Housing Market So Competitive?
Demand outpaces supply across Glendale, California, and that imbalance drives the competition buyers feel firsthand. Housing stock here spans a genuinely varied landscape: historic Spanish-style homes sit alongside mid-century modern residences, with newer condominiums and townhomes filling in the gaps. That mix gives buyers more entry points, but it also means desirable properties in any category attract multiple offers quickly. Anyone researching mortgages-glendale-ca-097 options needs to understand this dynamic before house hunting begins.
Location adds another layer of pressure. Glendale sits within Los Angeles County and offers convenient freeway access to downtown Los Angeles employment hubs, making it attractive to professionals who want city proximity without sacrificing residential character. The result is a blend of urban amenities and neighborhood charm that few comparable markets can match.
What Makes Glendale Attractive to Buyers?
Buyers gravitate toward Glendale for its combination of architectural variety and commuting convenience. Families often cite the community’s residential charm, while professionals weigh in on the shortened commute to Los Angeles job centers.
Is Glendale’s Market Harder for First-Time Buyers?
Competition tends to hit first-time buyers hardest, since inventory across every price point moves fast. Securing glendale-home-loans-097 pre-approval before touring properties shifts the advantage back toward the buyer.
The property types driving this competition include:
- Historic Spanish-style single-family homes
- Mid-century modern residences
- Newer-construction condominiums and townhomes
Navigating these conditions calls for preparation grounded in local knowledge. A clear glendale-mortgage-guide-097 helps buyers, self-employed professionals, and investors move decisively when the right property appears, rather than losing it to a faster-moving offer.
What Loan Programs Fit Glendale Homebuyers?
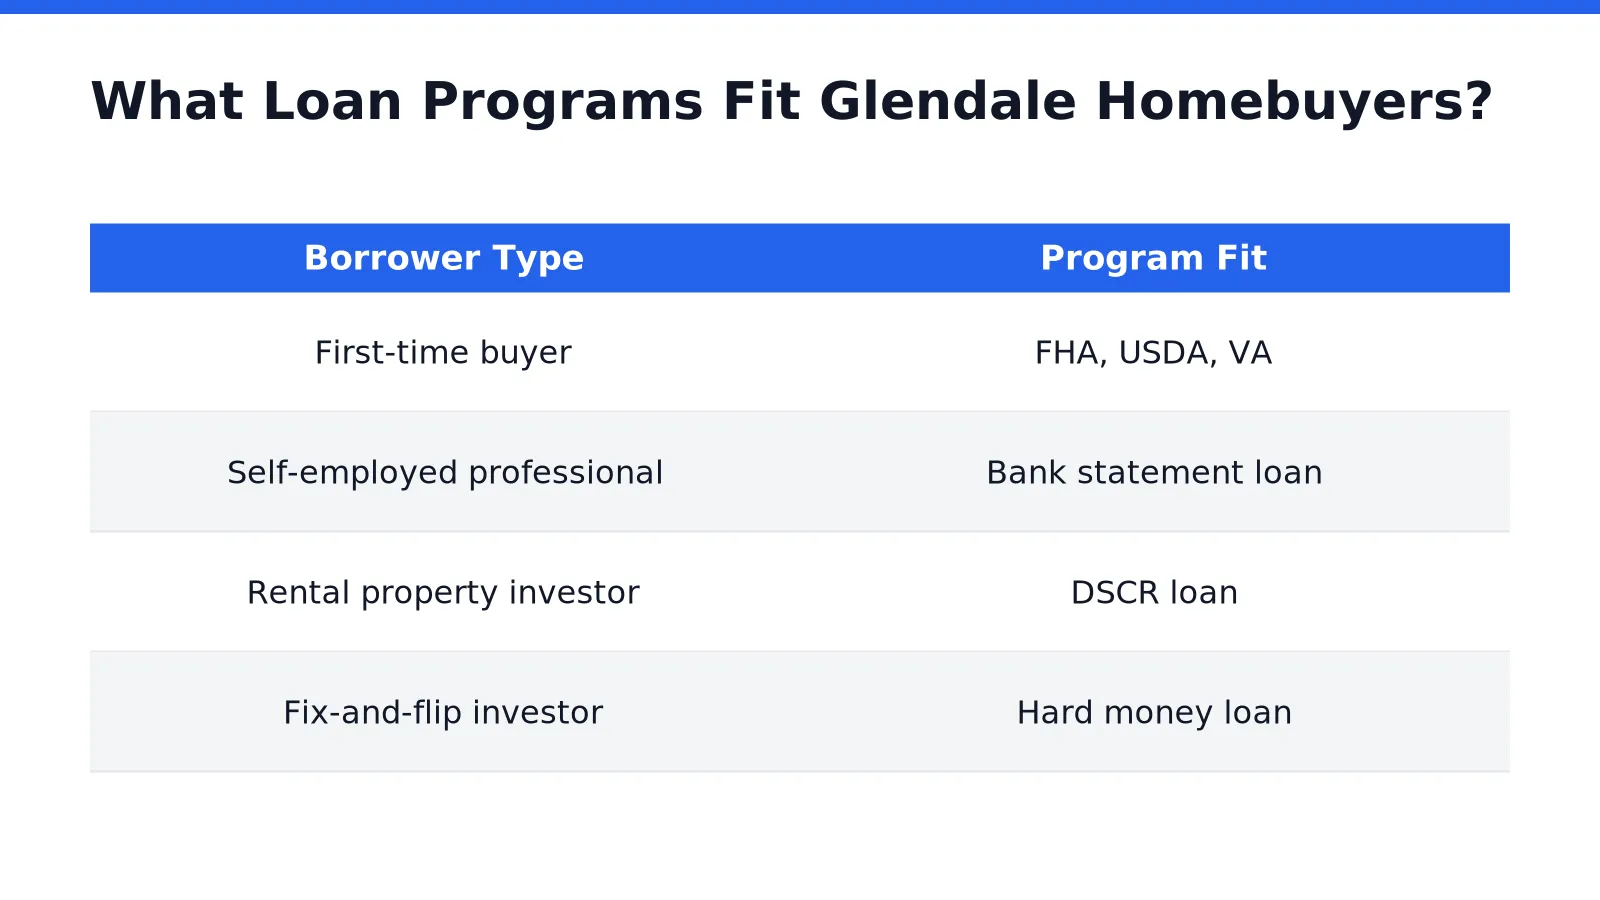
Four federally backed programs, FHA, VA, USDA, and bank statement loans, cover most buyer profiles entering the Glendale market. Each program targets a different financial situation, from limited down payment savings to self-employment income that does not fit a standard W-2 structure. Munshi Capital Inc. structures mortgages-glendale-ca-097 around the borrower rather than forcing applicants into a single rigid product.
Self-employed professionals in Glendale often struggle to document income using traditional pay stubs. Bank statement loans solve this by evaluating deposits and cash flow instead of tax returns alone. First-time buyers, meanwhile, benefit from FHA and USDA structures built for lower down payments and flexible credit requirements.
Which Loan Works Best for Glendale Property Investors?
Investors pursuing rental property or fix-and-flip opportunities in Glendale typically need speed and flexibility that conventional underwriting cannot offer. DSCR loans qualify borrowers based on a property’s rental income rather than personal income documentation. Hard money loans add a fast-closing option for time-sensitive acquisitions, rounding out glendale-home-loans-097 for active investors.
Does One Program Work for Every Glendale Buyer?
No single program fits every buyer entering Glendale’s housing market. Veterans access VA loans with no down payment requirement, while seasoned investors lean on DSCR financing to scale portfolios. A personalized glendale-mortgage-guide-097 matches each applicant to the program suited to income type, property use, and investment timeline, with guidance provided through every step of the loan process.
How Much Home Can You Afford in Glendale?
Affordability in Glendale depends on gross monthly income, existing debt, and the specific loan program a buyer qualifies for. A mortgage calculator offers the clearest starting point, weighing income against financial obligations to estimate real borrowing capacity before house hunting begins in Glendale’s competitive Los Angeles County market. The DFPI recommends keeping housing costs below 31 to 40 percent of gross monthly income, a guideline that holds true whether the target property is a historic Spanish-style home or a newer Glendale condominium.
Credit score strength plays a direct role in the numbers. A stronger score typically unlocks lower mortgage rates. Improving credit before searching for mortgages in Glendale, CA can meaningfully reduce long-term borrowing costs. Lender pre-approval sets a ceiling, but it rarely tells the full story.
Does Pre-Approval Mean a Buyer Can Afford That Amount?
Not necessarily. Approval amounts reflect financial qualifications, not a buyer’s complete financial picture. A realistic budget looks past the monthly mortgage payment and accounts for the full scope of homeownership costs.
Buyers planning Glendale home loans should weigh several moving parts together, not just the sale price:
- Loan program selection (conventional, FHA, VA, USDA, or bank statement options for self-employed borrowers)
- Down payment size and its effect on monthly payment
- Credit qualification requirements
- Closing costs and other transaction expenses
A comprehensive Glendale mortgage guide approach treats these factors as connected, not isolated line items. Investors and self-employed professionals in particular benefit from reviewing all four before committing to an offer. Munshi Capital Inc. helps buyers model these numbers accurately, then invites qualified sellers and property owners to request a direct cash offer when a sale, rather than a purchase, is the goal.
What Steps Guide the Glendale Home Buying Process?
Four stages define the path to closing on a Glendale property: research, affordability review, financing, and purchase. Each stage builds on the last, and skipping one creates costly missteps later.
Research comes first. Buyers need clarity on property type, whether a condo, townhome, or single-family home fits their needs, before scheduling a single showing. Glendale’s housing stock spans historic Spanish-style homes, mid-century residences, and newer construction, so narrowing preferences early saves time and avoids wasted house-hunting trips.
How Can Buyers Spot Neighborhood Trends in Glendale?
Watching asking price shifts across Glendale listings reveals which neighborhoods are heating up and which are cooling. Price movement over several weeks tells buyers more than a single snapshot ever could. This tracking habit also strengthens negotiating position once an offer is on the table.
Buying a home remains a major financial decision with many moving parts: loan options, down payments, credit requirements, and closing costs all interact. None of these pieces work in isolation, which is why sequencing matters.
Should a Glendale Purchase Be Treated as an Investment?
No. Home values do not rise on a guaranteed schedule. A purchase decision built primarily on resale speculation carries real risk. Buyers planning to stay for the long term, rather than flip quickly, tend to weather Glendale’s market swings more comfortably.
Securing the right financing ties these steps together. A sound [mortgages Glendale](https://munshi.biz/mortgages-glendale/) CA strategy, paired with accurate Glendale home loans guidance and a clear Glendale mortgage guide, keeps each stage moving without surprises at the closing table.
How Does Munshi Capital Simplify Glendale Financing?
Munshi Capital removes guesswork from mortgages Glendale CA transactions through clear, honest communication at every stage. Glendale buyers face a competitive Los Angeles County market filled with Spanish-style homes, mid-century residences, and new condominium construction. Confusing loan jargon or hidden terms only add risk to an already fast-moving process. Clarity matters most when decisions move quickly.
Borrowers working toward Glendale home loans move through a defined sequence: application, underwriting, and closing. Each stage is explained before it happens, not after. No hidden surprises appear mid-transaction, and no last-minute conditions derail a closing date. This structure gives first-time buyers, self-employed professionals, and investors a predictable path toward ownership in Glendale’s neighborhoods.
What makes the pre-approval process fast?
Technology and loan specialists work together to accelerate pre-approval timelines. Automated systems handle document intake and status updates, while specialists review the financial picture behind every file. Borrowers gain full visibility into where their loan stands, rather than waiting for scattered updates.
Why does trust matter in a Glendale mortgage?
Trust determines whether a borrower feels confident committing to a purchase offer. Munshi Capital’s approach is built on transparency and a service-driven ethos, not sales pressure.
The following elements define this Glendale mortgage guide approach:
- Honest communication from application through closing
- A defined underwriting process with no concealed conditions
- Technology-driven tracking paired with hands-on specialist support
- A borrower-first philosophy rooted in clarity and honesty
Buyers who want to move forward can request a direct cash offer evaluation or request your property assessment to clarify financing options before making an offer on a Glendale property.
FAQ
What loan programs does Munshi Capital Inc. offer Glendale buyers?
Munshi Capital Inc. provides FHA, VA, USDA, and bank statement loans, plus DSCR and hard money loans for investors, tailoring each option to the borrower’s unique financial picture.
Why should Glendale buyers get pre-approved before house hunting?
Glendale’s competitive market moves fast, with desirable properties across every price point attracting multiple offers quickly. Pre-approval shifts the advantage back toward the buyer.
How does Munshi Capital Inc. support self-employed buyers in Glendale?
Bank statement loans serve self-employed professionals. Investors with non-traditional income, backed by transparent underwriting and personalized guidance from application through closing.
Conclusion
In closing, navigating the Glendale mortgage landscape requires a financing partner committed to transparency and personalized guidance. Munshi Capital Inc. delivers comprehensive loan solutions tailored to your unique financial circumstances, whether you are a first-time homebuyer or experienced investor. Our straightforward application and underwriting processes eliminate confusion, ensuring you understand every step toward homeownership. With access to diverse loan programs and dedicated loan specialists, you gain the clarity and dependable service necessary to secure financing with confidence and move forward with certainty.
Leave a Reply