Harlem homebuyers combine coop, condo, and FHA, VA, or bank statement loan programs through Munshi Capital Inc., a nationwide lender serving Harlem buyers, with local counseling support from West Harlem Group Assistance, Inc. on Amsterdam Avenue, which offers home buying counseling, housing counseling, and rental assistance for first-time purchasers and investors alike.
Key Takeaways
- West Harlem Group Assistance at 1652 Amsterdam Ave. provides home buying counseling and housing counseling services.
- Shared equity home financing requires understanding mortgage products and securing lending partners for buyer qualification.
- Transparent mortgage guidance helps Harlem borrowers navigate FHA, VA, USDA, and specialized loan program options.
- Community resources combined with personalized loan specialist support accelerate pre-approval and closing timelines for homebuyers.
What Shapes Harlem’s Home Buying Landscape?
Harlem’s housing market takes its shape from a mix of historic building stock, specialized ownership structures, and financing rules that differ from a standard home purchase. Brownstones built decades ago continue to draw developers. Nonprofit housing groups looking to convert units into affordable housing, a pattern City Limits documented in its reporting on Harlem development deals. That history still influences what buyers find on the market today: a blend of converted multifamily brownstones, co-ops, and condos, each carrying its own financing path.
Shared equity programs add another layer. Buyers pursuing these arrangements must understand legal instruments such as ground leases or deed-restricted covenants before a lender will approve financing, according to Grounded Solutions Network. These documents affect resale value, monthly costs, and loan eligibility, so reviewing them early protects a buyer from delays at closing.
What mortgage products apply to Harlem buyers?
Grounded Solutions Network notes that buyers and program staff benefit from learning which mortgage products exist. Which barriers lenders face when working with shared equity purchasers. Munshi Capital Inc. builds its harlem-mortgage-guide-093 resources around exactly this gap, pairing mortgages-harlem-093 options with underwriting support suited to co-op boards, deed restrictions, and brownstone conversions.
Why does property type matter for financing?
Property type determines which loan programs apply and how quickly approval moves forward:
- Co-ops often require board review alongside lender approval.
- Deed-restricted or ground-lease properties need specialized underwriting.
- Converted brownstones may carry mixed-use or multifamily financing rules.
Buyers evaluating harlem-home-loans-093 options should confirm these details before making an offer.
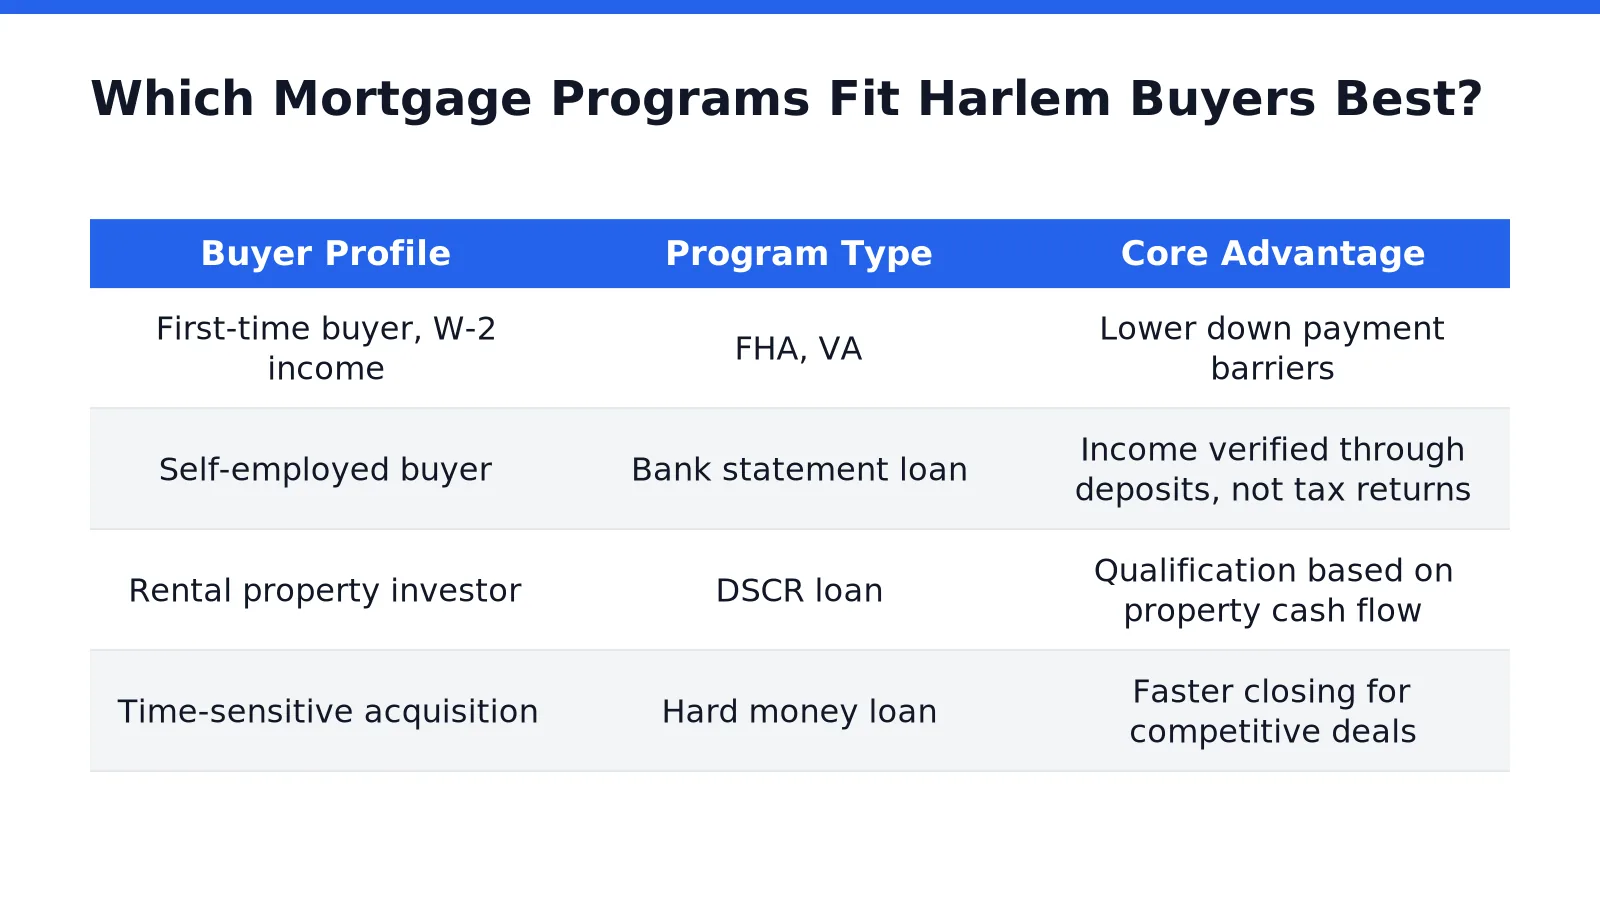
Which Mortgage Programs Fit Harlem Buyers Best?
No single loan fits every Harlem purchase. A condo on Striver’s Row calls for different financing than a multi-family rental near 125th Street. Munshi Capital Inc. structures harlem-home-loans-093 around the buyer’s actual financial profile rather than a one-size-fits-all product, offering FHA, VA, USDA, and bank statement loan programs under one roof. Each option serves a distinct borrower: FHA suits buyers with limited down payment funds, VA serves eligible veterans, USDA applies to qualifying property types, and bank statement loans help self-employed Harlem residents whose tax returns don’t reflect full earning power.
What loan options work for Harlem investors?
Investors eyeing rental units or multi-family buildings in Harlem need financing that moves fast and underwrites on property performance, not just personal income. DSCR loans qualify borrowers based on a property’s rental income potential. Hard money loans provide short-term capital for buyers competing on timing, such as those pursuing a distressed brownstone before rehab and resale.
Choosing between these programs depends on the buyer’s goals and the property itself:
How does Munshi Capital Inc. match buyers to the right program?
Personalized guidance drives every recommendation. Loan specialists review a borrower’s income structure, property type, and investment timeline before narrowing the field. This harlem-mortgage-guide-093 approach exists precisely because Harlem’s housing stock, from prewar co-ops to new-construction condos, demands flexible mortgages-harlem-093 solutions rather than a single standard product.
Where Can Harlem Buyers Find Housing Counseling?
West Harlem Group Assistance, Inc. answers this question directly from its Amsterdam Avenue location. The organization provides home buying counseling, general housing counseling, and rental assistance to residents preparing for a purchase. Buyers working through harlem home loans decisions benefit from sitting down with a counselor before signing a contract. Guidance on budgeting, credit readiness, and paperwork reduces costly surprises later in the process.
A second resource, the Harlem Community Justice Center, extends support across a wider footprint. The center serves East, Central, and West Harlem through programs built around stable housing, neighborhood safety, and community stability. Its reach matters for condo and co-op purchasers who need neighborhood-level context, not just loan math.
What Programs Does the Justice Center Offer?
The Housing Help Center sits alongside several other initiatives under the Justice Center’s umbrella. These include Youth and Community Programming, the Men’s Empowerment Program, Girl Talk, Reentry Services, and the Neighborhood Safety Initiative. Stable housing remains a central theme across these offerings, making the Housing Help Center a natural starting point for buyers seeking local orientation before financing conversations begin.
How Should Buyers Combine Counseling With Financing?
Counseling organizations clarify budgets and documentation; lenders translate that preparation into an actual loan offer. Pairing a session at West Harlem Group Assistance with a review of available mortgages harlem options builds a realistic purchase timeline. For buyers assembling a full harlem mortgage guide, local counseling services and loan program research work best as complementary steps, not substitutes for one another.
How Does Munshi Capital Simplify Harlem Financing?
Munshi Capital Inc. removes friction from Harlem home financing by combining a clear process with hands-on guidance. Buyers move through application, underwriting, and closing without hidden surprises, a structure built for Harlem’s co-op boards, condo associations, and multi-unit brownstones alike. Each step stays visible from the first document request to the closing table.
Technology drives much of that visibility. Modern loan-tracking tools paired with dedicated loan specialists give Harlem buyers quick pre-approvals. A transparent view of where their file stands at any moment. A first-time buyer eyeing a condo near Marcus Garvey Park. An investor evaluating a multi-family property on Lenox Avenue, gets the same real-time status updates rather than vague promises of “we’ll call you back.”
The process itself starts simply. Harlem buyers complete a quick, secure application and share their goals directly with a loan specialist, who then identifies which residential or commercial program fits the purchase.
What Happens After Submitting a Harlem Mortgage Application?
A loan specialist reviews the buyer’s goals. Property type, then recommends a residential or commercial program suited to the purchase. From there, underwriting begins, and the buyer receives steady updates rather than silence.
Why Does Transparency Matter for Harlem Mortgage Shopping?
Co-op and condo transactions in Harlem often involve board approvals and strict timelines. A transparent harlem-mortgage-guide-093 process, paired with clear harlem-home-loans-093 updates, keeps buyers prepared for each deadline instead of guessing.
Munshi Capital Inc.’s approach to mortgages-harlem-093 financing centers on:
- Clear application steps with no hidden conditions
- Real-time loan status visibility
- Direct access to a dedicated loan specialist
Ready To Secure Your Harlem Home Loan?
Harlem buyers move forward once financing feels clear rather than confusing. Munshi Capital Inc. built its mortgage guidance around the borrower, pairing harlem-home-loans-093 options with straightforward answers at each stage of the loan program. Clarity replaces guesswork, and dependable service carries buyers from application through closing.
Trust anchors that process. Munshi Capital Inc.’s lending approach stays rooted in transparency. Honesty, a foundation built to serve borrowers pursuing homes across the country, Harlem included. Co-op and condo purchasers face board approvals and building-specific financial requirements that differ from a standard single-family purchase. A service-driven, borrower-first approach helps buyers understand those distinctions before they sign anything, rather than discovering surprises at the closing table.
Should First-Time Buyers Get Counseling Before Applying For A Mortgage?
Preparation strengthens any loan application. Local resources such as home buying counseling help buyers organize finances, understand loan terms, and walk into the mortgage process with fewer unknowns. Pairing that counseling with transparent, borrower-first guidance from Munshi Capital Inc. gives Harlem buyers a stronger starting position before they ever submit paperwork.
What Makes A Harlem Mortgage Guide Useful For Investors?
A sound harlem-mortgage-guide-093 explains how different loan programs fit different buyer profiles, from a first purchase to an investment property. Investors benefit most when guidance stays specific to their financial picture rather than generic.
Readiness starts with a conversation, not a guessing game. Buyers evaluating mortgages-harlem-093 can request a direct cash offer to understand property value quickly. Request your property assessment to clarify the numbers before applying for financing.
FAQ
What mortgage programs does Munshi Capital Inc. offer Harlem buyers?
Munshi Capital Inc. provides FHA, VA, USDA, and bank statement loans, along with DSCR and hard money loans, tailoring each option to the borrower’s unique financial profile and goals.
Where can Harlem buyers find local home buying counseling?
West Harlem Group Assistance, Inc. at 1652 Amsterdam Ave offers home buying counseling, housing counseling, and rental assistance for first-time purchasers and investors.
Why does property type matter when financing a Harlem home?
Property type determines the loan path: co-ops require board review, deed-restricted or ground-lease properties need specialized underwriting, and converted brownstones may involve mixed-use or multifamily financing rules.
Conclusion
In closing, Harlem residents navigating the mortgage landscape benefit from access to diverse financing solutions tailored to individual circumstances and investment objectives. Whether pursuing homeownership through conventional pathways or exploring specialized lending products, borrowers gain advantage through transparent processes that eliminate ambiguity and establish clear expectations from application through closing. The combination of comprehensive loan programs, personalized guidance, and commitment to straightforward communication positions qualified borrowers to make informed decisions with confidence and secure financing aligned with their long-term goals.
Leave a Reply