Staten Island mortgage options span FHA, VA, USDA, bank statement, DSCR, and hard money loans, serving buyers navigating a median home price near $710,000-$750,000. Munshi Capital Inc., based in Walnut Creek, CA, provides financing to Staten Island homebuyers, self-employed borrowers, and investors through transparent underwriting, fast pre-approvals, and loan programs tailored to each borrower’s financial situation.
Key Takeaways
- Staten Island’s median home price ranges from $710,000 to $750,000, offering affordability compared to Manhattan and Brooklyn.
- Munshi Capital Inc. offers FHA, VA, USDA, bank statement, DSCR, and hard money loans for diverse borrower needs.
- Our transparent application and underwriting process eliminates hidden surprises with clear answers at every step.
- Loan specialists provide personalized guidance and quick pre-approvals with full visibility into your loan status throughout closing.
Why Is Staten Island’s Housing Market Different?
Staten Island stands apart from the rest of New York City on price alone. The borough’s median listing price lands near pricing varies according to the Staten Island Mortgage Banker Guide, well below what buyers face in Manhattan or Brooklyn. That gap changes who can realistically compete for a home here. It changes how mortgages for Staten Island buyers need to be structured.
Pricing data for 2025 sharpens the picture further. The First-Time Homebuyer’s Guide to Staten Island NY 2025 places the borough’s median home price between $710,000 and $750,000. That range still beats Manhattan and Brooklyn. The Staten Island Ferry keeps commuters connected to Manhattan without the price tag attached to living there.
Is Staten Island affordable for first-time buyers?
Affordability is relative, but the comparison matters. A first home in Staten Island remains an attainable milestone for buyers who secure the right guidance and financing early. Clear direction on loan options, down payment strategy, and timing turns an intimidating process into a manageable one.
What sets the borough apart, in short form:
- Median listing price near pricing varies lower than Manhattan or Brooklyn
- 2025 median range of $710,000-$750,000 with ferry access to Manhattan intact
- Achievable entry point for first-time buyers with proper financing guidance
Staten Island home loans need to account for this pricing gap directly, since standard loan limits and down payment assumptions built around Manhattan pricing rarely fit here. A properly built Staten Island mortgage guide treats the borough as its own market, not a cheaper footnote to the rest of the city.
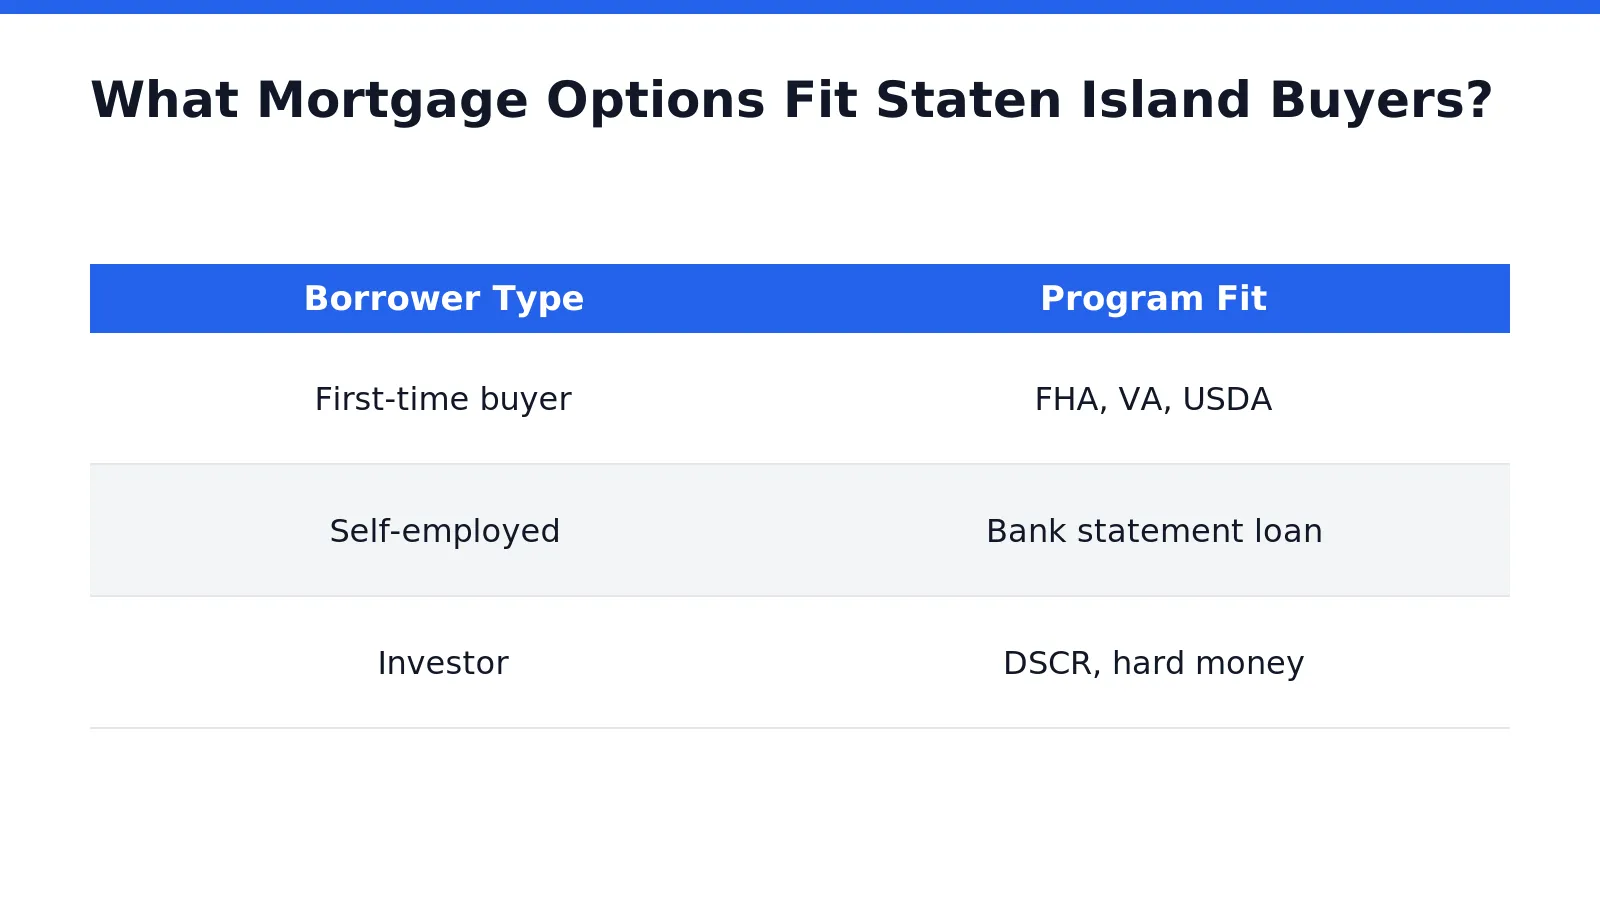
What Mortgage Options Fit Staten Island Buyers?
Staten Island buyers draw from several distinct loan categories, each suited to a different financial profile. First-time buyers, self-employed professionals, and seasoned investors across the borough rarely fit one mold. The right financing path depends on income structure, credit history, and property type. Munshi Capital Inc. provides mortgages Staten Island residents can match to their actual circumstances, not a one-size-fits-all product.
A full home-buying approach in Staten Island covers more than loan selection alone. It accounts for local assistance programs, neighborhood-by-neighborhood navigation, and the financing structure that ties everything together. Skipping any one piece leaves buyers exposed to delays or financing gaps late in the process.
What loan programs does Munshi Capital offer Staten Island borrowers?
Munshi Capital Inc. provides a full suite of Staten Island home loans, including FHA, VA, USDA, and bank statement loan programs. Each program targets a different borrower need, from low down payment requirements to income verification built around bank deposits rather than tax returns. Residential and commercial options sit side by side, so growing families and business owners both find a workable path.
Are there financing options for Staten Island real estate investors?
Investors purchasing rental or commercial property in Staten Island can access DSCR loans, which qualify based on property cash flow rather than personal income. Hard money loans offer a faster, asset-based alternative for time-sensitive deals.
Every program above is built around the borrower’s actual financial picture, not a generic checklist. A Staten Island mortgage guide only holds value when it connects program details to real underwriting decisions. That connection is where guidance matters most.
How Do You Shop, Compare, And Negotiate?
Shopping for Staten Island home loans means comparing multiple lender types before signing anything. Borrowers who skip this step risk locking into higher fees or unfavorable terms for the life of the loan. A disciplined comparison process protects a buyer’s budget on properties across the borough, from Tottenville to St. George.
Several categories of lenders serve Staten Island borrowers, and each operates differently.
- Direct mortgage lenders, who fund loans themselves
- Mortgage brokers, who shop multiple lenders on a borrower’s behalf
- Credit unions and local banks, which often hold their own portfolio loans
Why does lender compensation matter?
Compensation structures vary widely, and that variation shows up in the fees borrowers pay. Some brokers earn a apartment fee; others earn a percentage of the loan amount or a rate markup. Asking directly how a broker or lender gets paid allows for an apples-to-apples comparison across offers, not just a glance at the advertised rate.
Should buyers negotiate loan terms?
Negotiation is not optional for serious buyers working through a Staten Island mortgage guide. Rates, points, and closing costs are frequently adjustable when a borrower comes prepared with competing offers. Buyers who treat the first quote as final often leave money on the table.
Munshi Capital Inc. serves Staten Island borrowers directly, laying out loan options with full fee transparency. Comparison shopping stays simple rather than stressful. Current homeowners weighing a refinance benefit from the same scrutiny applied to mortgages in Staten Island. Even a slightly better rate changes the total cost over the loan’s term. Those ready to take the next step can request your property assessment and begin comparing terms with confidence.
What Does The Munshi Capital Process Involve?
Four stages define the Munshi Capital process: application, underwriting, closing, and ongoing support for Staten Island borrowers. Each stage follows a defined sequence, with no hidden surprises buried in fine print. Staten Island buyers, from first-time homeowners in New Dorp to investors eyeing multifamily units near the ferry terminal, move through the same structured path.
Clarity drives every step. Munshi Capital pairs modern underwriting technology with hands-on loan specialists, a combination that keeps mortgages-staten-island-091 moving without unnecessary delay. Borrowers see their file status at every stage, not just at the start and finish.
How Fast Can Staten Island Borrowers Get Pre-Approved?
Pre-approval timelines move quickly for most applicants. In many cases, a borrower reviewing a loan application today could already hold pre-approval by the time the review ends. Staten Island homebuyers competing for properties in neighborhoods like Tottenville or Great Kills benefit from that speed. Faster pre-approval strengthens an offer before a seller moves on.
The process breaks down into four parts:
- Application: borrowers submit income, credit, and property details specific to the Staten Island purchase or refinance.
- Underwriting: loan specialists verify documentation and confirm eligibility across FHA, VA, USDA, DSCR, or bank statement programs.
- Closing: terms are finalized with full visibility into fees and conditions.
- Post-closing support: specialists remain available for questions on staten-island-home-loans-091 after funding.
Why Does Transparency Matter in Staten Island Mortgage Financing?
Transparency protects borrowers from surprise costs and shifting terms late in the process. Staten Island property values and loan structures vary by neighborhood. A dependable staten-island-mortgage-guide-091 keeps expectations grounded in fact rather than guesswork.
Sellers and buyers across Staten Island can request a direct cash offer or request your property assessment to see where their financing stands before committing further.
Ready To Start Your Staten Island Home Loan?
Progress toward a Staten Island property starts the moment a buyer submits a loan application. Delay carries a real cost: homes in competitive neighborhoods like Tottenville or New Dorp move quickly, and financing gaps can mean losing a preferred property to a faster buyer. Munshi Capital Inc. structures its staten-island-mortgage-guide-091 process so borrowers lose no ground to slower, less transparent lenders.
Dedicated loan officer support exists for one reason: helping local buyers move financing forward without confusion. Staten Island borrowers working with knowledgeable, locally attentive guidance avoid the stalled paperwork and unanswered questions that derail closings elsewhere.
What makes Munshi Capital different for Staten Island borrowers?
Munshi Capital Inc. operates on trust. Clarity, honesty, and a service-driven ethos guide every file, from first conversation to closing table. Borrowers pursuing mortgages-staten-island-091 receive straight answers rather than vague timelines or shifting terms.
How does personalized guidance help Staten Island buyers?
A dedicated team works alongside each borrower, whether a first-time buyer in Great Kills or a seasoned investor eyeing multifamily property in Stapleton. That hands-on support turns staten-island-home-loans-091 into a manageable, confident process rather than a guessing game.
Borrowers ready to move forward can request a direct cash offer. Homeowners weighing a sale first should request your property assessment before locking in financing terms.
FAQ
What loan programs does Munshi Capital Inc. offer Staten Island buyers?
Munshi Capital Inc. offers FHA, VA, USDA, bank statement, DSCR, and hard money loans, covering first-time homebuyers, self-employed borrowers, and investors with financing tailored to each client’s financial picture.
Why is Staten Island more affordable than Manhattan or Brooklyn?
Staten Island’s median home price ranges from $710,000 to $750,000, lower than Manhattan or Brooklyn. The Staten Island Ferry still provides commuter access to Manhattan.
What makes the Munshi Capital Inc. loan process transparent?
Borrowers move through a straightforward application, underwriting, and closing process with clear answers at every step, backed by fast pre-approvals and full visibility into loan status from start to finish.
Conclusion
In closing, navigating Staten Island’s mortgage landscape requires a partner committed to transparency and personalized guidance. The right lender understands your unique financial circumstances and delivers straightforward communication throughout the application, underwriting, and closing process. By prioritizing clarity over complexity and pairing modern technology with dedicated loan specialists, borrowers gain the confidence and visibility necessary to secure financing that aligns with their objectives. Your path to homeownership or investment success begins with dependable service and honest expertise.
Leave a Reply