Content gaps in Walnut Creek, California mortgage broker coverage center on low-down-payment programs, bank statement loans for self-employed borrowers, and DSCR financing for investors, topics underserved despite the 2026 “Market-Ready” initiative’s focus on first-time buyer guides. Munshi Capital Inc. fills these gaps with FHA, VA, USDA, DSCR, and hard money loan content tailored to East Bay borrowers.
Key Takeaways
- First-time homebuyers in Walnut Creek qualify for financing with down payments below the outdated 20% benchmark requirement.
- Mortgage keyword intelligence aligns search intent to specific page types, helping borrowers find tailored loan solutions faster online.
- Transparent loan officers rank higher by optimizing websites for actual borrower search terms, not inflated keyword volume metrics.
- Personalized guidance through FHA, VA, USDA, and bank statement programs converts organic visibility into qualified mortgage inquiries consistently.
What Gaps Exist In Walnut Creek Mortgage Content?
Local mortgage content in Walnut Creek skews narrow. A competitor content gap analysis of the market reveals that most local guidance centers on a single first-time homebuyer resource rather than a full menu of loan programs, leaving self-employed borrowers and investors with limited resources.
That narrow focus creates a real content gap in mortgage coverage for the East Bay. Down payment requirements are often misunderstood, with many believing the outdated 20% benchmark instead of recognizing lower options. Qualified buyers walk away discouraged, assuming they need savings they don’t actually need.
Why does Walnut Creek need city-specific mortgage pages?
Most competitor sites publish general advice without local detail. A city-level page lets a borrower in Walnut Creek compare loan programs, rates, and market conditions specific to that address, rather than sorting through generic national content.
Who gets overlooked in current local content?
Investors chasing cash-offer competition rarely see tailored guidance. One local initiative pairs low-down-payment options with faster underwriting specifically to help buyers compete against cash offers, a sign that investor-focused financing remains thin across Walnut Creek content overall.
This points to a clear loan-related SEO opportunity for Munshi Capital Inc., which already serves borrowers across California and the country with:
- First-time homebuyer programs, including FHA, VA, and USDA options
- Bank statement loans for self-employed applicants
- DSCR and hard money products built for investors
- Local market insights tied to the specific city where a borrower is purchasing
Coverage built around these categories, rather than a single generic guide, matches what Walnut Creek borrowers are actually searching for.
Which Loan Programs Are Underserved Locally?
Walnut Creek borrowers face a narrow menu of loan programs on most local lending sites. FHA, VA, USDA, and bank statement loan programs remain largely absent from that menu, even though these programs serve buyers far beyond the typical first-time purchaser. Self-employed professionals in the East Bay often skip homeownership entirely because conventional-only pages never mention an alternative path.
A thorough competitor content gap analysis of Walnut Creek mortgage pages shows the same pattern repeating: conventional loans and first-time buyer tips, little else. That narrow focus creates a mortgage content gap for military families, rural-adjacent buyers near Walnut Creek, and self-employed applicants who cannot document income the traditional way. Munshi Capital Inc. fills that space with a comprehensive suite of residential loan programs built for a wide range of financial pictures, not a single borrower type.
Investor financing shows an even sharper divide. DSCR and hard money loans serve real estate investors purchasing rental property or flipping homes near Walnut Creek. These specialized products rarely appear on guides written for retail buyers. That absence marks a clear SEO opportunity for loan content aimed squarely at investors.
Why Do DSCR and Hard Money Loans Matter for Walnut Creek Investors?
DSCR loans qualify investors using projected rental income instead of personal income documentation, a critical option for Walnut Creek landlords buying additional units. Hard money loans provide short-term, asset-based financing for fix-and-flip projects where speed matters more than a lengthy underwriting file. Both products target investors, a category largely missing from first-time buyer-focused local guides.
Beyond product selection, the process itself sets underserved content apart. Munshi Capital Inc. guides Walnut Creek borrowers through application, underwriting, and closing with clarity at every step, avoiding the vague promotional language common on competing sites. Borrowers considering a sale alongside a purchase can request a direct cash offer. Homeowners weighing their equity position can request your property assessment before deciding on next steps.
How Does Search Intent Reveal SEO Opportunity?
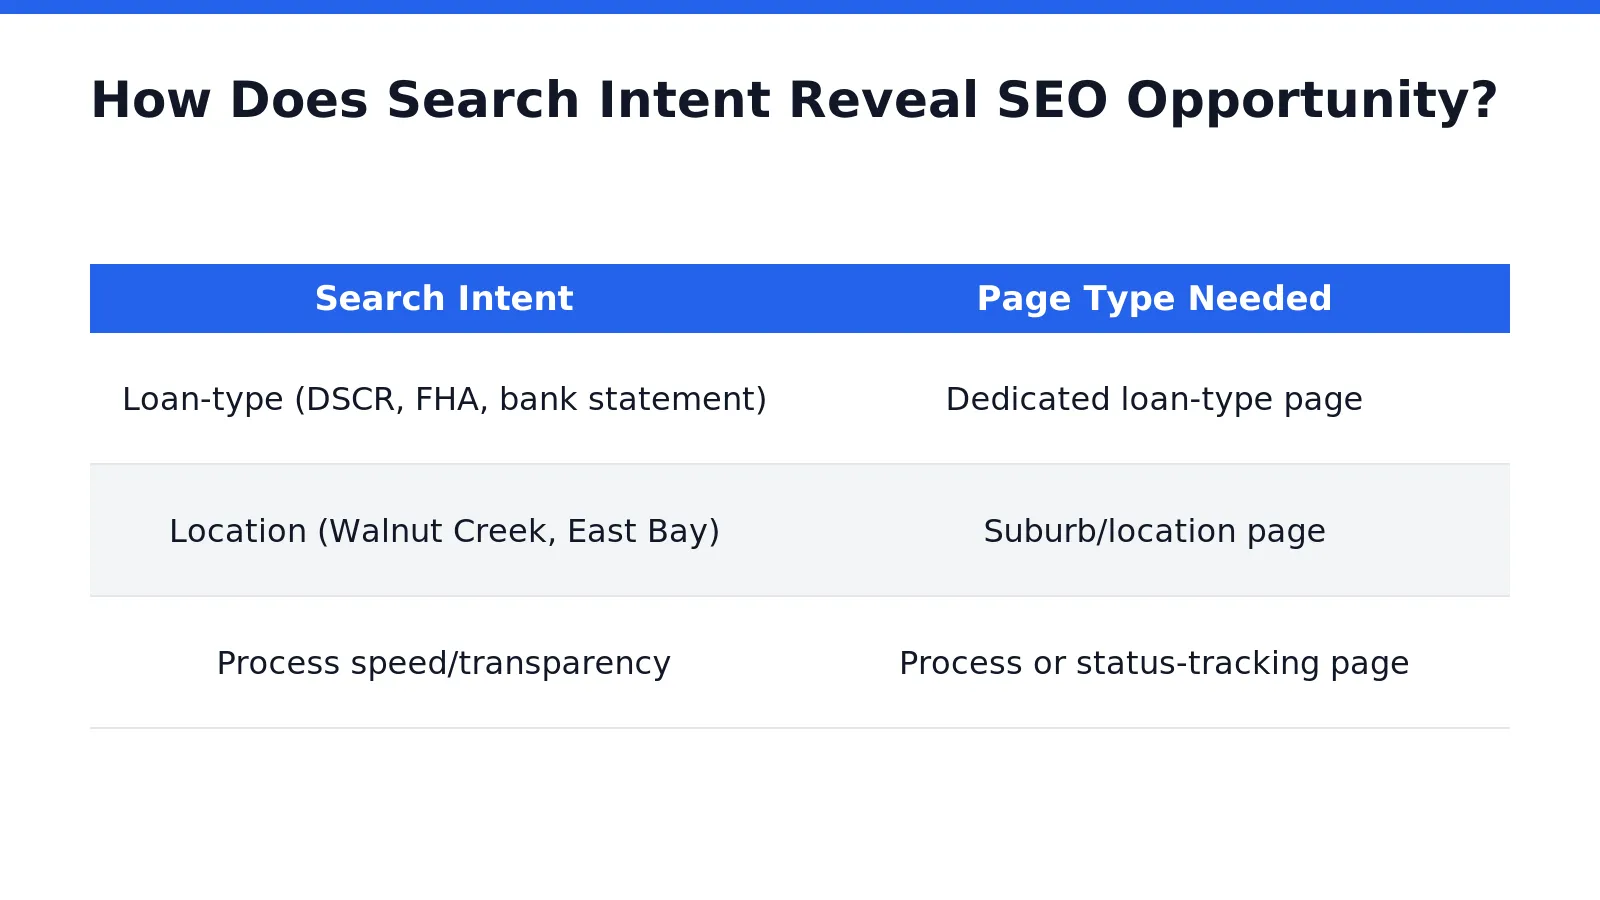
Search intent exposes SEO opportunity in loan content by showing exactly what a Walnut Creek borrower wants to know before clicking a result. Grouping searches by intent, not raw volume, matches each query cluster to the right page type: a loan-type page for FHA or DSCR questions, a location page for Walnut Creek neighborhoods, or a calculator for payment estimates. A search for “bank statement loan Walnut Creek” signals a self-employed borrower ready to compare lenders. “first-time homebuyer programs East Bay” signals someone still researching.
Finance searches carry added weight with search engines. Ranking requires more than a keyword match. It demands the exact answer a borrower needs, backed by demonstrated lending expertise on a dedicated page.
What role does a content gap play in mortgage rankings?
A content gap analysis of competitors shows which borrower questions go unanswered on existing Walnut Creek mortgage pages. Missing pages on DSCR loans for East Bay rental investors or hard money financing for fix-and-flip buyers represent lost visibility. Filling those content gaps in mortgage pages, rather than duplicating generic guides, captures searches competitors ignore.
Which signals matter most for process-speed searches?
Searches tied to speed and transparency, such as “fast mortgage pre-approval Walnut Creek,” reward pages proving quick turnaround. Munshi Capital Inc. pairs modern underwriting technology with hands-on loan specialist service, supporting rapid pre-approvals and full visibility into loan status at every stage.
What Content Formats Are Competitors Missing?
Competitor review of mortgage sites targeting Walnut Creek, California reveals a pattern: technical jargon dominates. Practical borrower questions go unanswered. A thorough competitor content gap analysis shows that ranking success comes from optimizing for the terms borrowers actually search, not generic industry language built for insiders. Many broker sites serving the East Bay still default to that jargon, missing first-time buyers and self-employed applicants searching for plain answers about financing options.
Some lending-industry blogs lean heavily into institutional topics: credit union agency sales, GSE seller patterns, and HOEPA price-trigger thresholds. Those subjects matter to secondary-market professionals managing loan portfolios. They say almost nothing to a Walnut Creek investor weighing a DSCR loan against a bank statement loan. A first-time buyer trying to understand FHA versus conventional financing.
What topics are missing from most mortgage broker content?
Few sites publish content mapped to the real decision points East Bay buyers face. The content gap in mortgage marketing shows up as missing comparisons, missing local context, and missing guidance for non-traditional income documentation.
Formats largely absent from competitor pages include:
- Side-by-side loan comparisons (FHA vs. VA vs. USDA vs. bank statement loans)
- Walnut Creek neighborhood-specific affordability breakdowns
- Investor-focused guides covering DSCR and hard money qualification
- Step-by-step underwriting and closing explainers for self-employed borrowers
This open seo opportunity for loans content favors a lender offering a wide product suite alongside integrity and personalized service. Covering FHA, VA, USDA, bank statement, DSCR, and hard money programs in one place fills the exact gap that jargon-heavy industry blogs leave behind for Walnut Creek homebuyers and investors.
How Should Walnut Creek Borrowers Use This Map?
Walnut Creek borrowers should treat this map as a checklist, not a sales pitch. Local buyers and investors can line up lender pages side by side to see which ones actually answer a question and which ones simply claim expertise. That comparison is the core of a competitor content gap analysis: finding where rival lenders speak in generalities while leaving borrowers without real guidance on FHA, VA, USDA, bank statement, or DSCR programs.
A clear content gap in mortgage information shows up fast in Walnut Creek search results. Many lender sites repeat the same loan-program descriptions without explaining how a self-employed borrower in the East Bay actually qualifies. How an investor structures financing on a rental property. A borrower-first approach rooted in clarity and honesty closes that gap. It functions as a reliable partner through each stage of the loan journey, the standard Walnut Creek borrowers should expect from lender content and lender service alike.
What Should Borrowers Look For When Comparing Lenders?
Borrowers should look for guidance across every loan program, not just the common ones. Mortgage financing built around the borrower, paired with clear answers and dependable service, defines the SEO opportunity in loans that most competitors are not fully claiming in Walnut Creek search results.
How Does This Translate Into Next Steps?
A ready borrower can start with a quick, secure application. Sharing goals with a loan specialist, and naming which residential or commercial program fits, moves the process from research straight into pre-approval without delay. That single step turns a comparison exercise into forward motion.
FAQ
What loan programs does Munshi Capital Inc. offer Walnut Creek borrowers?
Munshi Capital Inc. provides FHA, VA, USDA, and bank statement loans, along with DSCR and hard money products, covering first-time buyers, self-employed applicants, and investors.
Why do many Walnut Creek borrowers think they need a 20% down payment?
Local content repeats the outdated 20% benchmark as a fixed requirement instead of explaining lower-down-payment options, discouraging qualified buyers unnecessarily.
Who is currently underserved by Walnut Creek mortgage content?
Self-employed professionals and investors are overlooked. Most local pages cover only conventional loans and first-time buyer tips without bank statement or DSCR financing guidance.
Conclusion
In closing, the Walnut Creek mortgage market presents distinct opportunities for lenders who prioritize transparency and comprehensive loan solutions. Competitors addressing fragmented borrower needs through specialized programs, from investor-focused DSCR. Hard money products to first-time homebuyer options like FHA and VA loans, establish meaningful differentiation. The most compelling positioning emerges when lenders combine broad product depth with streamlined processes, clear communication, and personalized guidance that removes friction from the borrowing experience. This alignment between diverse financing capabilities and borrower-centric service defines the competitive advantage in an increasingly sophisticated regional market.
Leave a Reply