Munshi Capital Inc.’s online mortgage application portal includes a secure document-upload system that gathers financial paperwork with borrower permission, a custom dashboard tracking real-time application status, and sign-on access for returning applicants to prefill fields. Borrowers also receive preapproval guidance and next-step prompts, keeping the process transparent from initial eligibility check through closing.
Key Takeaways
- Submit basic information online and receive an initial eligibility check from our mortgage consultant within hours.
- Access your custom dashboard to track application status, next steps, and document requirements in real time.
- Skip manual document gathering, we collect your financial records securely with your permission through our portal.
- Complete your entire application online without visiting an office, then connect with our loan specialists for personalized guidance.
Why Apply for a Mortgage Online Today?
Speed and transparency answer the question directly. A digital mortgage application removes the paperwork scavenger hunt that slows traditional lending, letting borrowers submit financial documents through a secure online-application-portal instead of chasing paper files by hand. Munshi Capital Inc. pairs this technology with hands-on loan specialist support, so borrowers get fast processing without losing personal guidance.
The process stays transparent from the first click. Borrowers who choose to apply for a mortgage online move through application, underwriting, and closing with no hidden surprises buried in fine print. Each stage stays visible, so clients always know where their loan stands.
Timing matters most in competitive housing markets. Preapproved buyers receive priority consideration from sellers, which means completing the online process before house-hunting begins carries real weight.
Is It Faster to Apply for a Mortgage Online?
Yes. A digital mortgage portal lets lenders gather financial documents directly, with borrower permission, instead of waiting for mailed or faxed paperwork. That cuts delays common in paper-based applications and speeds up the preapproval timeline sellers look for.
What Do Borrowers Need Before Applying Online?
Borrowers should expect to provide income details, employment history, and documentation that verifies creditworthiness. Having these ready before starting the online-application-portal process shortens the time between application and preapproval.
Consider what changes with a digital approach:
- Document collection: gathered electronically instead of mailed or hand-delivered
- Status visibility: tracked step-by-step rather than learned through phone calls
- Preapproval speed: positions buyers to compete for homes before offers are due
- Process clarity: underwriting and closing steps explained upfront, not discovered later
Borrowers ready to move forward can inquire about financing options that suit their specific situation.
What Features Define a Modern Application Portal?
A modern application portal combines secure document handling, real-time status updates, and direct access to a loan specialist in one place. Five features separate a true digital mortgage portal from a basic contact form.
Full visibility ranks as the defining feature. Munshi Capital’s lending process gives borrowers a clear view of their loan status from the first submission through closing. No guessing games. No waiting on hold to learn what step comes next.
A secure account dashboard reinforces that visibility. Once a borrower creates an account, the dashboard displays the current status of the mortgage application alongside the next required action. This structure removes the uncertainty that once defined paper-based lending.
What happens after submitting an online mortgage application?
Submission triggers a connection to a loan specialist who reviews the borrower’s goals and matches them to a residential or commercial program. The process starts quickly and stays secure throughout. Borrowers share only the information needed to begin eligibility review, not a full paper file upfront.
Can borrowers manage their loan without calling a representative?
Self-service functionality has become standard across modern loan servicing platforms. Borrowers increasingly check balances, make payments, download statements, and exchange documents directly through the portal. Phone calls become optional rather than required.
A complete online application portal typically includes:
- Secure identity verification and encrypted document upload
- A live dashboard tracking status and next steps
- Direct messaging with a loan specialist
- Self-service statement and payment access
- Mobile-friendly access for updates on the go
Borrowers evaluating lenders should treat portal functionality as a core decision factor, not an afterthought. Those ready to compare options can apply for a mortgage online and begin eligibility review the same day they submit their information.
What Documents Do You Need to Apply?
Lenders need proof of identity, income, and financial standing before issuing a decision. Every applicant, along with any co-borrower such as a spouse or partner, must supply this information directly to the lender. No file moves forward without it.
Documentation requirements fall into three core categories:
- Income and employment history: pay stubs, tax returns, or employer verification confirming steady earnings
- Creditworthiness records: credit history and outstanding debt obligations that shape loan terms
- Overall financial situation: bank statements, asset records, and liabilities that paint a full financial picture
Borrowers with nontraditional income streams face a different documentation path. Self-employed applicants and small business owners often cannot rely on standard pay stubs alone. Munshi Capital Inc. addresses this gap through bank statement loans, one of several programs built around each client’s unique financial picture rather than a one-size-fits-all checklist.
Do document requirements change for an online application?
The core documents stay the same whether a borrower applies in person or through a digital mortgage portal. What changes is the collection method: scanned uploads and secure data pulls replace paper handoffs. Specific features available within an online application portal vary by loan type. A home mortgage consultant clarifies exactly which tools apply to a given loan before documents get uploaded.
What happens after documents are submitted?
Underwriters review the submitted files for accuracy and completeness. Gaps trigger follow-up requests rather than automatic denial. Borrowers ready to move forward can request a direct cash offer or request your property assessment to see how their documentation lines up with available programs.
How Does the Process Move From Application to Closing?
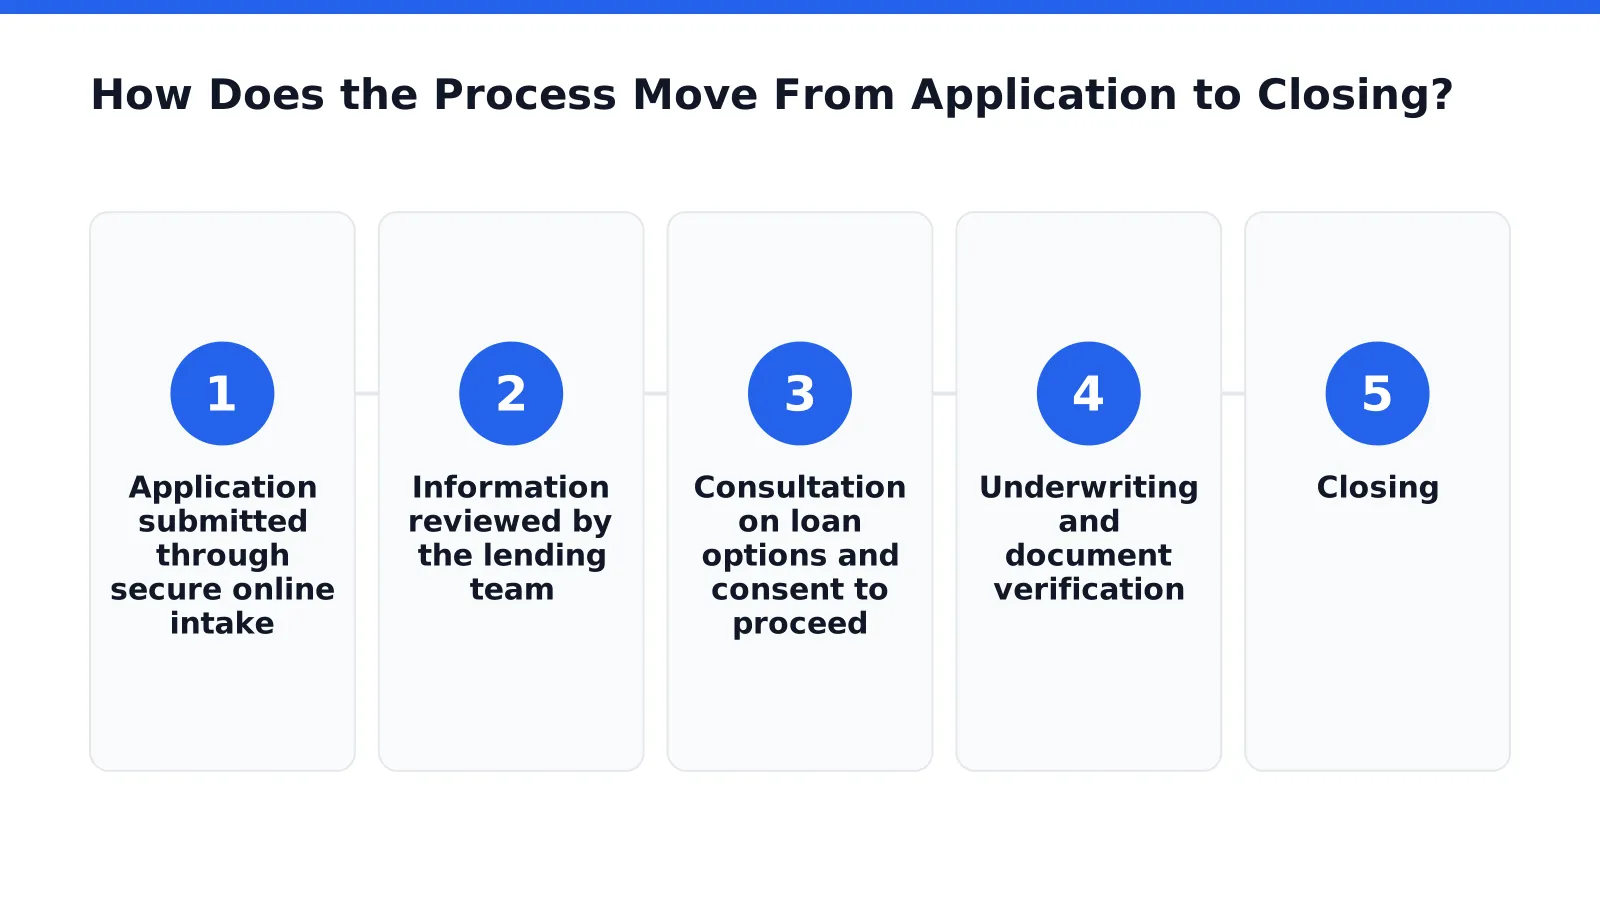
Five stages carry a borrower from first submission to signed documents: application, review, consultation, underwriting, and closing. Munshi Capital Inc. guides borrowers through every step with clarity and speed, removing confusing jargon and hidden surprises from a process that often overwhelms first-time buyers.
Submission starts the clock. A borrower completes the online application portal, providing income, asset, and property details without a single phone call required. Because the system stores documents securely, applicants avoid repeated paperwork requests later in the process.
Review follows next. After the lending team examines the submitted information, a representative reaches out to discuss loan options and confirm the borrower’s readiness to move forward. This conversation shapes which programs fit the borrower’s actual financial picture, rather than a generic default product.
What Happens After the Initial Consultation?
Consent triggers formal processing. Once a borrower agrees to proceed, the file advances into underwriting, where documentation gets verified against the stated loan terms. Munshi Capital’s personalized guidance keeps borrowers across the country informed at each checkpoint, so nothing moves without the applicant’s knowledge.
Is Applying Online Actually Faster Than In Person?
Speed comes from structure, not shortcuts. A borrower who can apply for a mortgage online skips scheduling delays tied to branch visits and paper intake. The digital mortgage portal consolidates status updates, so borrowers track progress instead of guessing where their file stands.
The stages break down as follows:
- Application submitted through secure online intake
- Information reviewed by the lending team
- Consultation on loan options and consent to proceed
- Underwriting and document verification
- Closing
This structure reflects an approach rooted in clarity, honesty, and a service-driven ethos, built so borrowers reach closing with full visibility and no surprises waiting at the table.
Which Loan Programs Fit Your Financial Picture?
Financial circumstances vary widely, so Munshi Capital Inc. structures its loan offerings around that reality rather than a single standard borrower profile. First-time buyers, seasoned investors, and business owners each carry different income documentation, credit histories, and property goals. A lending program built for one rarely fits another.
Investors chasing rental income or property acquisitions need financing that looks past a traditional paycheck. Munshi Capital Inc. addresses this gap directly through specialized products, including DSCR loans, which evaluate a property’s cash flow rather than personal income, and hard money loans, designed for short-term, asset-based borrowing. These options give investors a path to financing that conventional underwriting often blocks.
What if income documentation doesn’t fit the standard mold?
Borrowers with nontraditional income, self-employment earnings, or multiple revenue streams often struggle with rigid underwriting rules elsewhere. Munshi Capital Inc.’s broader suite of residential. Commercial programs exists precisely to address those gaps, matching loan structure to the borrower’s actual financial picture instead of forcing a mismatch.
Does location change which loan program makes sense?
Yes. Local market conditions shape rates, loan limits, and program availability. Munshi Capital Inc. lets borrowers search by city to review local loan programs, rates, and market insights tailored to where they’re buying, turning a national lending menu into a localized decision.
Choosing the right program comes down to three questions:
- What does the income documentation look like, traditional or nontraditional?
- Is the property for personal residence or investment cash flow?
- Does the local market carry specific rate or program considerations?
Every path runs through the same foundation: transparent, borrower-first guidance built on trust, not guesswork.
FAQ
Is applying for a mortgage online faster than traditional methods?
Yes, Munshi Capital’s digital portal gathers financial documents electronically with borrower permission, eliminating mailed or faxed paperwork delays and speeding up the preapproval timeline.
What should borrowers prepare before starting an online application?
Borrowers should have income details, employment history, and creditworthiness documentation ready, which shortens the time between submitting an application and receiving preapproval.
How does the portal keep borrowers informed throughout the loan process?
A custom dashboard tracks real-time application status, next steps, and document requirements, giving borrowers full visibility from initial eligibility check through closing.
Conclusion
In closing, an effective online mortgage application portal represents far more than a digital convenience, it embodies the commitment to transparency and accessibility that defines modern lending. By consolidating documentation, streamlining underwriting, and providing real-time visibility into loan status, such platforms eliminate friction from the borrowing process while maintaining the personalized guidance borrowers require. The integration of advanced technology with dedicated loan specialist support ensures that whether you are a first-time homebuyer or seasoned investor, you navigate your financing journey with clarity, confidence, and dependable service from application through closing.
Leave a Reply