Hard money loans give investors in Investors short-term, asset-based financing secured by real estate, issued by private lenders rather than banks. Munshi Capital Inc., based in Walnut Creek, CA, structures these loans around property value and investment timelines, delivering faster approvals, flexible underwriting, and funding for acquisitions, rehabs, or bridge financing needs.
What Is a Hard Money Loan for Investors?
A hard money loan is a short-term, asset-based loan secured by real estate, issued by private lenders rather than traditional banks. **Hard Money Loans Explained: Key Features in Real Estate Investors** for property investors comes down to one core idea: the asset backs the loan, not the borrower’s credit history. Investors who miss a narrow buying window because conventional financing moves too slowly lose deals, equity, and negotiating leverage to faster-moving bidders.
Hard money lenders weigh the merits of the investment property itself, using it as collateral instead of scoring the applicant’s personal finances. This structure sits at the center of the **Hard Money Loans for Real Estate Investors** that draw fund managers and seasoned investors toward competitive acquisitions.
Who Actually Lends Hard Money?
Banks do not originate these loans. Funding instead comes from:
- Individual investors
- Investing groups
- Financing companies
Why Do Investors Choose Hard Money Over a Traditional Mortgage?
Speed separates hard money from conventional underwriting. A traditional mortgage can take weeks to process. Hard money loans deliver fast funding by focusing on the property’s value rather than the borrower’s personal finances. For time-sensitive real estate investment financing, that gap often decides whether an offer gets accepted or lost to a competing buyer.
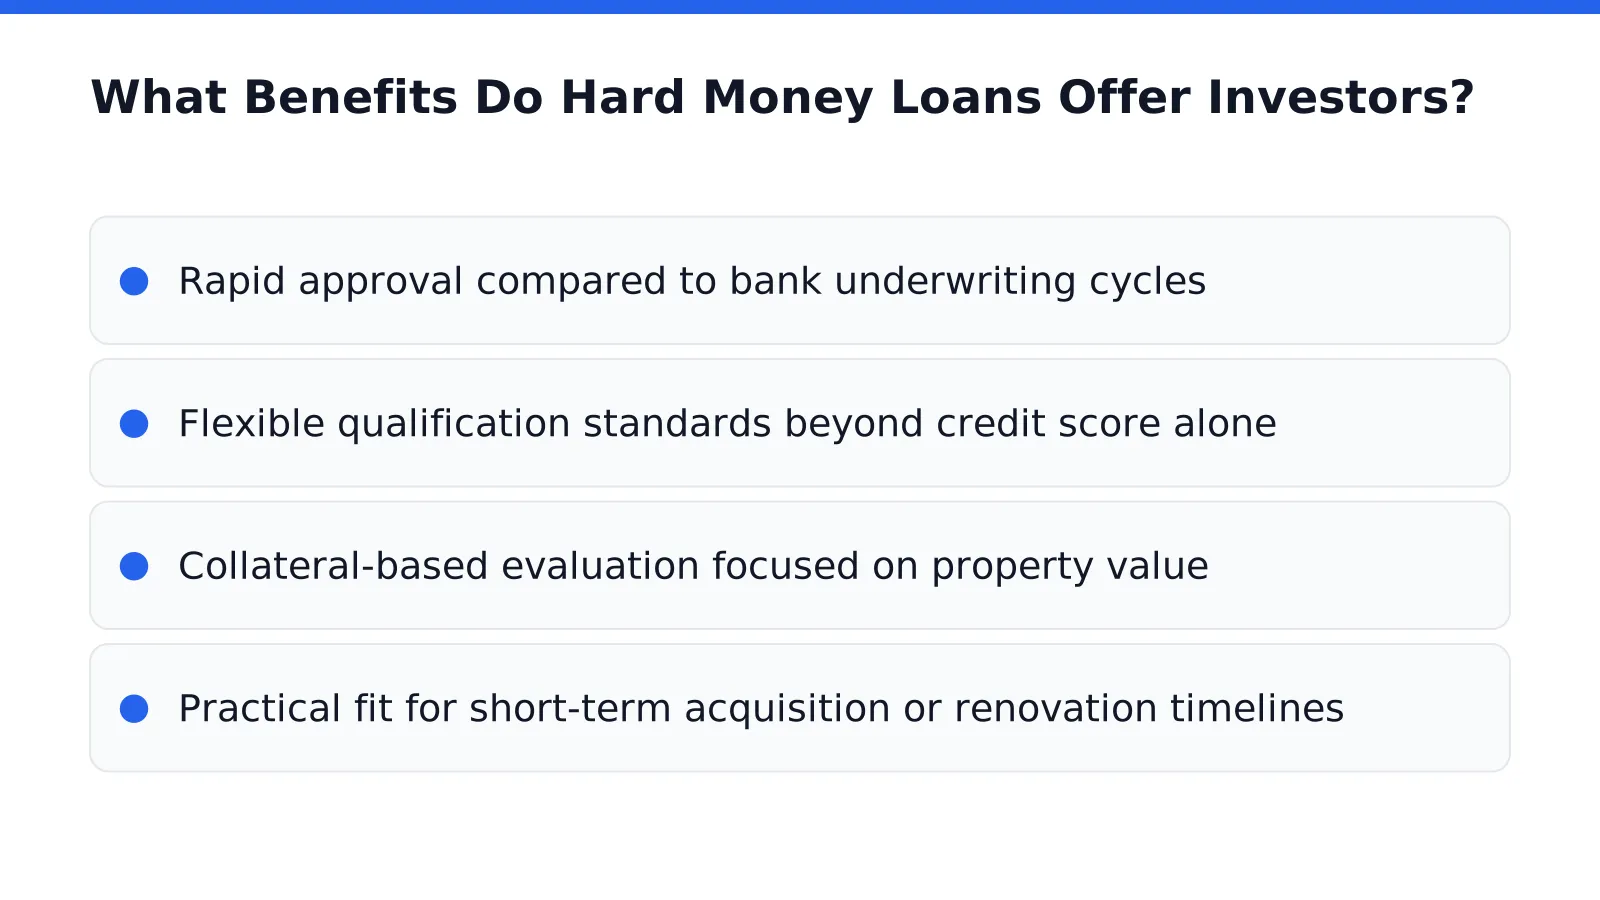
What Benefits Do Hard Money Loans Offer Investors?
Speed defines the core advantage. Hard money loans explained simply: these are asset-based financing tools that approve and fund faster than conventional mortgages, often clearing underwriting hurdles that stall bank loans for weeks.
Investors pursuing competitive deals rarely have weeks to spare. Faster approval timelines and more flexible qualification standards give buyers a real edge when a seller wants a quick, certain close. Traditional lenders scrutinize income history and credit depth. Hard money lenders weigh the property’s value instead, which shortens the path from offer to funding.
This structure explains the primary hard money loan benefits for active market participants:
- Rapid approval compared to bank underwriting cycles
- Flexible qualification standards beyond credit score alone
- Collateral-based evaluation focused on property value
- Practical fit for short-term acquisition or renovation timelines
Who Actually Uses Hard Money Financing?
Real estate investors use these loans most often for property investment purchases and situations where conventional financing falls short. For seasoned investors and fund managers running tight acquisition timelines, this type of real estate investment financing fills a specific gap: speed and flexibility, not long-term cost efficiency.
Property sellers facing similar time pressure have options too. Sellers ready to move can request a direct cash offer from Munshi Capital Inc., which provides fast, fair cash offers for commercial properties, helping owners maximize net proceeds while avoiding costly repairs and delays.
What Risks Should Investors Weigh First?
Higher interest rates, compressed repayment windows, and elevated foreclosure exposure top the list of risks tied to hard money financing. Fund managers and first-time buyers alike face this trade-off when speed outweighs cost. **DSCR Loans for Real Estate Investors: Qualifying Criteria Explained** structured this way sacrifices affordability for access, a trade-off that deserves scrutiny before signing anything.
Munshi Capital Inc. frames this reality directly. Clients receive a customer-centric approach built on clear, practical financial solutions for real estate transactions, not vague promises. Investors weighing a specific property can request your property assessment to clarify how asset value supports proposed loan terms.
Hard money lenders rely on asset-based underwriting rather than traditional income verification. The property itself, not the borrower’s credit history, becomes the primary qualification factor and the collateral securing the loan. This speeds approval but shifts risk squarely onto the investor if a deal underperforms.
Key risks to weigh:
- Interest rates that run well above conventional mortgage rates
- Repayment periods measured in months, not years
- Foreclosure risk if the exit strategy stalls
- Collateral exposure tied directly to the property’s value
Are hard money loan benefits worth the added risk?
Seasoned investors weigh hard money loan benefits, such as speed and flexible qualification, against shorter timelines and foreclosure exposure. Costs and risks demand careful evaluation before committing to any deal. Hard Money Loans Explained in plain terms: fast capital comes with a shorter runway and less room for error.
Conclusion
In closing, hard money loans represent a strategic financing mechanism for investors seeking expedited capital deployment and flexible underwriting criteria. The accelerated funding timelines, asset-based lending structure, and reduced documentation requirements address critical gaps in traditional mortgage markets, enabling investors to capitalize on time-sensitive opportunities. By understanding these key features and evaluating alignment with your investment objectives, you position yourself to make informed decisions that optimize your real estate strategy and enhance your competitive positioning in dynamic market conditions.
Leave a Reply