Homeownership tax basics center on deductions for mortgage interest. Property tax payments, available to itemizing filers under IRS guidance (Tax Tip 2024-51). Homeowners exclude capital gains from a home sale up to IRS limits. First-time buyers and investors benefit from understanding these rules before closing, since they directly affect annual tax liability and long-term equity returns.
Key Takeaways
- Homeowners deduct mortgage interest and property tax payments from federal taxable income when itemizing deductions.
- The mortgage interest deduction applies to loans used to buy, build, or substantially improve your home.
- Imputed rental income from homeownership remains untaxed, providing significant financial advantage to property owners.
- Multiple tax breaks exist for homeowners; review IRS guidance to confirm eligibility for each deduction.
Why Do Homeowners Get Tax Breaks?
Federal tax policy rewards homeownership because owning a primary residence carries real financial weight. Congress built in relief to soften that burden. Tax benefits exist specifically to help offset the costs that come with buying, financing, and maintaining a home.
The core principle behind these breaks is simple. Rarely explained plainly: the value a homeowner gets from living in their own property, known as imputed rental income, is never taxed. A renter’s landlord pays tax on rental income. A homeowner living in their own house pays no such tax on that equivalent benefit. This single distinction underpins most of the mortgage tax deductions and related homeowner benefits available today.
What Costs Do These Tax Breaks Actually Offset?
Homeownership tax benefits target the real, recurring expenses buyers take on. Three categories matter most for new owners and investors alike:
- Property taxes paid to state and local governments
- Mortgage interest paid on home loans
- Capital gains realized when a home is eventually sold
Each category reduces taxable income or shelters gains, directly lowering what a homeowner owes.
Who Benefits Most From These Deductions?
First-time buyers and investors both gain ground here, though differently. A first-time buyer offsets the early years of a mortgage, when interest payments run highest. An investor building a portfolio benefits from the capital gains treatment on eventual sales.
Navigating which deductions apply, and when, depends heavily on loan structure. Munshi Capital Inc. offers residential programs, including FHA, VA, USDA, and bank statement loans, built around each borrower’s actual financial picture. That structure, paired with a transparency-first approach, gives borrowers clarity on costs and benefits from application through closing, rather than confusion after the fact.
What Mortgage Tax Deductions Can You Claim?
Mortgage tax deductions reduce taxable income for homeowners who pay interest on loans used to purchase, build, or substantially improve a primary residence. The most significant of these is the mortgage interest deduction, which applies to the interest portion of monthly loan payments rather than the principal. Early in a loan’s life, interest makes up the bulk of each payment, so this deduction carries real weight for new buyers.
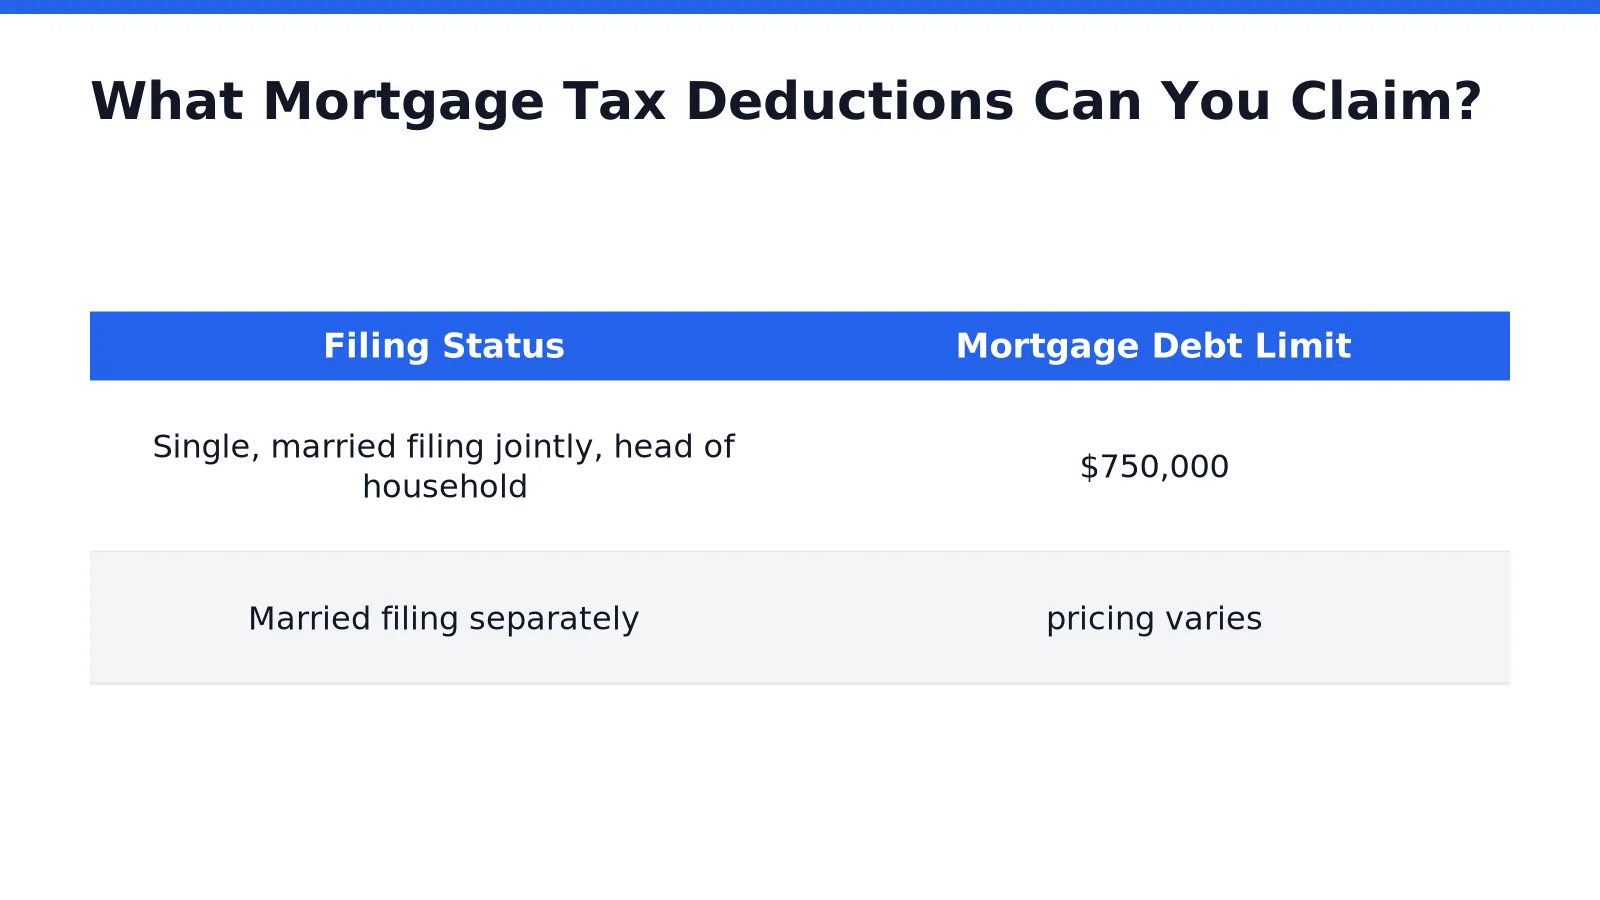
Limits on mortgage interest deductions vary based on specific loan circumstances and property values. Deductions cover interest on only the first $750,000 of mortgage debt for most filers; married individuals filing separately face a lower cap, with the exact threshold varying by filing circumstances. Borrowers who exceed those thresholds still owe tax on interest paid above the limit. Loan structure deserves attention before closing.
How does loan size affect the deduction?
Loan size determines how much interest qualifies. A mortgage under $750,000 allows the full interest amount to be deducted, while balances above that figure only partially qualify. Structuring a purchase or refinance with this ceiling in mind protects more of a homeowner’s deduction.
Who benefits most from this deduction?
First-time buyers and investors carrying larger loan balances typically see the greatest tax impact, since interest dominates early payments. Munshi Capital Inc. specializes in mortgage financing built for this range of borrowers, from first-time homebuyers to seasoned investors pursuing deduction-eligible loans. Personalized guidance from the Munshi Capital team helps borrowers understand how loan terms interact with filing outcomes. The financing decision and the tax decision work together rather than against each other.
How Do Property Taxes Affect Your Return?
Property taxes reduce taxable income directly, but only within strict limits. State and local real estate taxes qualify as a deduction, capped at $10,000 for the combined total of property and state income taxes claimed. That ceiling applies regardless of how high actual tax bills run in a given county or state.
Claiming this benefit requires a specific filing choice. Homeowners must itemize deductions on their federal return to write off property taxes and mortgage interest together. Taking the standard deduction instead forfeits both benefits, even if the homeowner paid thousands in local taxes that year.
Is Itemizing Always Worth It?
Not for every household. Itemizing only produces savings when combined deductions, property taxes, mortgage interest, and other eligible expenses, exceed the standard deduction amount. First-time buyers with smaller mortgage balances sometimes find the standard deduction delivers a better outcome.
Review of the tax math matters before filing season arrives. Here is a quick way to frame the decision:
- Compare totals: Add projected property taxes, mortgage tax deductions, and other itemized expenses against the standard deduction.
- Track the cap: Remember the $10,000 limit applies to combined state and local taxes, not property taxes alone.
- Reassess annually: Property tax bills and mortgage interest change year to year, so the better option can shift.
Munshi Capital gives borrowers full visibility into loan status, including how property-related costs factor into monthly payments. That transparency helps new homeowners anticipate their tax position well before filing season, rather than discovering surprises in April. Loan specialists walk clients through every property-related cost tied to their financing, pairing a fast process with hands-on guidance that keeps tax planning grounded in real numbers.
Can You Avoid Capital Gains Tax Entirely?
Full avoidance is rare. Homeowners may exclude a portion of the gain realized from selling a primary home, up to a limit set by the tax code. That exclusion does not erase every dollar of profit from taxation. It simply shields a defined portion, leaving any remaining gain exposed.
The tax code offers more than one lever here. Beyond the familiar deductions tied to mortgage interest. Local assessments, the code provides several benefits for people who own their homes, not deductions alone. Selling a primary residence triggers a separate set of rules around capital gains, distinct from the annual deductions claimed while living in the home.
Does Selling an Investment Property Work the Same Way?
Not quite. The exclusion tied to a primary home does not automatically extend to rental or investment properties. Investors who later sell a property acquired through financing need a lender that understands both sides of the transaction.
This is where loan structure matters before the sale ever happens. Munshi Capital’s DSCR and hard money loan products support investors managing properties that may eventually trigger capital gains considerations at sale.
Who Benefits Most From the Exclusion?
Owner-occupants selling a long-held primary residence see the clearest advantage. Investors, by contrast, face a narrower path and often need planning well before closing.
A few points worth remembering:
- The exclusion applies to a primary home, not every property owned.
- Limits cap how much gain stays untaxed.
- Investment property sales generally fall outside the exclusion.
Munshi Capital’s commitment to integrity and a broad range of loan products makes it a trusted choice for investors planning a future property sale.
How Should You Plan For These Benefits?
Planning starts with a clear picture of costs before any loan closes. Munshi Capital Inc. walks borrowers through a straightforward application, underwriting, and closing process. Homeowners understand mortgage tax deductions and other costs before committing to a loan. That clarity matters most at tax time, when overlooked details on property taxes or capital gains can turn a planned savings into an unexpected bill.
When Should A Homeowner Review Tax Strategy With A Lender?
Reviewing strategy early, before signing loan documents, gives homeowners room to adjust. Munshi Capital builds financing around each borrower’s goals, not a generic template, and offers clear answers through every loan program available.
What Makes A Lender Reliable For Tax-Season Planning?
Reliability comes from consistency, not promises made once and forgotten. Munshi Capital’s approach stays rooted in clarity and honesty throughout the loan journey, which builds the kind of trust borrowers need heading into tax season.
A practical planning sequence looks like this:
- Confirm projected mortgage interest and tax deductions with a loan specialist.
- Review property tax obligations tied to the purchase price and location.
- Discuss capital gains exposure for any future sale, especially for investment property.
Investors weighing a sale can request a direct cash offer. Current owners assessing their tax position can request your property assessment to plan with confidence.
FAQ
What expenses do homeowner tax breaks offset?
Tax breaks target property taxes paid to state and local governments, mortgage interest paid on home loans, and capital gains realized when a home sells, each lowering taxable income or sheltering gains.
Why don’t homeowners pay tax on living in their own home?
The value homeowners get from occupying their own property, called imputed rental income, stays untaxed, unlike a landlord who pays tax on rental income collected from tenants.
How does Munshi Capital Inc. support borrowers navigating these deductions?
Munshi Capital Inc. offers FHA, VA, USDA, and bank statement loans tailored to each borrower’s financial picture, delivering transparency from application through closing so costs and benefits stay clear.
Conclusion
In closing, understanding the tax benefits of homeownership positions you to make informed financial decisions that extend far beyond the initial purchase. These advantages, from mortgage interest deductions to capital gains exclusions, represent tangible value that strengthens your long-term wealth strategy. Securing the right financing through a trusted lender ensures you maximize these benefits from day one, with transparent guidance and dependable service supporting your homeownership journey every step of the way.
Leave a Reply