Effective investor financing strategies combine conventional loans, DSCR products, and commercial mortgages matched to property cash flow rather than personal income alone. Munshi Capital Inc. structures financing around income and value for one- to four-unit. Multi-unit properties, with conventional purchases starting near 15% down for qualifying investors nationwide.
Key Takeaways
- Conventional investment loans finance one- to four-unit properties with down payments starting at 15% for single units.
- Munshi Capital’s DSCR and hard money loans provide specialized financing options designed specifically for real estate investors.
- Investment property underwriting evaluates credit, income, assets, debts, reserves, and eligible rental income for comprehensive borrower assessment.
- Munshi Capital delivers transparent pre-approvals and full loan status visibility throughout the entire financing process.
Why do investment property loans differ from home loans?
Investment property loans impose stricter qualifying standards than standard home loans because lenders face greater risk on non-owner-occupied real estate. Government-backed programs reserve their most forgiving terms for primary residences, pushing property investors toward conventional and specialized financing instead. Building smart investor financing strategies starts with understanding this split before shopping for a loan.
Standard FHA and VA loans work only for primary residences. An investor cannot use either program to buy a rental property outright. One narrow exception applies: an investor who purchases a multiunit home and occupies one unit as a primary residence may still qualify, while renting out the remaining units.
Can investors use FHA or VA loans for rental property?
Not for a straight rental purchase. FHA and VA financing targets owner-occupants, not landlords buying income property outright. The workaround applies only to multiunit purchases where the buyer lives in one unit and rents the rest.
For investors who won’t occupy the property, conventional real estate investor loans fill the gap. A conventional loan can finance a qualifying one- to four-unit investment property, with underwriting weighing credit history, income, assets, debts, down payment, cash reserves, and eligible rental income together, not just a borrower’s paycheck.
How much down payment does an investment property loan require?
Down payments on investment property loans start higher than on owner-occupied purchases. A one-unit investment purchase may begin around 15% down, while two- to four-unit properties generally require more.
Sound investment property finance depends on matching the loan type to the asset and the borrower’s complete financial picture. Munshi Capital Inc. structures residential and commercial loan programs around that picture, serving first-time buyers and seasoned investors alike across the country.
Which loan programs fit your investor financing strategy?
Loan selection depends on property type, timeline, and the strength of an investor’s financial documentation. Munshi Capital Inc. structures investor financing strategies around specialized products, including DSCR and hard money loans, designed for buyers who need financing built around the deal rather than a traditional W-2 paycheck. These tools sit alongside residential programs like FHA, VA, USDA, and bank statement loans, giving borrowers a range of paths from a first purchase to a growing multi-property portfolio.
Building a real estate portfolio often feels exciting and overwhelming at once. Returns need weighing against renovation costs, market timing, and financing terms, and juggling all three without a clear lending plan creates unnecessary risk. Matching the loan to the strategy removes much of that uncertainty.
What loan types work best for property investors?
Several real estate investor loans serve different scenarios, and no single product fits every deal:
- DSCR loans: qualify based on a property’s rental income rather than personal income, useful for investors with complex tax returns.
- Hard money loans: short-term financing for fix-and-flip projects or properties that need repairs before qualifying for conventional terms.
- FHA, VA, and USDA loans: government-backed programs built for owner-occupants, often used by investors purchasing a multi-unit property to occupy one unit.
- Bank statement loans: designed for self-employed investors whose tax returns understate true cash flow.
How should an investor choose between these options?
Choosing the right program starts with understanding how each one works. An investor who studies the mechanics of investment property finance can work with a lender to select the option matching goals, timeline, and property type, whether that means a single-family rental, a small multi-family building, or a commercial acquisition. Property managers juggling multiple assets benefit from comparing loan structures side by side before committing to one lender or product. For California investors and those buying nationwide, the right fit often comes down to documentation strength and how quickly the deal needs to close.
How do DSCR and hard money loans work for investors?
DSCR loans qualify investors using property cash flow instead of personal income documentation. Hard money loans supply short-term capital secured directly by the property, often closing faster than conventional financing. Munshi Capital Inc. positions both products among its investor-focused financing options, designed to serve borrowers whose goals do not fit a standard mortgage profile.
A property loan functions as the backbone of any investment property finance plan, giving investors flexibility, funding capacity, and a range of repayment structures. Securing funds for acquisition or refinancing sits at the center of shaping a workable investment strategy. Without the right loan structure, a promising property can stall before it ever generates income.
What qualifies a property for a DSCR loan?
A DSCR loan evaluates whether rental income covers the property’s debt obligations, shifting the underwriting focus away from a borrower’s W-2 earnings. This structure suits self-employed investors and those holding multiple properties whose personal tax returns don’t reflect true cash flow. Property performance, not payroll history, drives approval.
When does a hard money loan make sense for investors?
Hard money financing fits time-sensitive purchases, renovation projects, or deals where speed outweighs the cost of a longer-term rate. Investors use these loans as bridge capital while repositioning or refinancing a property into permanent financing.
Key distinctions between the two products include:
- DSCR loans: underwritten on property income, suited for long-term rental holds.
- Hard money loans: underwritten on the asset’s value, suited for short-term, time-driven projects.
Larger acquisitions, including multifamily and mixed-use buildings, often fall under commercial loan programs structured around the property’s income and value, with terms tailored to the investment strategy. This approach gives real estate investor loans a framework flexible enough to support both single-asset purchases and growing portfolios. Matching the loan to the strategy, rather than forcing the strategy to fit the loan, remains the defining principle behind sound investor financing strategies.
What should you know about commercial financing for larger deals?
Larger commercial transactions demand financing built around a property’s income and asset value, not a single owner’s paycheck. Munshi Capital Inc. provides commercial mortgage financing for business owners and real estate investors across the USA, structuring each loan around the asset being purchased, refinanced, or expanded.
Scale matters here. Sound investor financing strategies for sizable deals start with matching the property type to the right loan structure. Commercial underwriting weighs cash flow and collateral value rather than personal W-2 income alone.
What property types qualify for larger commercial loans?
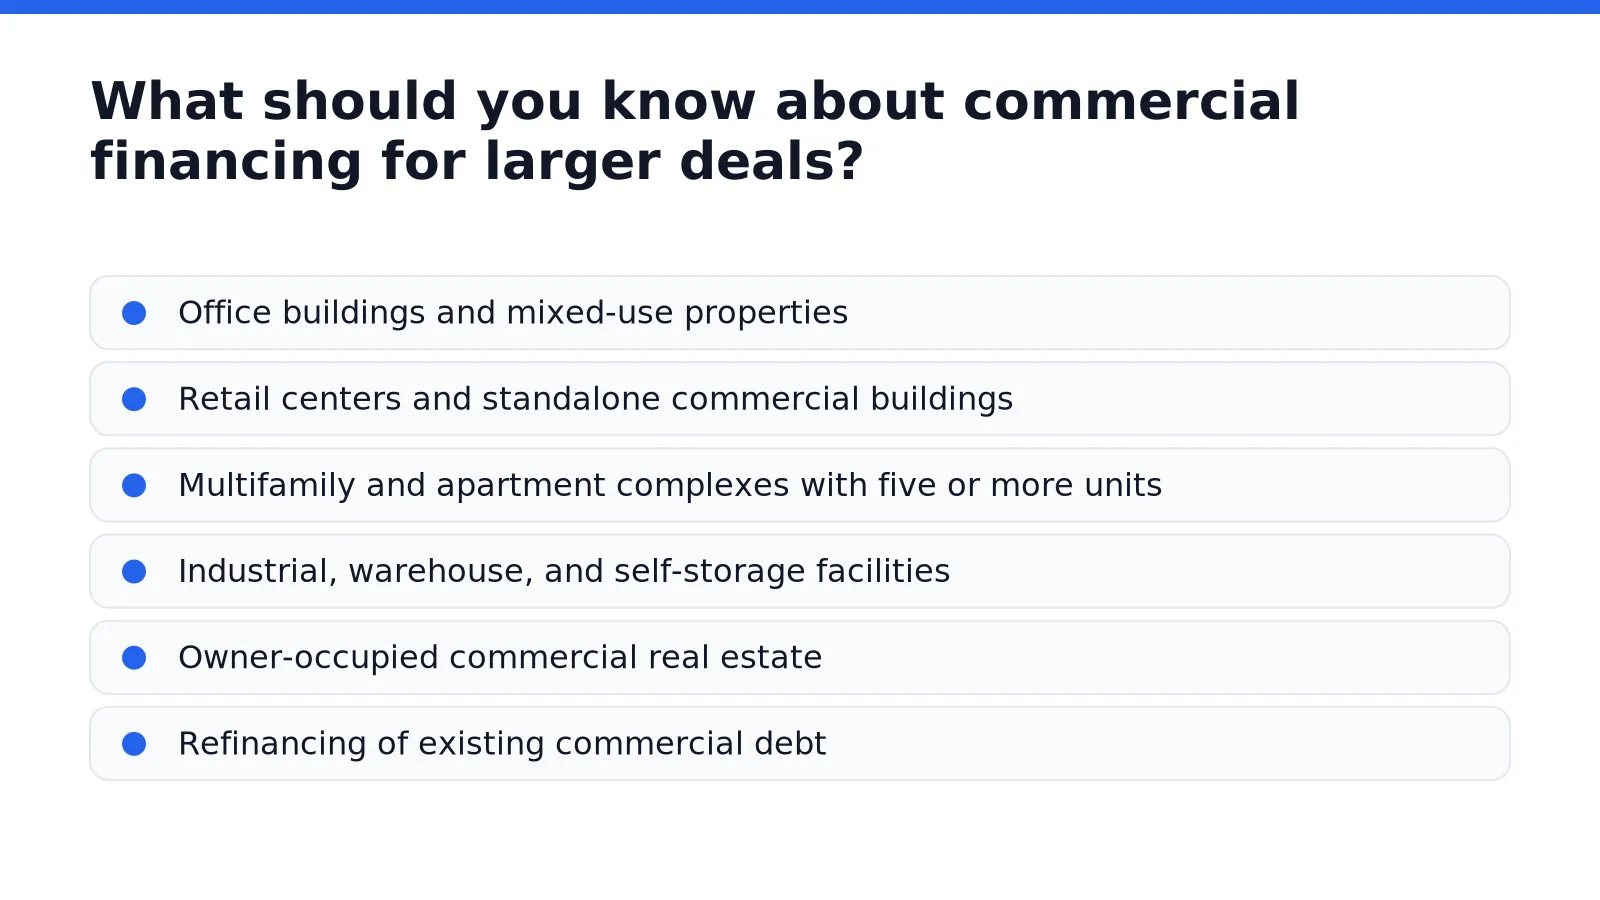
Commercial programs extend across a wide range of asset classes, giving investors flexibility as portfolios grow. Eligible property types include:
- Office buildings and mixed-use properties
- Retail centers and standalone commercial buildings
- Multifamily and apartment complexes with five or more units
- Industrial, warehouse, and self-storage facilities
- Owner-occupied commercial real estate
- Refinancing of existing commercial debt
What loan amounts and terms apply to commercial deals?
Commercial loan amounts span from pricing varies million or more, supporting both modest acquisitions and institutional-scale purchases. Underwriting rests on cash flow and asset value, a structure that supports durable real estate investor loans for growing portfolios.
For business owners who need financing tied to operations rather than real estate alone, SBA 7(a) and 504 programs offer another path. Munshi Capital Inc. matches each client with the program, term, and rate structure suited to their goals, rounding out a broader approach to investment property finance for owners scaling beyond a single asset.
How does Munshi Capital make closing fast and transparent?
Closing moves quickly because borrowers follow a defined application, underwriting, and funding sequence with no hidden steps. Clear documentation requirements and consistent communication remove guesswork at every stage. For real estate investors building investor-financing-strategies-030, predictability matters as much as speed.
Technology drives the pace. Loan specialists pair automated underwriting tools with direct, hands-on guidance. Files move efficiently without losing the personal contact investors need when questions arise mid-deal. That combination supports real-estate-investor-loans-030 across single-family, multi-family, and commercial transactions alike.
What makes pre-approval fast?
Pre-approval happens quickly because digital systems verify income, assets, and credit data in parallel rather than in sequence. Investors gain early clarity on buying power before competing for a property, which matters in fast-moving markets.
Can investors track their loan status in real time?
Full visibility into loan status runs from application through funding. Borrowers see exactly where their file stands at each milestone, eliminating the uncertainty that typically stalls traditional lending.
This structure supports sound investment-property-finance-030 decisions across a wide range of programs. The approach rests on three pillars:
- Defined, step-by-step underwriting with no surprise conditions
- Technology-driven processing paired with direct specialist access
- Transparent status updates from pre-approval to close
Integrity and personalized service remain the foundation, making the process a dependable choice for investors nationwide.
FAQ
Why do investment property loans differ from home loans?
Investment property loans carry stricter qualifying standards because lenders face greater risk on non-owner-occupied real estate. Government-backed programs reserve their most forgiving terms for primary residences, pushing investors toward conventional and specialized financing instead.
FHA and VA financing targets owner-occupants, not landlords buying straight rental property. The one exception applies to multiunit purchases where the buyer occupies one unit and rents out the remaining units.
A one-unit investment purchase starts around 15% down for qualifying investors. Two- to four-unit investment properties generally require a higher down payment than single-unit properties.
Conclusion
In closing, successful real estate investment financing requires a strategic approach grounded in transparent partnerships and tailored loan solutions. Munshi Capital Inc. delivers the specialized programs, including DSCR and hard money loans, that align with investor objectives, coupled with straightforward underwriting processes that eliminate uncertainty. By prioritizing clarity and personalized guidance throughout the lending journey, investors gain the confidence and dependable support necessary to execute their acquisition and portfolio expansion strategies with precision and integrity.
Leave a Reply