VA loans give eligible active-duty members, veterans, and surviving spouses 100% financing with no down payment and competitive interest rates. Those who exhaust their VA entitlement often qualify for alternative programs, such as a Navy Federal Military Choice Loan. Comparing interest rates, mortgage insurance, down payment requirements, and eligibility rules determines the best fit for military families.
Key Takeaways
- VA loans offer 100% financing with zero down payment for eligible military members and veterans.
- Military families access specialized mortgage programs designed specifically for their unique financial situations and service backgrounds.
- Munshi Capital Inc. provides transparent guidance through VA loan options with clear answers and dependable service.
- Our loan specialists deliver personalized support helping military families secure the right financing confidently nationwide.
What Makes VA Loans a Smart Choice?
VA loans deliver 100% financing with no down payment required, paired with low interest rates for eligible servicemembers and veterans. These terms set VA financing apart from most conventional residential loan products. Military borrowers avoid the years of saving that typically precede a home purchase.
Monthly costs stay lower too. VA loans carry no mortgage insurance requirement, a feature that directly reduces the monthly housing payment compared to loans requiring private mortgage insurance. That savings compounds over the life of the loan, freeing up income for other financial priorities.
Interest rates on VA loans also tend to run below conventional rates, and the resulting monthly payments reflect that advantage. For a military family budgeting around deployments, relocations, or a spouse’s career changes, predictable and lower payments matter.
Who Qualifies for a VA Loan?
Eligibility centers on service history rather than income brackets alone. Active-duty members, veterans, National Guard and Reserve personnel, and certain surviving spouses typically qualify. Specific service-length and discharge requirements apply. A lender specializing in military lending can confirm eligibility quickly.
How Does Munshi Capital Fit Into This Picture?
Munshi Capital Inc. includes VA loans within a comprehensive suite of residential loan programs built around each client’s financial picture. This complete military-veteran-mortgage-guide-029 approach means a veteran isn’t boxed into one product. Alternatives exist if VA financing doesn’t fit a particular situation.
For military families exploring va-loan-resources-029 and broader veteran-home-financing-029 options, understanding these distinctions prevents overpaying on avoidable costs.
Who Qualifies for VA Home Loan Benefits?
Three groups qualify for VA home loan benefits: veterans, active-duty servicemembers, and eligible surviving spouses. The Veterans Benefits Administration confirms this guaranty benefit exists specifically to help these groups achieve homeownership, alongside other housing-related programs. Eligibility hinges on service history, discharge status, and length of duty, so requirements vary by individual circumstance.
Many service members assume this benefit expires after one use. That assumption costs them options. A VA home loan actually functions as a lifetime benefit, available for future purchases as long as eligibility requirements continue to be met. A borrower who used a VA loan a decade ago may still qualify today.
Can a veteran use a VA loan more than once?
Yes. The lifetime structure of this benefit means eligible veterans and servicemembers can tap it again for a future home purchase, refinance, or relocation. Reuse depends on meeting current eligibility standards at the time of the new loan, not just the original qualification.
Who else besides veterans can qualify?
Eligible surviving spouses and active-duty personnel also qualify, not just discharged veterans. This military-veteran-mortgage-guide-029 approach to eligibility reflects the benefit’s design: supporting families connected to military service, not only those who have left it.
Munshi Capital Inc. treats every borrower’s service record as unique rather than running through a generic checklist. The team’s va-loan-resources-029 guidance accounts for deployment history, discharge classification, and spousal eligibility questions that national lenders often overlook. That personalized approach to veteran-home-financing-029 helps borrowers nationwide secure financing structured around their actual service background. Financial profile, not a one-size-fits-all formula.
What If You’ve Already Used Your Benefit?
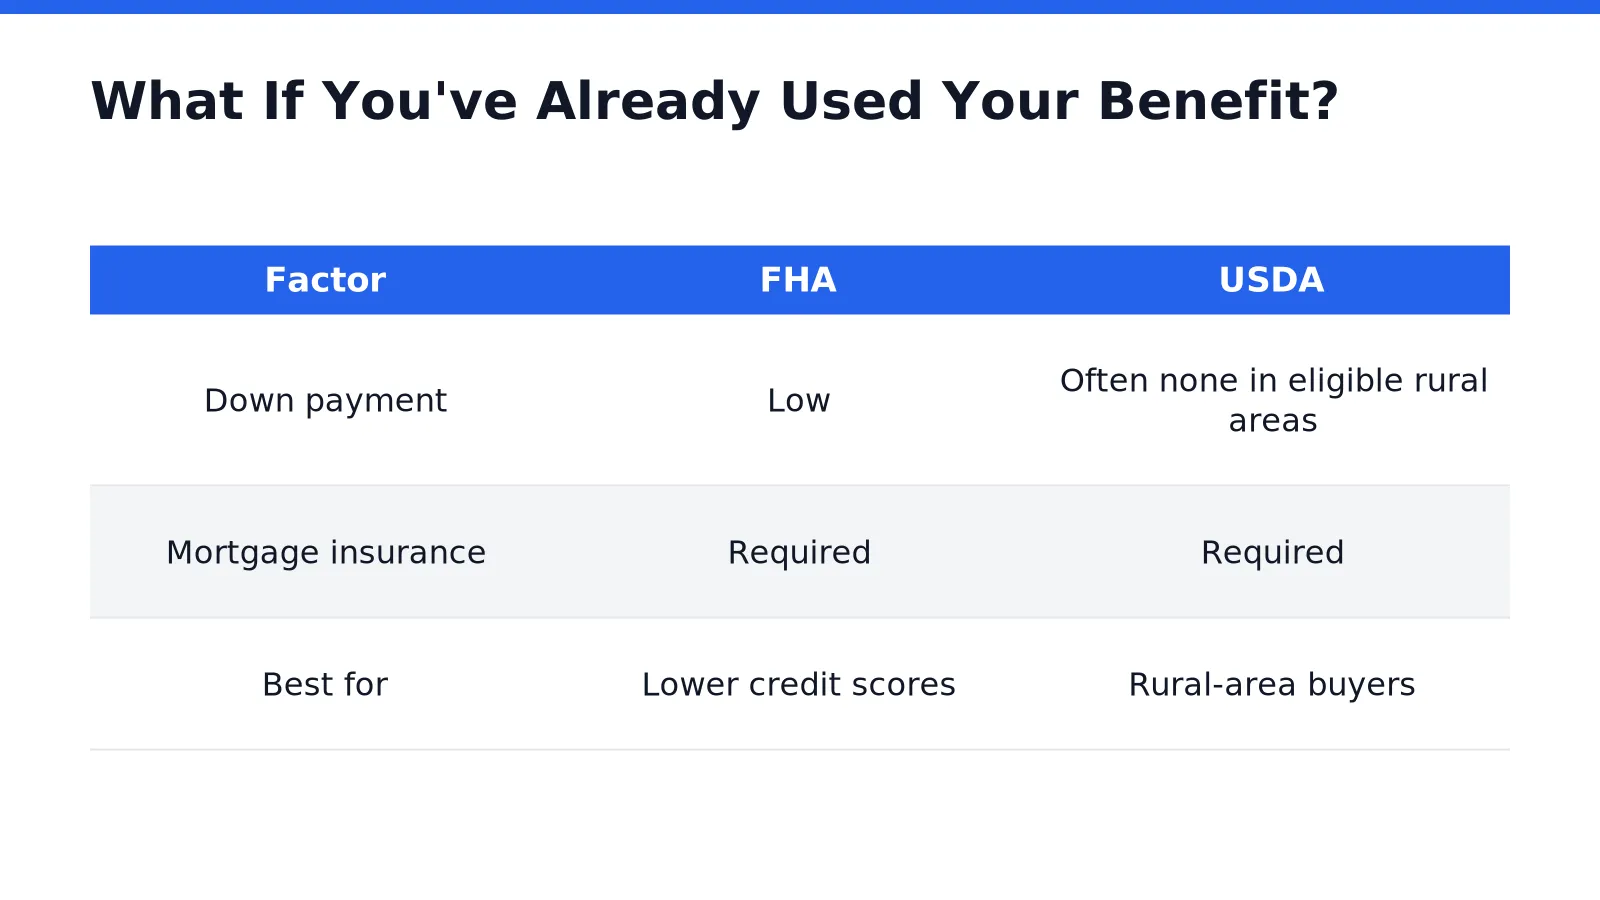
Exhausting a VA loan entitlement does not close the door on homeownership. Military families who have used up their VA guaranty can still qualify for other military-focused loan products built around service-connected careers and income. This comprehensive military-veteran-mortgage-guide-029 approach looks past a single loan type toward the full menu of financing paths open to service members.
Munshi Capital’s lending programs extend well past VA eligibility limits. FHA, USDA, and bank statement loans each carry distinct qualifying criteria, giving military borrowers real options once VA benefit no longer applies. These programs round out a broader set of va-loan-resources-029 built for borrowers at every stage of service, deployment, and civilian transition.
Which loan fits best after VA eligibility runs out?
The right choice depends on four factors working together: interest rate, mortgage insurance requirement, down payment size, and eligibility standards. No single product wins on every measure. Comparing them side by side matters more than chasing one factor alone.
Does military status still matter without VA eligibility?
Yes. Service history still shapes underwriting conversations, income documentation, and loan structuring. Munshi Capital’s integrity-driven, personalized service treats every veteran-home-financing-029 case individually, matching military families nationwide with programs suited to their actual financial picture rather than a one-size-fits-all product.
How Does Munshi Capital Simplify Financing?
Munshi Capital simplifies financing by replacing guesswork with transparency at every stage of the loan process. Active-duty members, veterans, National Guard and Reserve personnel, and military spouses receive the same honest communication given to every borrower, with no confusing fine print and no last-minute conditions sprung on the file.
This commitment shapes a reliable military and veteran mortgage guide to the lending journey. Rather than leaving applicants to decode jargon on their own, Munshi Capital walks each file through three connected stages:
- Application: Documentation requirements are explained upfront, not discovered midway through underwriting.
- Underwriting: Loan specialists review the file with clear criteria, flagging issues early instead of late.
- Closing: Terms match what borrowers were told from the start, with no hidden surprises at the table.
How fast can a military borrower get pre-approved?
Speed comes from pairing modern lending technology with hands-on loan specialists who understand military income and benefit documentation. That combination shortens the pre-approval timeline without skipping the verification steps a solid application requires.
Can borrowers track their loan status in real time?
Full visibility runs through the entire file, from submission to the closing table. Borrowers see exactly where their loan stands, which stage is active, and what remains outstanding, removing the uncertainty that often accompanies military relocations and tight closing windows.
For Servicemembers comparing options against broader VA loan resources, this structure offers a dependable alternative built around clarity rather than speed alone. Anyone evaluating veteran home financing paths can start that conversation and request a direct cash offer. Request your property assessment, to see how transparent underwriting applies to their specific situation.
Which Loan Program Fits Your Family?
Family size, income type, and long-term goals determine the right mortgage path. Military households rarely fit a single mold. Loan selection depends on service status, income documentation, and whether the goal is a primary residence or an investment property.
Munshi Capital Inc. structures its lending around this reality. The company’s military-veteran-mortgage-guide-029 draws on FHA, VA, USDA, and bank statement loan programs, each built to accommodate non-traditional military income such as housing allowances, combat pay, or disability compensation. A borrower transitioning from active duty into civilian employment needs different documentation than one still drawing military pay. The loan structure should reflect that difference rather than force a single standard.
What If a Veteran Wants to Buy a Rental Property?
Veterans expanding into real estate investment have access to va-loan-resources-029 that extend beyond primary-residence financing. DSCR loans qualify borrowers based on a property’s rental income rather than personal income documentation. Hard money loans offer short-term, asset-based financing for veterans moving quickly on investment opportunities.
How Does a Military Family Choose Between Programs?
Choosing the right fit starts with an honest look at income stability and long-term housing plans.
veteran-home-financing-029 works best when guidance stays clear from application through closing. Munshi Capital Inc. commits to that clarity, offering dependable service and honest answers at every stage of the loan process.
FAQ
What are the main benefits of a VA loan for military families?
VA loans offer 100% financing with no down payment, no mortgage insurance requirement, and generally lower interest rates than conventional loans, reducing monthly housing costs for eligible servicemembers and veterans.
Who qualifies for VA home loan benefits?
Active-duty members, veterans, National Guard and Reserve personnel, and certain surviving spouses typically qualify. Specific service-length and discharge requirements apply to each individual case.
What happens if a military family exhausts their VA loan entitlement?
Families who exhaust VA entitlement often qualify for alternative programs, such as a Navy Federal Military Choice Loan, and Munshi Capital Inc. provides guidance through these additional residential loan options.
Conclusion
In closing, military families deserve mortgage solutions that honor their service through straightforward financing and unwavering support. VA loans represent a powerful benefit, yet navigating the full spectrum of available programs requires expertise grounded in transparency and personalized guidance. The right lender understands your unique financial circumstances and delivers clear answers without hidden complexities. By partnering with a mortgage specialist committed to integrity and dependable service, you secure not merely a loan. A trusted advisor dedicated to your homeownership success.
Leave a Reply