Eligible veterans and active military members qualify for VA loans with zero down and no income limits. USDA loans serve non-military buyers purchasing in approved rural areas who meet income caps and pay annual fees. VA loans typically carry lower long-term costs. USDA loans fit rural buyers without military service seeking zero-down financing through Munshi Capital Inc.’s loan programs.
Key Takeaways
- VA loans require zero down payment and serve eligible Veterans and military borrowers exclusively
- USDA loans offer zero down payment to general public borrowers in eligible rural areas nationwide
- VA loans typically feature lower long-term costs and greater flexibility than USDA loan options
- USDA loans include ongoing annual fees and income restrictions that VA loans do not impose
Who Qualifies For A VA Or USDA Loan?
Eligibility draws the sharpest line between these two programs. VA loans serve eligible veterans, active-duty service members, and certain surviving spouses. USDA loans open to any borrower willing to buy in an approved rural area and stay under local income limits. That distinction shapes the entire comparison of va vs usda financing. One path depends on service history and the other on geography and earnings.
Do veterans automatically qualify for VA loans?
Service alone does not guarantee approval. Lenders still verify credit, income stability, and a valid Certificate of Eligibility tied to military service. Military loans under the VA program reward service, but underwriting standards still apply.
Can non-military buyers use a rural mortgage program?
Yes. USDA financing welcomes the general public, not just veterans. Approval hinges on two factors: property location and household income relative to area limits. This makes USDA a practical zero-down option for civilian buyers shut out of VA eligibility entirely.
Munshi Capital Inc. builds its residential loan programs, VA and USDA included, around each borrower’s actual financial picture rather than a one-size approach. Guidance stays personalized from the first conversation through closing, helping veterans and rural buyers alike move forward with confidence. The application walkthrough stays clear and direct, so eligibility questions get answered before surprises can surface later.
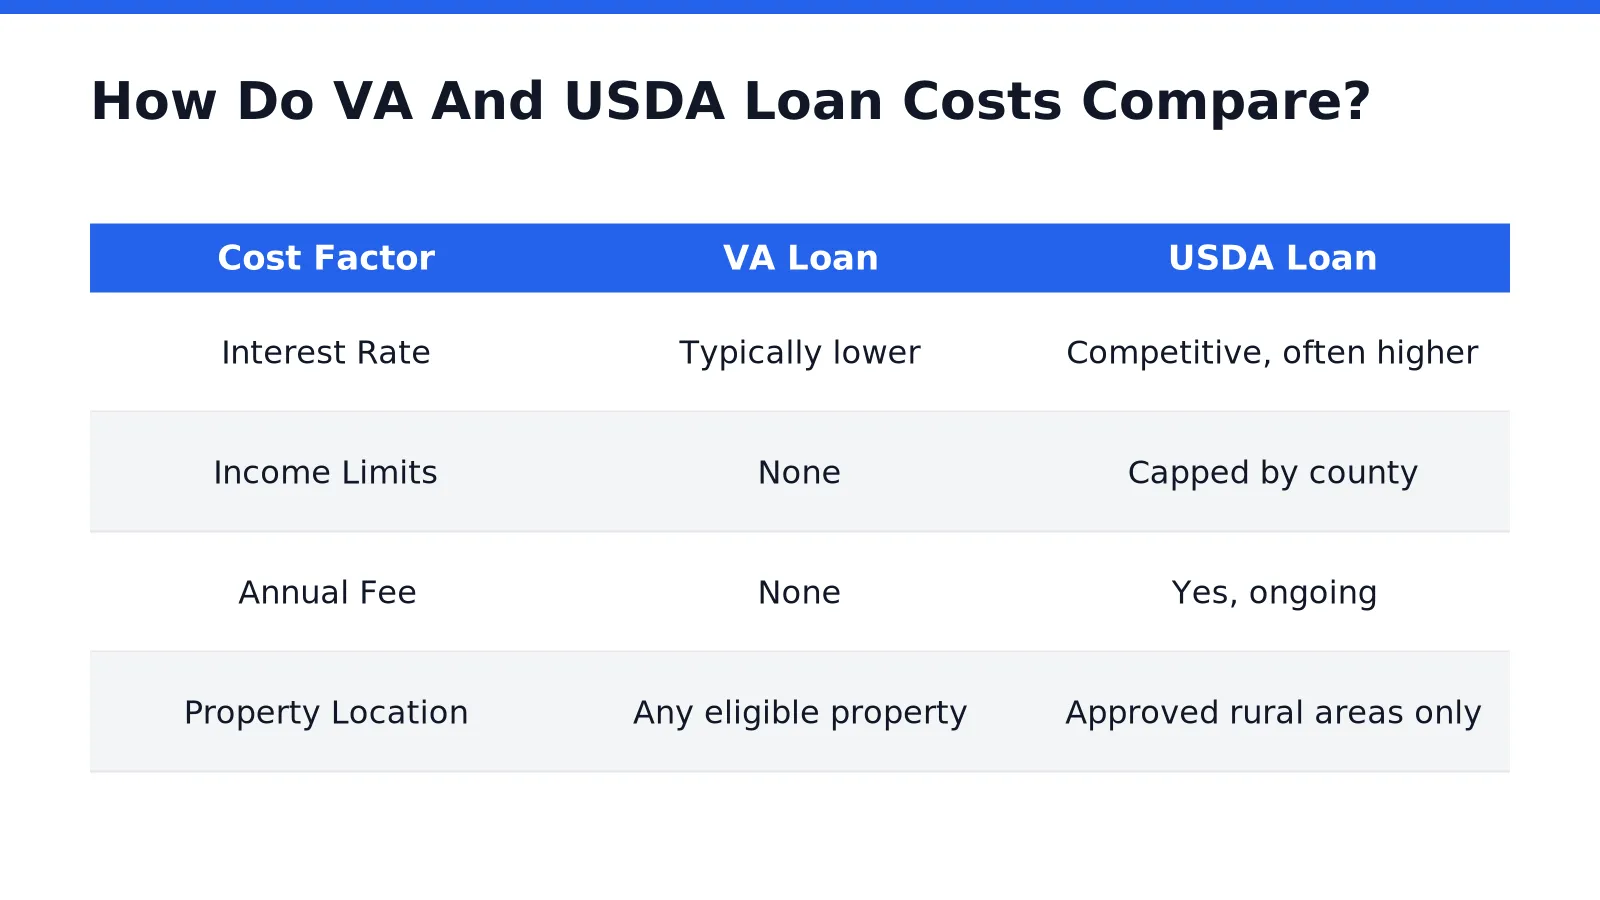
How Do VA And USDA Loan Costs Compare?
Cost differences between these two programs center on interest rates, fees, and eligibility rules. VA loans typically carry lower interest rates and impose no income limits. USDA loans add annual fees and stricter income-based qualification standards. For veterans weighing military loans against rural financing options, that gap shapes monthly payments for years to come.
Long-term affordability tilts toward VA financing. VA loans generally produce lower overall costs and greater flexibility than USDA loans, which carry location restrictions, income caps, and ongoing annual fees. A rural mortgage comparison between the two programs shows USDA’s annual fee structure adding a recurring cost that VA borrowers simply never pay.
The table below highlights the core cost factors separating the two programs.
Which loan costs less over time?
VA loans generally cost less across the life of the mortgage because they skip the recurring annual fee tied to USDA financing. Borrowers running a va vs usda cost review should weigh that annual fee against USDA’s rural-area flexibility before choosing a program.
Does loan type change closing transparency?
Munshi Capital Inc.’s underwriting and closing process keeps every fee. Rate disclosed upfront, no matter which program a borrower selects. Modern technology paired with hands-on loan specialists delivers fast pre-approval timelines. Borrowers see full visibility into pricing from application through closing, with no hidden surprises along the way.
Which Rural Or Suburban Buyers Fit USDA Loans?
Rural and suburban buyers who plan to settle permanently outside major metro centers fit USDA loans best. The program targets low-to-moderate income households committed to living in designated rural areas, not short-term investors or buyers chasing urban addresses. A rural mortgage comparison quickly shows why: USDA financing rewards geographic commitment over credit profile alone.
Civilian buyers without military service ties gain the most from this path. Zero-down financing through USDA loans gives non-military households in eligible rural areas a genuine path to ownership without years of saving for a down payment. For buyers weighing a va vs usda decision, income and location, not service history, decide eligibility here.
Who Qualifies For A USDA Loan?
Qualification hinges on income limits tied to the local area. A property located within a USDA-eligible rural or suburban zone. Buyers do not need military loans eligibility or veteran status to apply. Commitment to rural living matters as much as the numbers on a credit report.
Is USDA Better For First-Time Buyers Than Other Zero-Down Options?
For civilian buyers without VA eligibility, USDA often stands as the strongest zero-down option available. It suits households planning long-term residency in a qualifying area rather than those needing flexibility to relocate.
Buyers weighing USDA eligibility should consider:
- Household income relative to local area limits
- Whether the target property sits inside a USDA-eligible zone
- Long-term plans to live in that rural or suburban community
Munshi Capital Inc. maintains city-specific mortgage pages showing local loan programs, rates, and market insights for each buying location. Pair that research with a request your property assessment before committing to any rural purchase.
What Do Military Loans Offer Veterans Financially?
Military loans deliver zero-down financing, flexible credit standards, and a path to primary-residence ownership without draining savings. Eligible veterans and active-duty service members gain access to one of the strongest government-backed mortgage benefits available. Comparing military loans against rural financing options clarifies which program fits a given financial picture.
VA and USDA loans share a core advantage: both eliminate the down payment barrier and relax credit requirements that trip up conventional buyers. Weighing va vs usda options side by side matters, since each program serves a different borrower profile and property type.
Who qualifies for a VA loan?
Eligibility runs through military service, not income or geography. Veterans, active-duty members, and certain surviving spouses typically meet the baseline requirement. Unlike a rural mortgage comparison against USDA programs, VA eligibility does not hinge on where the property sits.
Why does loan guidance matter for veterans?
Clear communication separates a confident closing from a stressful one. Munshi Capital Inc. emphasizes clarity and honest communication throughout the lending process, a standard that carries real weight for veterans sorting through benefit details. Mortgage financing built around each borrower gives veterans guidance through every loan program, paired with clear answers instead of jargon.
Integrity and personalized service remain the foundation of that approach, extending to military borrowers alongside first-time buyers and investors nationwide. Veterans exploring zero-down financing deserve a lender who explains every term before it reaches a closing document. Those ready to put VA benefits to work can request a direct cash offer conversation or request your property assessment to see how the numbers line up before committing to a program.
Which Zero-Down Option Fits Your Situation?
Military service, property location, and income level determine the right zero-down path. Veterans and active-duty members typically qualify for military loans backed by the VA. Rural and suburban buyers without service history often turn to USDA financing instead. Comparing va vs usda programs side by side clarifies which path fits a borrower’s circumstances and eligibility.
Selecting between these two programs is rarely simple. Qualifications, location, and household income each shift the balance. A buyer who checks both boxes faces a genuine decision rather than an easy default.
Is USDA ever the better choice for a veteran?
Yes, in specific cases. A veteran purchasing in a USDA-eligible rural area with income inside USDA limits may find the program’s terms line up well with the property and budget. Knowing every option available, rather than assuming military status settles the question automatically, protects a buyer from leaving a better fit unexplored.
A side-by-side rural mortgage comparison highlights the deciding factors:
How does Munshi Capital Inc. help borrowers decide?
Munshi Capital Inc. built its lending process on trust, pairing borrower-first guidance with full clarity at every step. The team walks eligible service members and rural buyers through program comparisons with honesty, not guesswork. Fast, transparent underwriting keeps loan status visible from application through closing. No borrower is left wondering where their file stands.
FAQ
Who qualifies for a VA loan versus a USDA loan?
VA loans serve eligible veterans, active-duty service members, and certain surviving spouses, with zero down and no income limits. USDA loans serve the general public buying in approved rural areas who meet local income caps.
Which loan typically costs less over time?
VA loans typically carry lower interest rates and no income limits, producing lower overall costs and greater flexibility. USDA loans add ongoing annual fees and income-based qualification standards that increase long-term expenses.
How does Munshi Capital Inc. help borrowers choose between these programs?
Munshi Capital Inc. builds its VA and USDA loan programs around each borrower’s financial picture, offering personalized guidance from the first conversation through closing. Their clear application walkthrough answers eligibility questions before surprises arise.
Conclusion
In closing, the choice between a VA loan and a USDA loan depends entirely on your eligibility, financial circumstances, and property requirements. Both programs eliminate or substantially reduce down payment obligations, yet they serve distinct borrower profiles and geographic considerations. Munshi Capital Inc. provides the personalized guidance necessary to evaluate these options against your specific situation, ensuring you secure financing aligned with your goals. Our loan specialists deliver transparent analysis. Dependable service throughout the entire process, empowering you to make an informed decision with confidence.
Leave a Reply