Hard money loans serve as a crucial resource in real estate financing, enabling quick access to capital that conventional loans often can’t provide. These loans are mostly used by real estate investors looking for speed and flexibility in property investments. Unlike traditional mortgage options, hard money loans offer unique advantages that cater specifically to those involved in real estate transactions. In this article, we will dive deep into the inner workings of hard money loans, including their key features, interest rates, and benefits, while also discussing the scenarios where they are most beneficial. We will also examine the risks and approval requirements associated with these loans.
What Are Hard Money Loans and How Do They Function in Real Estate Financing?
Hard money loans are short-term financing options backed by real estate assets rather than personal creditworthiness. Their primary function is to facilitate quick funding for real estate investments, making them a popular choice among investors needing to act swiftly. The essence of hard money lending lies in its asset-based structure, where the property itself serves as collateral. This function contrasts with traditional loans that rely heavily on the borrower’s credit history and income verification.
What Distinguishes Hard Money Loans From Conventional Mortgage Loans?
The main distinction between hard money loans and conventional mortgage loans lies in their approval processes and terms. Hard money loans are typically approved much faster, often within days, as they focus on the property’s value rather than the borrower’s creditworthiness. In contrast, conventional mortgages require extensive documentation, credit checks, and can take weeks to finalize. Additionally, hard money loans usually come with higher interest rates but offer greater flexibility in terms of repayment schedules and loan structures.
Which Real Estate Investment Scenarios Benefit Most From Hard Money Lending?
Hard money loans suit various investment scenarios, particularly when speed is essential. Investors often utilize these loans for fix-and-flip projects, where properties are purchased, renovated, and quickly resold. They are also ideal for real estate investors looking to seize opportunities on properties that conventional lenders might view as too risky, such as distressed properties or those requiring substantial renovations. In cases where quick financing is critical, hard money loans provide a viable solution to move forward without delay.
What Are the Typical Interest Rates and Loan Terms for Hard Money Loans?
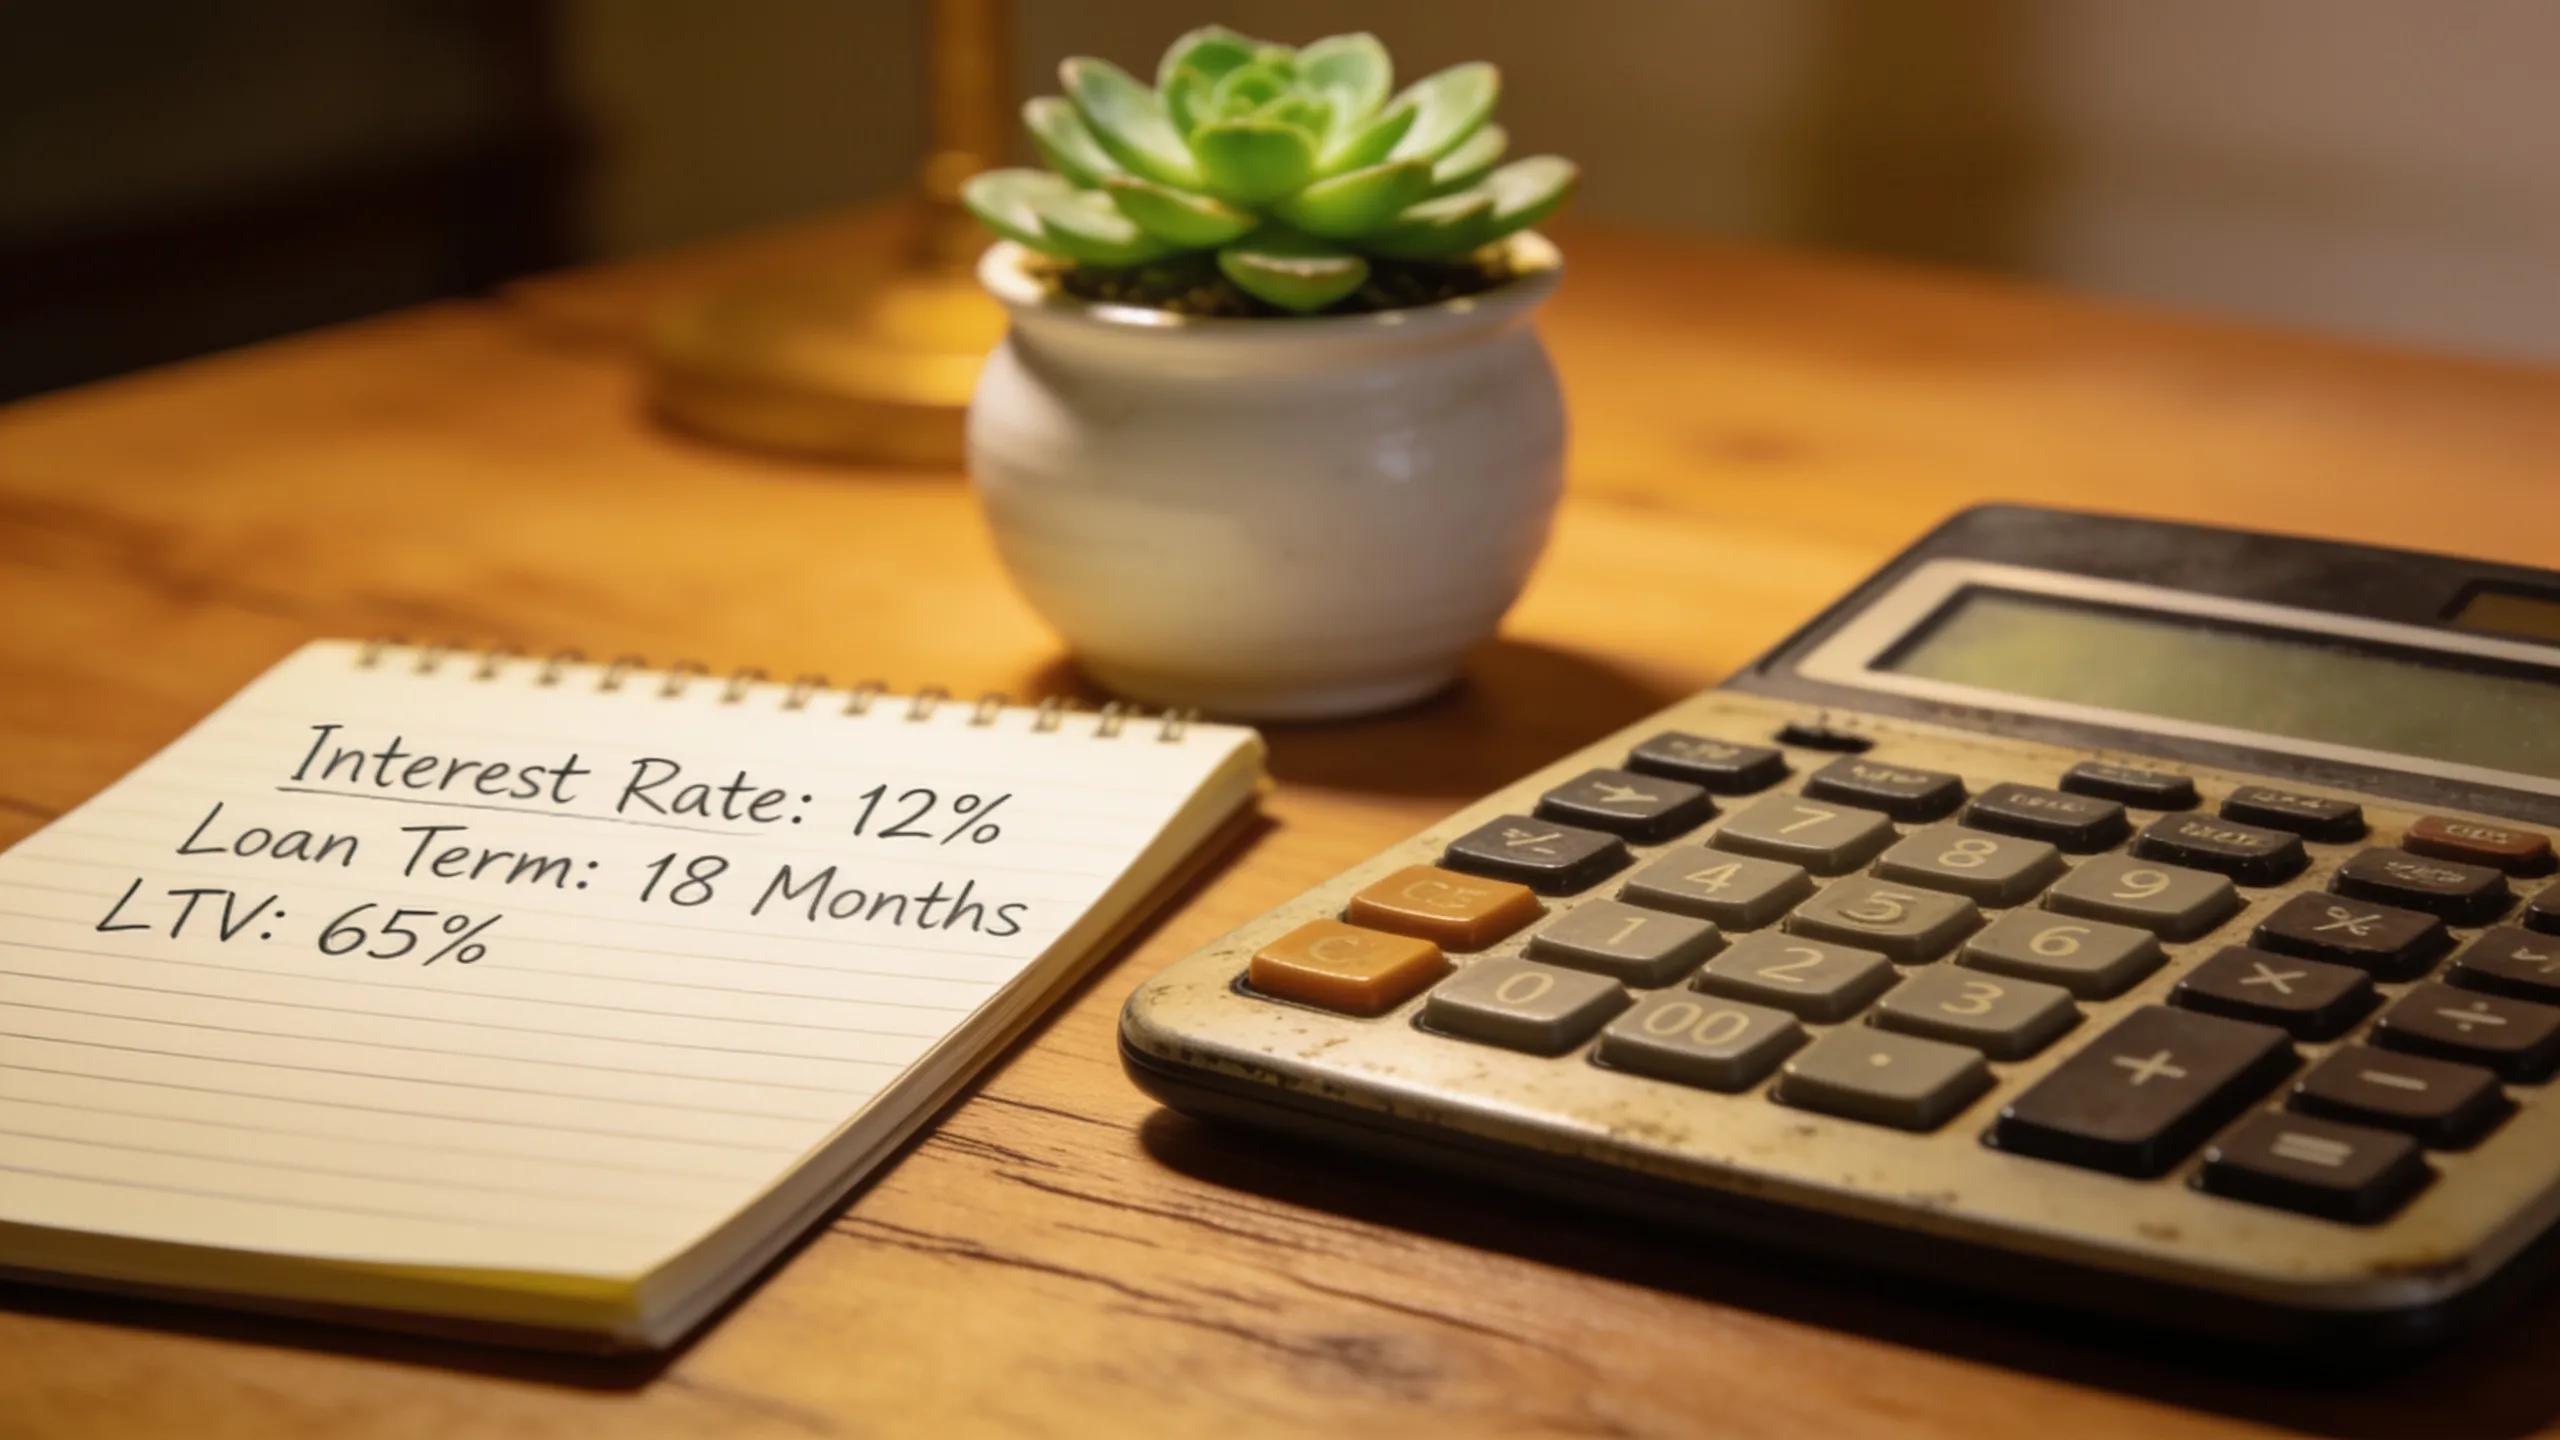
When considering hard money loans, understanding the typical interest rates and loan terms is crucial for investors. These loans generally carry higher interest rates, reflecting the risk involved. The interest rates can vary widely but usually range from 7% to 15%, depending on the lender and the perceived risk of the loan. The terms often range from six months to three years, making them suitable for short-term projects.
How Do Hard Money Loan Interest Rates Compare to Conventional Loan Rates?
The interest rates for hard money loans are generally significantly higher than those of conventional loans, which can range from 3% to 7% for well-qualified borrowers. This stark contrast is due to the higher risk assumed by lenders in the hard money sector, as these loans are often provided to borrowers lacking strong credit histories. Investors should carefully calculate the cost of borrowing to ensure the project’s potential returns exceed the loan expenses.
What Are Common Loan Term Lengths and Loan-to-Value Ratios in Hard Money Lending?
Common loan terms for hard money loans typically vary between 12 months to 36 months. Loan-to-value (LTV) ratios commonly hover around 60% to 75%. This means that lenders will typically lend a certain percentage of the property’s appraised value, which provides a cushion against potential losses. It’s essential for investors to understand these metrics as they directly influence the amount they can borrow and the viability of their investment strategies.
What Are the Key Advantages and Limitations of Hard Money Loans for Real Estate Investors?
Hard money loans offer unique advantages and limitations for investors in the real estate market. Understanding these can help investors make informed decisions on whether to utilize this type of financing.
What Benefits Do Hard Money Loans Offer for Quick Property Financing and Investment Flexibility?
- Speed of Funding: Hard money loans can be funded within a few days, allowing investors to act quickly on opportunities.
- Flexible Terms: Many hard money lenders offer customizable terms that can align with the investor’s needs or project timelines.
- Asset-Based: The focus on the property value rather than the borrower’s creditworthiness provides access even for those with lower credit scores.
These advantages make hard money loans particularly appealing for investors aiming to capitalize on rapidly changing market dynamics or seize purchase opportunities that require urgent funding.
Understanding how alternative financing fits into broader investment strategies helps clarify the mechanics of leveraging outside capital for property acquisition.
Financing Strategies for Real Estate Investments
Many are under the misconception that they cannot invest in real estate because of a lack of capital. This belief is entirely untrue and there are dozens of different strategies for investing in real estate with little or no capital from one’s own pocket. Many of these strategies don’t require bank involvement either. Leveraging other people’s money (OPM) in order to invest is a way to speed up the traditional route of getting to financial freedom/retirement. Financing strategies for real estate investments, 2017
What Are the Potential Risks or Drawbacks Investors Should Consider With Hard Money Lending?
- High-Interest Rates: The cost of borrowing is significantly higher than conventional loans, which can cut into profit margins.
- Short Repayment Terms: Borrowers must have a clear exit strategy to repay loans quickly, as failing to do so can result in foreclosure.
- Risk of Over-Leverage: Investors might overestimate property values, leading to inadequate funding for renovations or repayment difficulties.
Awareness of these risks is paramount, as they can profoundly affect the overall success of investment projects financed through hard money loans.
What Are the Standard Requirements and Application Process for Securing a Hard Money Loan?
To secure a hard money loan, investors must understand the typical documentation required and the application process involved. This knowledge can streamline the borrowing experience.
Which Documentation and Credit Criteria Are Typically Required?
The documentation needed typically includes details about the investment property, proof of ownership or purchase agreement, and a basic financial statement. Unlike conventional loans, hard money lenders often do not require extensive credit checks, focusing primarily on the asset rather than the borrower’s credit history. This makes hard money loans accessible for those with less than perfect credit.
How Does the Hard Money Lending Approval Process Differ From Traditional Loans?
The approval process for hard money loans is much more straightforward and can often be completed within a few days. This quick turnaround is a significant advantage for investors looking to close on properties swiftly. Unlike traditional loans, where multiple parties are involved and the process can drag on due to various checks and balances, hard money loans provide a streamlined experience focused on rapid decision-making.
Leave a Reply