USDA Rural Development Loans deliver 100% financing with no down payment for buyers purchasing in eligible rural. Suburban areas, guaranteed by the U.S. Department of Agriculture. Eligibility depends on household income limits and property location, both verified through USDA’s official eligibility site. Munshi Capital Inc. guides first-time and moderate-income borrowers through qualification, application, and closing with transparent, step-by-step support.
Key Takeaways
- USDA loans provide 100% financing with zero down payment required for eligible rural and suburban homebuyers.
- Household income must meet USDA guidelines; property location must fall within USDA-defined eligible rural areas.
- First-time homebuyers benefit significantly from USDA financing options designed to make homeownership more accessible and affordable.
- Our loan specialists guide you through USDA eligibility requirements with transparent communication and personalized support throughout.
What Makes USDA Loans Different From Other Mortgages?
Zero down payment separates USDA financing from nearly every other mortgage product on the market. Eligible buyers in rural and suburban areas secure 100% financing, meaning no down payment stands between a family and a signed deed.
This distinction matters most for first-time buyers and moderate-income households who have steady jobs but limited savings. A usda loan guide for these borrowers starts with one fact: location and income primarily determine eligibility. Credit history also plays a role. That shift in qualifying logic changes who gets to own a home.
Who Qualifies for a USDA Loan?
Qualification depends on property location and household income, not credit wealth or large reserves. Buyers purchasing in designated rural or suburban zones, who meet income limits for their area, typically qualify. Munshi Capital Inc. includes these loans within a broader suite of residential. Commercial programs, giving borrowers context on how USDA financing compares against other paths.
Beyond the zero-down structure, the process itself sets USDA apart. Munshi Capital Inc. guides borrowers through a straightforward application and closing process built on clear, honest communication at every step. That transparent approach, paired with usda mortgage info delivered plainly, removes guesswork for first-time applicants.
Technology plays a role too. Munshi Capital Inc.’s process pairs modern tools with hands-on loan specialists. Borrowers reviewing usda eligibility requirements receive both fast answers and personal guidance, not an automated dead end.
Who Actually Qualifies For A USDA Loan?
Household income determines eligibility for a USDA-backed mortgage more than any other factor. Property location matters too, since the home must sit within a USDA-designated rural or suburban zone. This usda-eligibility-006 framework exists to direct financing toward moderate-income households in areas the federal government wants to support.
The core income test is straightforward: a household’s total income cannot exceed 115% of the Area Median Income for the county where the property sits. That figure shifts county by county, so a family earning a qualifying wage in one region might sit above the limit in a wealthier neighboring county. Lenders calculate this using every income source in the household, not just the borrower’s paycheck.
What Income Counts Toward USDA Limits?
USDA guidelines require that combined household income, including wages from non-borrowing household members, meet the program’s specific thresholds. This broader calculation differs from conventional mortgage underwriting, which typically counts only the applicant’s income. Shoppers researching this usda-loan-guide-006 should gather income documentation for everyone living in the home before applying.
Does A Low Credit Score Disqualify An Applicant?
Credit history plays a role, but income eligibility remains the gatekeeping factor most first-time buyers overlook. Suburban shoppers exploring this usda-mortgage-info-006 often assume credit score alone decides approval, when county income limits frequently matter just as much.
Eligibility generally hinges on:
- Total household income at or below the county’s 115% AMI threshold
- Property location within an approved rural or eligible suburban boundary
- Documented income from all household members, not just the primary borrower
Munshi Capital Inc. offers personalized guidance that walks first-time and low-to-moderate income borrowers through these income. Location rules, helping each applicant understand exactly where they stand before submitting paperwork.
Which Areas Count As USDA-Eligible Rural Or Suburban?
Location determines everything. A property qualifies only when it sits inside a zone USDA defines as eligible rural, a boundary set by federal mapping rather than local zoning lines. That single requirement separates USDA financing from loan products available in every market nationwide.
Many buyers assume “rural” means farmland or distant countryside. In practice, eligible zones often include small towns, exurbs, and growing suburbs just outside major metro boundaries. Confirming an exact address against USDA’s standards, a core step in any solid usda eligibility review, prevents wasted time pursuing a home that cannot qualify. Skipping this step leads buyers straight into a denied application after months of searching.
Because boundaries shift by county, and sometimes within a single neighborhood, local knowledge carries real weight. Munshi Capital Inc. maintains city-specific mortgage pages across the country, giving first-time buyers local programs, rates, and market insights tailored to the exact area where they’re shopping for a home. That local lens, paired with a structured usda loan guide approach, turns a confusing map exercise into a clear yes-or-no answer.
Does USDA Eligibility Change Over Time?
Yes. Population growth can shift a suburb from eligible to ineligible within a few years. Buyers eyeing a specific neighborhood should verify current status rather than trusting an outdated map.
Can Suburban Buyers Qualify, Not Just Rural Buyers?
Many suburbs near larger cities remain eligible, since the rural definition extends well beyond farmland into lower-density communities. A full usda mortgage info check on the precise address, not the general region, delivers the accurate answer. Munshi Capital Inc. offers residential loan programs, including USDA financing, for first-time homebuyers across the country.
What Benefits Do USDA Loans Offer Buyers?
Zero-down financing stands as the clearest advantage of a USDA-backed mortgage. Rural and suburban buyers gain access to homeownership without years of saving for a down payment, a path few conventional programs offer. This complete USDA loan guide to buyer benefits starts with that single fact and builds from there.
Beyond the absence of a down payment, USDA loans serve a broader economic purpose. The program is structured to encourage homeownership in rural and underserved communities, which in turn supports local economies and strengthens community growth. Buyers are not just purchasing a house; they are investing in neighborhoods the federal program was built to revitalize.
Credit flexibility adds another layer of accessibility. The Single Family Housing Guaranteed Loan Program allows qualified borrowers to purchase with nothing down. Liberal credit standards, opening the door for buyers who might not clear the bar at a traditional lender.
What Makes USDA Loans Different From Conventional Mortgages?
The core difference lies in cost and eligibility structure. Conventional loans typically demand a down payment and stricter credit thresholds. USDA financing removes that barrier for eligible properties and income levels. This distinction matters most for first-time buyers with limited savings.
How Does a Lender Simplify USDA Mortgage Info and Eligibility?
Working through this USDA mortgage info and USDA eligibility process becomes far less stressful with the right lending partner. Munshi Capital Inc. combines modern technology with hands-on loan specialists to deliver fast pre-approvals and full visibility into loan status at every stage. That borrower-first approach is built on transparency, clarity, and honest communication from application through closing. No buyer is left guessing where a file stands.
Key buyer benefits include:
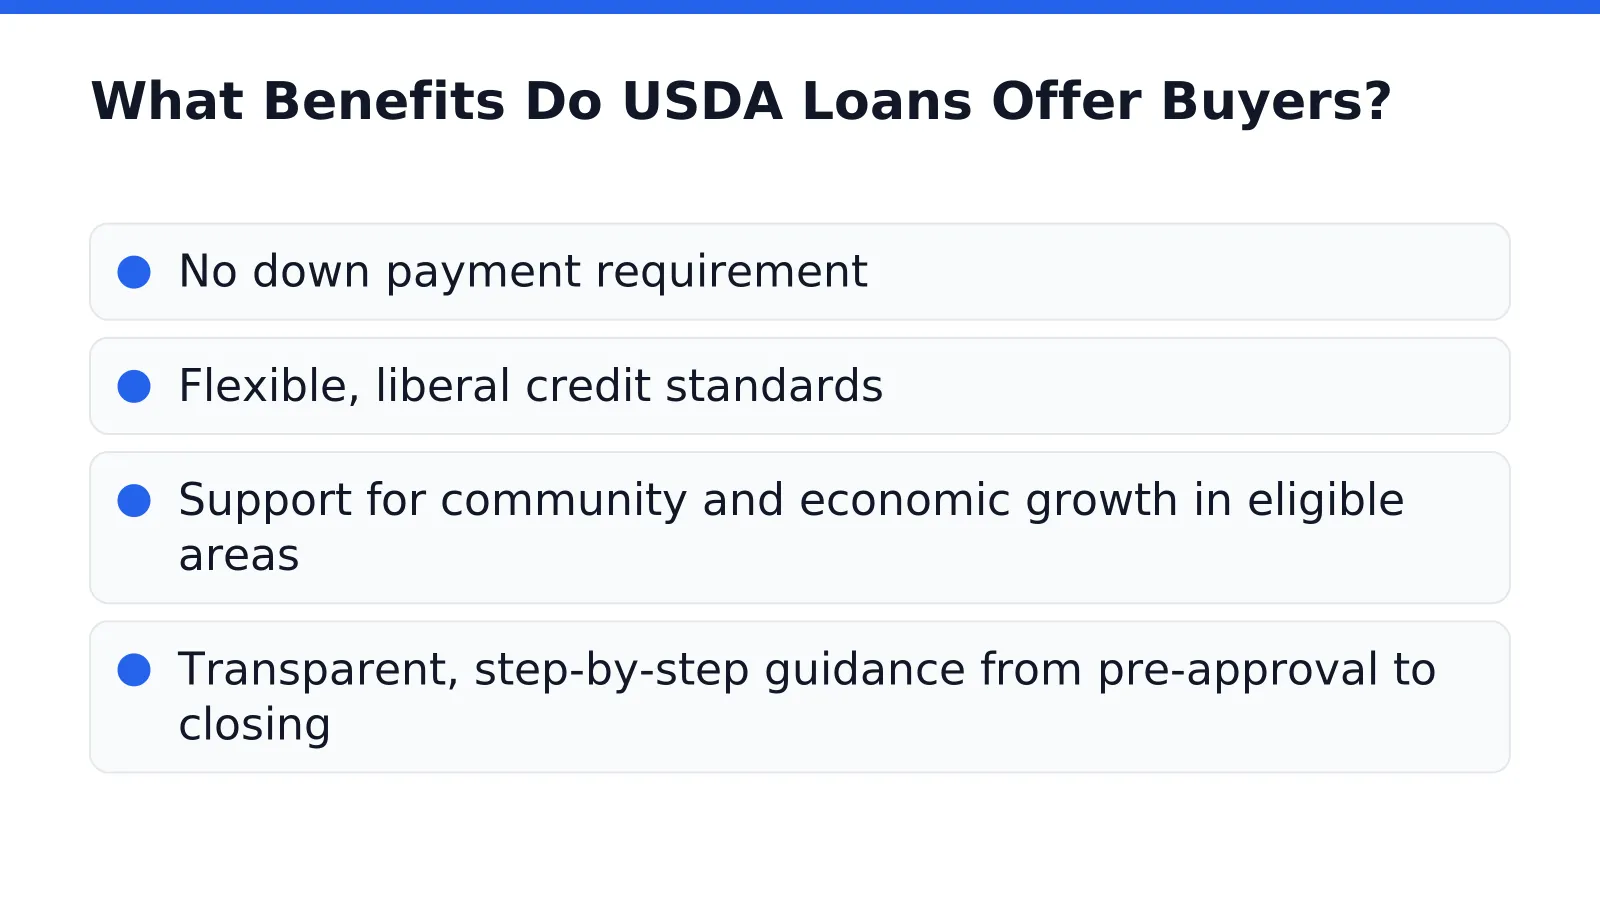
- No down payment requirement
- Flexible, liberal credit standards
- Support for community and economic growth in eligible areas
- Transparent, step-by-step guidance from pre-approval to closing
How Do You Apply For A USDA Loan?
Applying for a USDA loan starts with connecting to an approved lender who can confirm property. Income eligibility before any paperwork begins. Munshi Capital Inc. walks borrowers through this comprehensive usda-loan-guide-006 process, pairing each applicant with a loan specialist from day one.
The application sequence moves through several defined stages, and skipping steps only slows closing. Munshi Capital Inc.’s team guides borrowers through every stage, from initial application to final closing, with clarity and speed. No confusing jargon. No hidden surprises buried in fine print.
A typical application path includes:
- Confirming household income and property location against USDA guidelines
- Submitting income documentation, credit history, and asset statements
- Receiving underwriting review and conditional approval
- Completing appraisal and final loan conditions
- Closing on the home with finalized loan terms
What documents are needed for a USDA loan application?
Lenders typically request pay stubs, tax returns, bank statements, and proof of residency to verify eligibility. This usda-mortgage-info-006 paperwork confirms both income limits and rural property qualification. Munshi Capital Inc. offers guidance through every loan program, built around each borrower’s specific financial picture. Documentation gaps get resolved early rather than at closing.
Why are rural areas gaining popularity with buyers?
Remote work growth since 2019, combined with lower housing prices, has made rural and suburban neighborhoods increasingly attractive to buyers. That shift has widened interest in USDA financing well beyond traditional farm towns.
Munshi Capital Inc.’s approach to usda-eligibility-006 review stays rooted in clarity, honesty, and a service-driven ethos, giving applicants a dependable partner through every step of the lending timeline.
FAQ
What down payment does a USDA loan require?
USDA loans provide 100% financing with zero down payment required for eligible rural. Suburban homebuyers, removing the upfront barrier conventional loans typically demand.
Who qualifies for a USDA loan?
Qualification depends on property location and household income rather than credit wealth or large reserves. Buyers purchasing in designated rural or suburban zones who meet area income limits typically qualify.
How does Munshi Capital support USDA loan applicants?
Munshi Capital Inc. guides first-time and moderate-income borrowers through qualification, application, and closing with transparent, step-by-step support, pairing modern technology with hands-on loan specialists for personal guidance.
Conclusion
In closing, USDA loans represent a substantive financing pathway for rural and suburban homebuyers seeking accessible homeownership without the barriers of traditional lending requirements. The combination of zero down payment options, reduced mortgage insurance costs, and flexible credit criteria positions these loans as a practical solution for borrowers building equity in underserved communities. Munshi Capital Inc. delivers transparent guidance through the USDA loan process, ensuring borrowers understand their eligibility and benefits with clarity and precision. Our loan specialists work to match your financial profile with the right program, removing complexity from your path to homeownership.
Leave a Reply