VA loans provide eligible veterans, active-duty service members, and qualifying spouses a path to homeownership with potential benefits like 0% down payment and no PMI, subject to meeting Certificate of Eligibility requirements. Munshi Capital Inc. structures VA financing with competitive interest rates. Flexible credit guidelines, limiting certain closing costs while delivering transparent, step-by-step guidance from application through closing for military homebuyers nationwide.
Key Takeaways
- VA loans may allow eligible veterans to purchase a home with 0% down payment and no PMI, subject to specific eligibility criteria.
- Competitive interest rates on VA loans typically beat conventional and FHA loan options for military homebuyers.
- Certificate of Eligibility (COE) demonstrates your service history qualifies you for VA-backed financing with our specialists.
- Munshi Capital Inc. guides military borrowers through transparent VA loan processes with personalized support and clear answers.
What Makes a VA Loan Different From Others?
A VA loan separates itself from conventional financing through a federal guaranty. The Department of Veterans Affairs backs this mortgage option for veterans, service members, and surviving spouses, a distinction no conventional or FHA product carries. That backing changes the math for eligible borrowers from day one.
Eligible veterans can purchase a home with 0% down. Skip private mortgage insurance entirely, two features rarely paired together in conventional lending. Conventional loans typically demand a down payment plus monthly PMI charges until enough equity builds up. Skipping both costs preserves cash that would otherwise sit tied up in a down payment or disappear into insurance premiums month after month.
How does a VA loan compare to a conventional loan?
This comparison explains why military families often look to VA financing first.
Munshi Capital Inc. positions VA loans as one option inside a full va mortgage info residential lineup, built around each borrower’s financial picture rather than a one-size-fits-all script. The lending team pairs clear answers with dependable service at every stage of the loan program.
Who qualifies for this benefit?
Qualification hinges on service history and duty status, which forms the core of any va loan eligibility review. Munshi Capital Inc.’s mortgage financing stays built around the individual, guiding veterans, service members, and eligible spouses through every program with transparency instead of guesswork. This va loan guide approach to eligibility, down payment, and PMI is what sets VA financing apart from standard mortgage paths.
Who Meets VA Loan Eligibility Requirements?
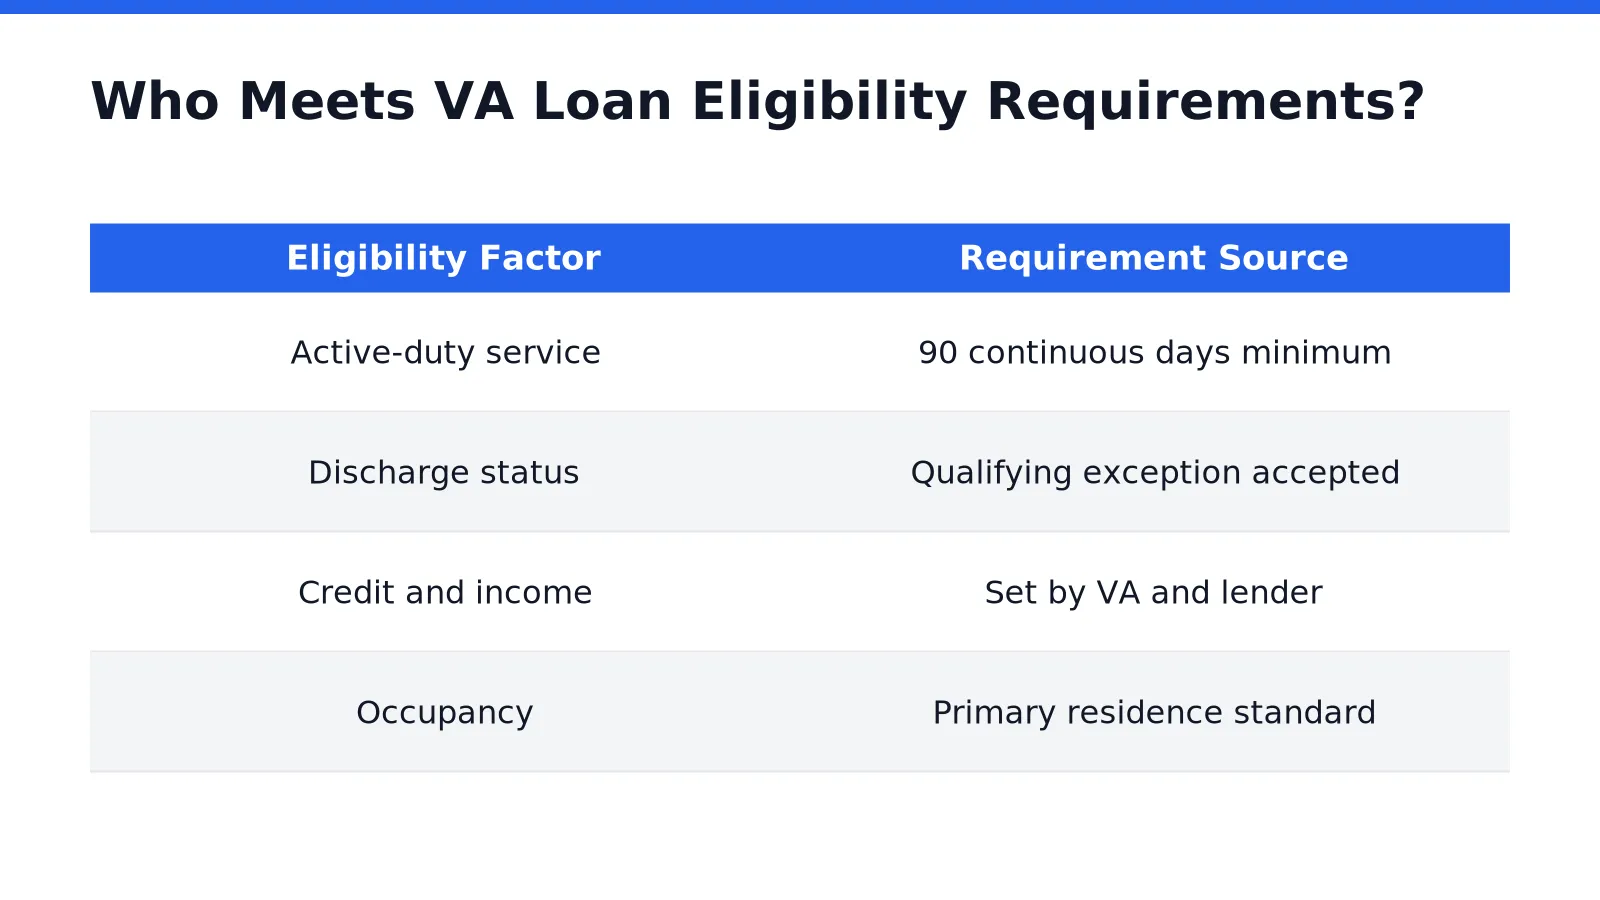
Active-duty service members, veterans, and eligible surviving spouses meet VA loan eligibility standards through specific service thresholds rather than income alone. Completing at least 90 continuous days of active duty, served all at once without a break, satisfies the minimum active-duty service requirement for most applicants. Reservists and National Guard members typically face different timelines, but the baseline standard centers on continuous, uninterrupted service.
Meeting the service requirement, however, does not guarantee automatic approval. Veterans who fall short of the standard minimum may still qualify for a Certificate of Eligibility if they were discharged under a qualifying exception, such as hardship or certain service-connected conditions. This flexibility sets VA financing apart from conventional lending paths.
What Else Do Lenders Check Beyond Military Service?
Service history opens the door, but it does not close the file. Borrowers must still satisfy credit, income, and occupancy requirements set by both the Department of Veterans Affairs and the individual lender. Occupancy rules generally require the financed property to serve as a primary residence, not a rental or investment purchase.
Where Can Military Borrowers Get Reliable Guidance?
Confusion over documentation and exceptions sends many qualified borrowers off track before they even apply. Munshi Capital Inc. offers a complete VA mortgage info resource paired with personalized guidance, helping military borrowers nationwide secure financing with confidence. For a straightforward VA loan guide through the next step, eligible service members and spouses can request a direct cash offer or request your property assessment to clarify where their qualification stands today.
How Does the VA Loan Application Process Work?
Four clear stages define the path from application to closing: intake, program matching, underwriting, and funding. Military homebuyers move through each stage with a dedicated loan specialist, not a call center queue. This complete va-loan-guide-005 walks service members, veterans, and eligible spouses through what to expect before the first form gets signed.
The process starts small. A borrower completes a quick, secure application and shares homeownership goals directly with a loan specialist. From there, the specialist helps identify which residential or commercial program fits the borrower’s situation, whether that means a VA purchase loan, a refinance, or another path suited to military families.
Once the program is selected, the file moves into underwriting. This stage can create anxiety for first-time applicants, since paperwork and verification steps pile up fast. Munshi Capital Inc. counters that friction by guiding borrowers through every step with clarity and speed, stripping out confusing jargon and unnecessary back-and-forth.
What Happens After Underwriting Approval?
Approval triggers the closing stage, where final numbers get confirmed and documents get signed. No hidden surprises surface at this point. The team has already walked the borrower through costs and terms earlier in the process. Closing day becomes a formality rather than a source of stress.
How Fast Can a VA Borrower Get Pre-Approved?
Pre-approval speed depends on documentation readiness, but the combination of modern technology and hands-on va-mortgage-info-005 specialists accelerates the timeline considerably. Borrowers get real answers quickly rather than waiting on manual review backlogs.
Military homebuyers who want a clear next step can request a direct cash offer or request your property assessment before deciding how to proceed. Verifying va-loan-eligibility-005 early keeps the entire timeline on track.
What Financial Advantages Do VA Loans Offer?
Eligible service members, veterans, and qualifying military spouses gain access to 100% financing through a VA loan guide built around measurable savings. No down payment stands between qualified borrowers and homeownership, and interest rates stay competitive compared to conventional financing. These savings compound over the life of a mortgage, turning what would be a steep upfront cost into funds kept in a household’s pocket.
Credit flexibility sets this program apart from conventional lending. Qualification standards remain more forgiving than many conventional loans require, and certain closing costs face strict limits by design. Borrowers who assume they fall short of conventional credit thresholds often find a workable path through VA financing instead.
Why Do VA Loans Cost Less Over Time?
Lower rates combined with zero down payment reduce both the upfront and long-term cost of borrowing. Monthly payments shrink without private mortgage insurance, a cost that conventional borrowers with low down payments typically absorb. That gap alone represents real money that stays with the homeowner instead of an insurer.
Can the VA Loan Benefit Be Used More Than Once?
Yes. This va-mortgage-info-005 benefit functions as a lifetime entitlement, not a one-time offer. It covers home purchase, refinance, and renovation needs across multiple transactions over a veteran’s lifetime.
Munshi Capital Inc. builds its lending approach around integrity and personalized service for military homebuyers nationwide. Clients exploring va-loan-eligibility-005 requirements and financing options can request a direct cash offer. Request your property assessment to see where current equity and buying power stand before moving forward.
What Should Military Borrowers Do Next?
Military borrowers move forward by gathering service documentation and connecting with a lender built for straightforward guidance. Munshi Capital Inc. provides mortgage financing designed for a wide range of borrowers, from first-time homebuyers wearing a uniform to seasoned investors building a property portfolio after retirement from service. The next step is not complicated, but skipping it costs time later.
Start by organizing paperwork. Lenders need clear records to confirm service history and loan standing before any underwriting begins.
What documents does a military borrower need before applying?
Military borrowers typically need discharge paperwork, a statement of service, or proof of continued active duty. Having these ready speeds up the review process and avoids delays during underwriting. Munshi Capital Inc.’s mission centers on transparency. Loan specialists explain exactly which documents matter and why before any application moves forward.
How does Munshi Capital Inc. support military homebuyers through the process?
Clarity and honest communication guide every stage of the lending relationship, from first contact through closing. Munshi Capital Inc. is built on trust, offering borrower-first mortgage guidance rooted in honesty rather than sales pressure. That service-driven approach matters most for military families balancing relocation timelines with financing deadlines.
Borrowers ready to move should take these steps:
- Pull together service and income documentation early.
- Request a va mortgage info consultation to review financing fit.
- Ask about full visibility into loan status from application to closing.
Quick pre-approvals give military borrowers a clear view of where their loan stands at every stage. Homebuyers ready to sell an existing property first should request a direct cash offer before starting the next purchase.
FAQ
Do VA loans require a down payment?
VA loans allow eligible veterans, active-duty service members, and qualifying spouses to purchase a home with 0% down payment. This eliminates the upfront cash barrier common with conventional financing.
Is private mortgage insurance required on a VA loan?
No, VA loans eliminate private mortgage insurance requirements for eligible borrowers. Conventional loans typically require PMI until the borrower builds enough equity.
How does someone prove VA loan eligibility?
A Certificate of Eligibility (COE) demonstrates that a borrower’s service history qualifies them for VA-backed financing. Munshi Capital Inc. specialists guide applicants through this eligibility review with transparent, personalized support.
Conclusion
In closing, VA loans represent a significant advantage for military service members and veterans pursuing homeownership, offering tangible benefits that reflect the nation’s commitment to those who have served. The application and underwriting process demands clarity and expert guidance to maximize these benefits effectively. Borrowers benefit from working with experienced loan specialists who understand the nuances of VA financing. Remain committed to transparent communication throughout the entire lending journey, ensuring confidence at every stage of homeownership.
Leave a Reply