Wholesale mortgage broker program resources include loan program access for FHA, VA, USDA, and bank statement loans through Munshi Capital Inc., serving borrowers across various markets including Los Angeles, San Diego, Sacramento, and Irvine, CA. Origination partners gain underwriting guidance, city-specific market data, and program comparisons through dedicated loan specialists supporting transparent, step-by-step closings nationwide.
Key Takeaways
- Munshi Capital Inc. offers comprehensive loan programs tailored to a diverse range of borrowers nationwide.
- Our wholesale mortgage broker program provides personalized coaching on company setup, recruiting, culture, and scaling strategies.
- Transparent pre-approval processes backed by modern technology deliver quick decisions with full loan status visibility.
- Specialized products like DSCR and hard money loans serve investor-focused financing needs with dependable service.
What Makes Wholesale Lending Different From Retail?
Wholesale lending separates loan origination from loan funding, routing applications through brokers instead of a lender’s retail branch. A wholesale mortgage lender offers financing through third-party channels, such as banks, credit unions, and independent mortgage brokers, rather than negotiating directly with the end borrower. Retail lenders handle every step of the transaction themselves. Wholesale partners rely on brokers to manage the client relationship from first contact to closing.
That distinction changes who controls pricing and process. Brokers working the wholesale channel can secure discounted rates for clients while preparing and owning the application file. Retail loan officers rarely have that pricing flexibility, since their rate sheets come fixed from a single institution.
Why do brokers rely on wholesale partnerships to grow?
Brokers need a lender willing to extend both reach and trust. Munshi Capital Inc. built its wholesale relationship on borrower-first transparency, a standard brokers can pass directly to clients without translation or guesswork. That clarity, paired with financing programs designed to serve first-time homebuyers and seasoned investors alike, gives brokers one partner for a wide client base instead of a patchwork of specialty lenders.
A broker resources guide, a set of brokerage-programs-108, and dedicated wholesale-lending-resources-108 provide originators with infrastructure that a retail branch cannot match. Brokers get underwriting clarity, program breadth, and a partner structured around their book of business rather than walk-in branch traffic.
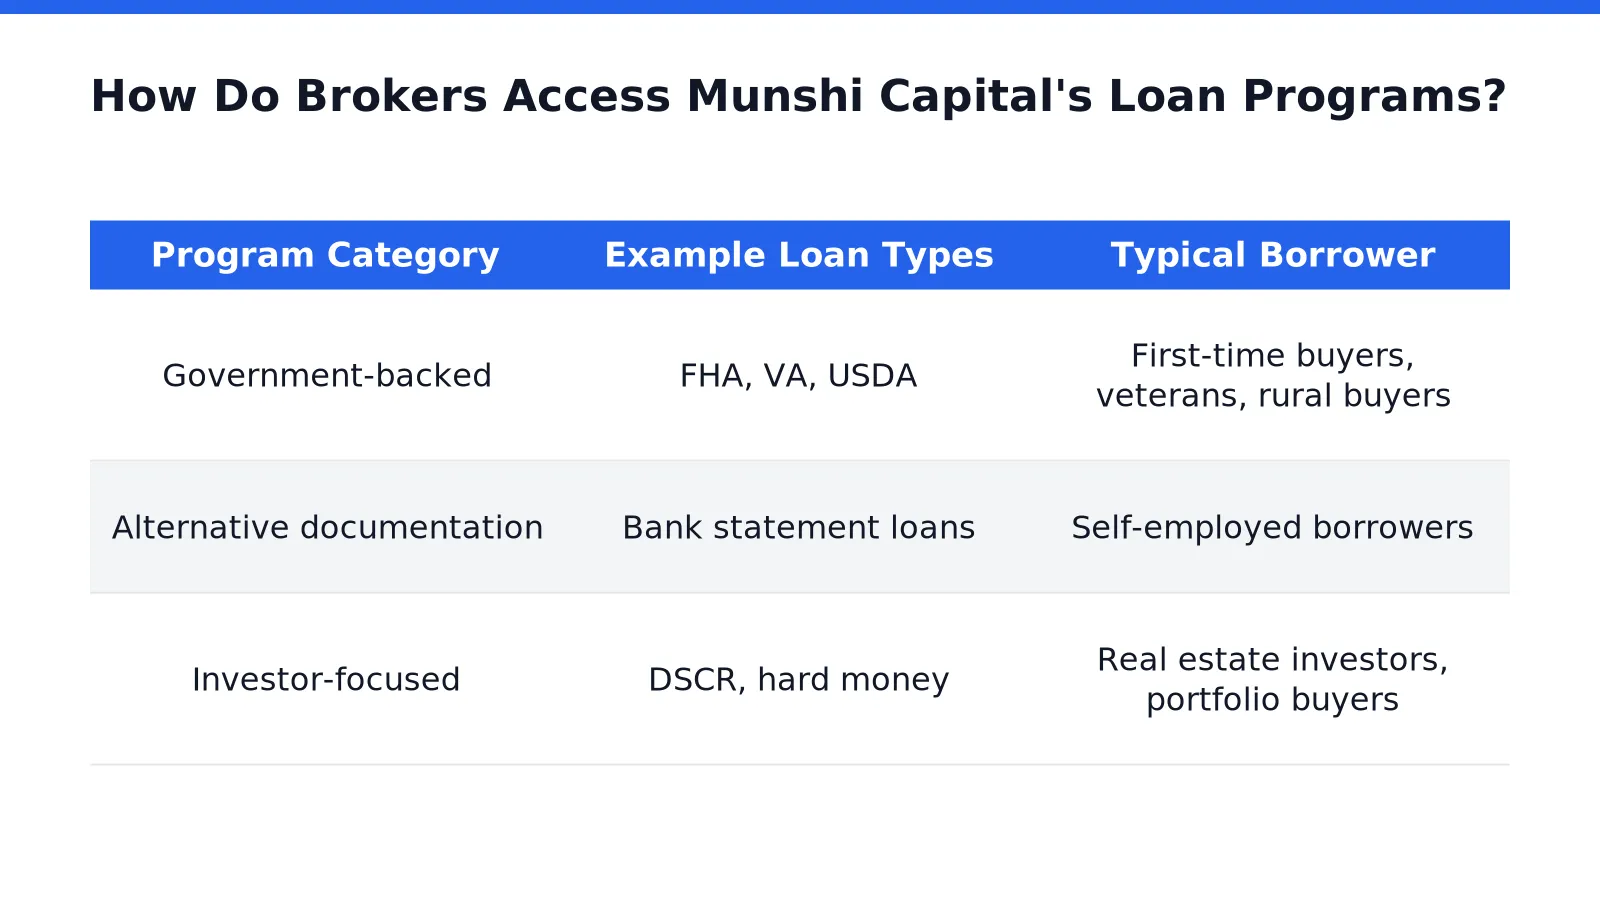
How Do Brokers Access Munshi Capital’s Loan Programs?
Access starts with program fit, not paperwork. Loan officers place FHA, VA, USDA, and bank statement files directly through Munshi Capital’s residential and commercial suite, matching each borrower’s profile to the right product before submission. This structure forms the foundation of the broker-resources-guide-108 that partners rely on when building out a pipeline across multiple loan types.
Investor-focused files extend the reach further. DSCR and hard money products give broker partners a path into financing that sits outside conventional conforming guidelines, covering borrowers who do not fit a standard W-2 underwriting box. Real estate investors, self-employed buyers, and seasoned portfolio holders all fall within this lane.
What Loan Programs Can Brokers Submit Through Munshi Capital?
Residential and commercial files move through the same partner channel, structured around the borrower’s actual financial picture rather than a one-size-fits-all checklist. The table below breaks down the core categories brokers use most.
How Fast Can Brokers Expect Pre-Approvals?
Speed depends on the pairing of technology with direct loan specialist support. Combined, these brokerage programs shorten the distance between file submission and pre-approval for broker-originated pipelines. Guidance stays clear at each stage, so brokers get dependable answers rather than guesswork.
That clarity defines the broader wholesale lending resources available to partners: transparent program access, responsive specialist support, and a process built to move files forward without stalling on ambiguity.
What Resources Help New Brokerages Launch And Scale?
New brokerage owners gain the fastest traction through dedicated support teams that coach them on company setup, recruiting, culture building, and scaling operations. A structured broker resources guide addresses the exact challenges that stall growth in the first months of running an independent shop. Without that early guidance, owners spend months solving problems that experienced partners already know how to fix.
Resource hubs built for new owners typically compile training videos, reference links, and step-by-step process documents. These materials walk a broker through the practical steps that follow the opening of an independent mortgage brokerage, reducing guesswork during a period when every decision carries weight.
What kind of ongoing support do wholesale partners offer brokers?
Beyond onboarding materials, daily access to an account executive keeps brokers moving. That relationship helps originators work through lender tools, technology platforms, and pipeline questions as loan volume grows. Consistent wholesale lending resources of this kind matter more as a brokerage adds loan officers and files.
Why does loan pipeline visibility matter for scaling brokerages?
Full visibility into loan status, from application through closing, gives growing brokerages the confidence to manage an expanding file count without losing track of where each loan stands. A broker juggling dozens of active files needs that transparency to avoid missed conditions and delayed closings.
Together, these elements form the backbone of effective brokerage programs:
- Dedicated business partner coaching on setup, recruiting, and culture
- Centralized video and document libraries for new owners
- Daily account executive access for tools and pipeline support
- End-to-end loan status visibility for scaling teams
Brokerages that combine all four resources scale with fewer stalled files and fewer avoidable mistakes.
How Does Loan Program Variety Expand Broker Opportunity?
Program breadth determines how many borrowers a brokerage can serve without referring business elsewhere. A lender offering only conventional products forces brokers to turn away self-employed buyers, real estate investors, or business owners who need commercial terms. Munshi Capital Inc. structures its wholesale lending resources around a diverse borrower base, from first-time homebuyers to seasoned investors. Brokers keep more deals in-house.
Residential and commercial programs working together matter most here. A broker who can originate FHA, VA, USDA, bank statement, DSCR, and hard money loans under one lending partner covers nearly every borrower profile that walks through the door. That range turns a single brokerage relationship into a full-service pipeline, rather than a patchwork of specialty lenders.
What loan categories should a broker expect access to?
A well-rounded brokerage programs lineup spans both government-backed and investor-focused products. Expect categories including:
- Government loans (FHA, VA, USDA)
- Bank statement loans for self-employed borrowers
- DSCR loans for rental property investors
- Hard money loans for short-term or bridge financing
- Commercial loan programs for business-owner clients
Does capacity to close loans matter as much as product variety?
Product access alone does not scale a brokerage; staffing does. Industry licensing initiatives now move individuals with no mortgage experience to licensed loan originator status in roughly five weeks, according to the September 14, 2024 UWM press release. That timeline matters because training bottlenecks have historically limited how fast brokerages add originators.
Faster licensing removes a structural ceiling on growth. Brokers gain capacity to handle more loan categories simultaneously, without waiting months to build a qualified team. Combined with a broker resources guide covering onboarding. Process support, program variety and staffing speed reinforce each other rather than operating as separate concerns.
What Should Brokers Do Next To Partner Confidently?
Confident partnership starts with reviewing available loan programs before submitting a single file. Brokers evaluating a wholesale lender should expect a clear path from application through underwriting to closing, free of hidden surprises at the table. That clarity protects both the broker’s reputation and the client’s trust.
Preparation matters just as much as process. A dedicated loan specialist takes time to understand each client’s financial goals before matching a program, which gives brokers a stronger foundation for submission. Files built on that groundwork move through underwriting with fewer conditions and fewer delays.
How Does A Transparent Process Benefit Broker Partners?
Transparency removes the guesswork that slows deals down. When underwriting criteria and closing timelines stay visible from the start, brokers can set accurate expectations with clients and avoid last-minute surprises. This kind of wholesale lending resources foundation turns a single transaction into a repeatable, scalable process.
Brokers ready to move forward should take a few deliberate steps:
- Review the full brokerage programs menu, including FHA, VA, USDA, and bank statement options, to match client profiles accurately.
- Consult a broker resources guide before submission to confirm documentation requirements upfront.
- Build a relationship with a dedicated specialist who understands long-term goals, not just the immediate loan.
- Prioritize lenders whose technology and support speed up the path to closing for shared clients.
Why Does A Long-Term Lending Relationship Matter More Than A Single Closing?
A lending approach rooted in honesty and clarity supports repeat business, not just one transaction. Brokers gain more from a partner who treats every file with the same transparency, deal after deal. That consistency, paired with smoother, faster closings, is what separates a dependable wholesale partner from a one-time vendor.
FAQ
What loan programs can brokers access through Munshi Capital’s wholesale program?
Brokers place FHA, VA, USDA, and bank statement loans through Munshi Capital’s residential and commercial suite, plus investor-focused DSCR and hard money products for borrowers outside conventional conforming guidelines.
How does wholesale lending differ from retail lending?
Wholesale lending routes applications through independent brokers who manage the client relationship and negotiate pricing. Retail lenders handle every step themselves with rates fixed by a single institution.
What resources does Munshi Capital provide to wholesale broker partners?
Partners receive underwriting guidance, program comparisons, and dedicated loan specialists supporting transparent, step-by-step closings, along with a broker resources guide covering company setup, recruiting, and scaling strategies.
Conclusion
In closing, Munshi Capital Inc. stands as a dependable partner for borrowers navigating the mortgage landscape with clarity and confidence. The comprehensive loan programs, transparent processes, and personalized guidance outlined throughout this resource demonstrate a commitment to removing complexity from the financing journey. Whether you are a first-time homebuyer or an experienced investor, the combination of modern technology and specialized loan expertise ensures you receive the tailored solutions and honest communication necessary to achieve your financial objectives with integrity and reliability. Property owners weighing their options can request a direct cash offer to understand their position. Sellers seeking a professional valuation can request your property assessment before moving forward with financing decisions.
Leave a Reply